BANKING · BEGINNER GUIDE
Checking Accounts Explained: What Beginners Need to Know
Learn how checking accounts work, how money moves in and out, what balances and fees mean, and how to use an everyday bank account with more confidence.
QUICK ANSWER
The Short Answer
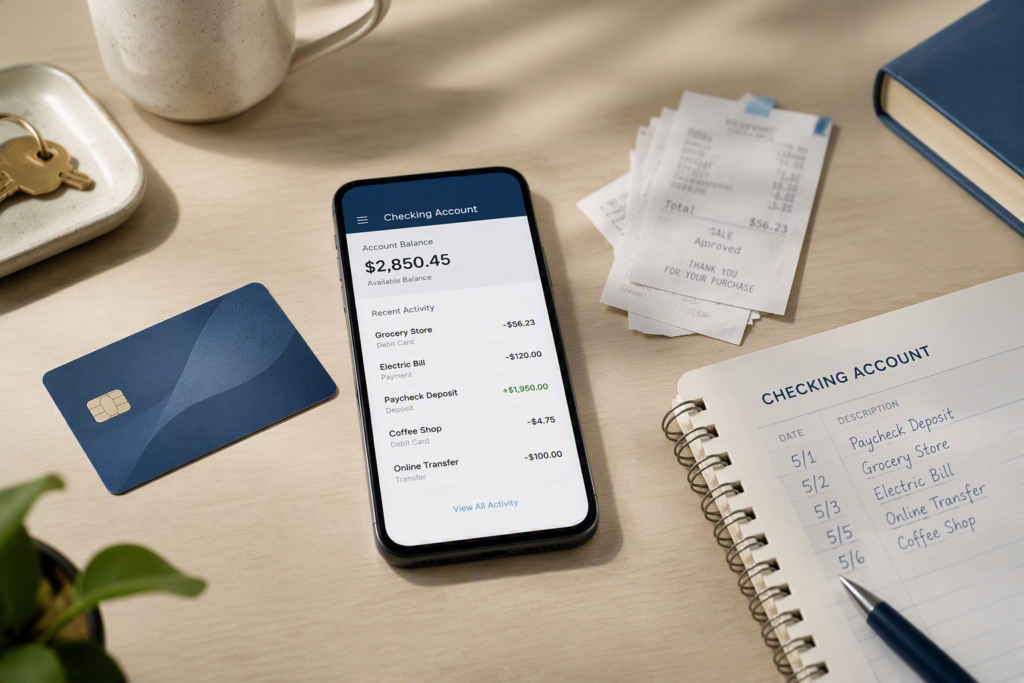
A checking account is a deposit account built for everyday money movement. It can be used to receive income, pay bills, make debit-card purchases, withdraw cash, and send or receive transfers. The most important things to understand are how money becomes available, which fees can apply, how overdrafts are handled, and how to keep track of your available balance.
What You'll Learn
- ✓ How a checking account works in everyday banking.
- ✓ How money moves into and out of the account.
- ✓ The difference between current and available balances.
- ✓ Which fees and overdraft rules can affect the account.
- ✓ How to compare, open, and manage a checking account.
HOW CHECKING ACCOUNTS WORK
How Money Moves Through a Checking Account
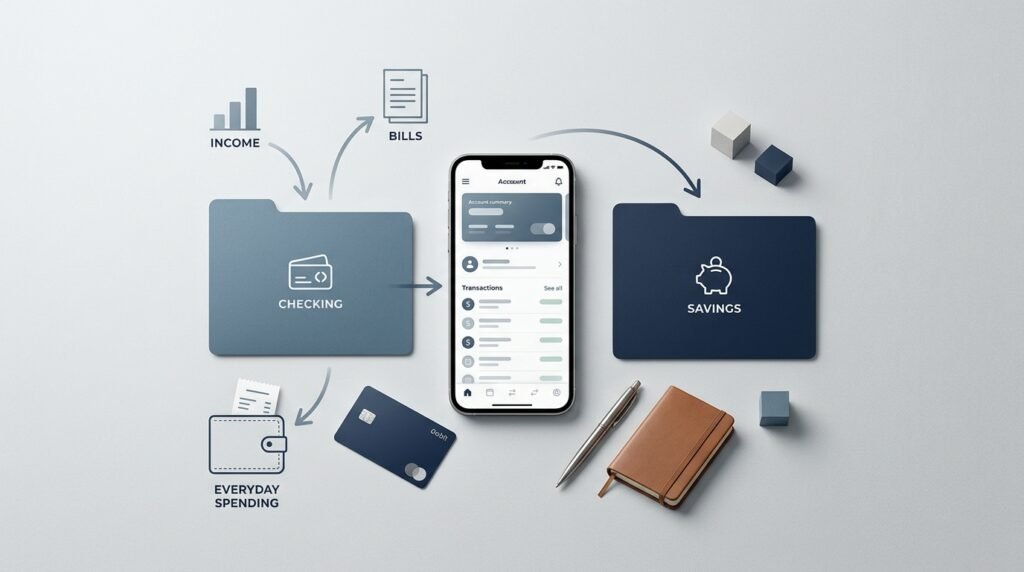
A checking account acts as an operating hub for everyday money. Funds enter through deposits, become available according to the institution's rules, and leave through purchases, payments, withdrawals, transfers, and fees.
Money enters the account
Funds can arrive through direct deposit, bank transfers, check deposits, cash deposits where supported, and other electronic payments.
Funds become available
A deposit appearing in your account does not always mean every dollar is immediately available to spend. Holds and funds-availability rules can affect when deposited money can be used.
Money leaves the account
Funds can leave through debit-card purchases, ATM withdrawals, checks, automatic payments, transfers, person-to-person payments, and account fees.
Your balance keeps changing
Transactions can remain pending before they fully post. That is why your current balance and available balance may show different amounts at the same time.
The key is to track money that is actually available for new transactions, not just deposits or payments that appear in your account history.
UNDERSTAND THE DIFFERENCE
Checking vs. Savings: Different Accounts for Different Jobs
Checking and savings accounts can both hold money, but they are generally designed for different purposes. Checking accounts are built around frequent money movement, while savings accounts are typically better suited to money you plan to keep for future use.
Purpose
Checking is generally designed for everyday transactions. Savings is generally designed for money you want to keep for later.
Spending Access
Checking accounts commonly provide debit-card, ATM, bill-pay, and sometimes check-writing access. Savings-account access can be more limited.
Transaction Frequency
Checking accounts are intended to handle frequent deposits, purchases, payments, withdrawals, and transfers.
Interest
Some checking accounts pay interest, but savings accounts more commonly pay interest on deposited funds. Rates and terms vary by institution.
Best Use
Checking usually works best for money that needs to move. Savings usually works better for money you want to separate from everyday spending.
The account's job matters more than the label
A checking account is typically the better operating account for income, bills, purchases, cash withdrawals, and other frequent transactions. A savings account is generally better suited to money that does not need to move as often.
That does not mean every checking or savings account works the same way. Fees, interest rates, balance requirements, transaction access, and digital features depend on the institution and the specific account.
CORE PRINCIPLE
Use checking primarily for money that needs to move and savings primarily for money you want to set aside. The exact structure should still reflect the terms of the accounts available to you.
LEARN THE CORE MECHANICS
The Core Building Blocks of a Checking Account
Once you understand how money moves through a checking account, the next step is learning the mechanics that affect everyday use: balances, account features, fees, overdrafts, payment methods, and automatic transactions.
BALANCES
Understand Current and Available Balances
One of the most important checking-account concepts is the difference between the balance already recorded on the account and the amount actually available for new transactions.
Terminology can vary by institution, but a current or ledger balance generally reflects transactions that have already posted. An available balance may also account for certain pending transactions, holds, or other activity that affects how much money you can currently use.
KEY IDEA
A deposit or transaction appearing in your account history does not always mean the money has fully settled or is immediately available to use.
FEATURES
Know Which Features Your Account Includes
Checking accounts can look similar on the surface while offering very different ways to access, move, and monitor your money.
The exact combination depends on the institution and account, so compare the features you are likely to use rather than assuming every checking account works the same way.
- Debit-card access for purchases and ATM withdrawals.
- ATM networks and possible out-of-network access.
- Mobile and online banking.
- Mobile check deposit where supported.
- Account alerts and debit-card controls.
- Check-writing privileges on accounts that offer them.
- Electronic transfers and bill-payment tools.
KEY IDEA
A useful checking account should fit the way you actually receive money, make payments, access cash, and monitor transactions.
FEES
Understand Which Fees Can Apply
A checking account can have no monthly maintenance fee and still charge for other services. Fee structures differ by institution, account type, and how the account is used.
Some institutions also provide ways to waive a monthly fee, such as maintaining a specified balance or receiving qualifying direct deposits. The exact requirements should be confirmed in the account disclosures.
- Monthly maintenance or service fees.
- Out-of-network ATM fees.
- Overdraft fees where applicable.
- Returned-item or nonsufficient-funds fees where applicable.
- Stop-payment fees.
- Check-ordering fees.
- Wire-transfer or expedited-service fees.
BETTER QUESTION
Instead of asking whether an account has any fees, ask which fees could realistically apply to the way you plan to use it.
OVERDRAFTS
Know What Can Happen When Funds Are Insufficient
An overdraft occurs when there is not enough money in the account to cover a transaction but the financial institution pays the transaction anyway.
What happens when funds are insufficient depends on the transaction type, the institution's policies, and the terms of the account.
- The transaction may be declined.
- The institution may pay it and create a negative balance.
- An overdraft fee may apply when permitted.
- A linked account may cover the shortage if that service is enabled.
- A payment may be returned unpaid.
IMPORTANT DISTINCTION
Federal rules include specific opt-in requirements before an institution can charge an overdraft fee for paying covered ATM and one-time debit-card transactions through its overdraft service. Other transaction types can be treated differently.
ACCOUNT ACCESS
Understand Debit Cards, ATMs, and Checks
A checking account can provide several ways to access the same pool of deposited money. Each method works a little differently.
A debit card generally uses money associated with your deposit account rather than creating a credit-card balance. ATMs provide cash access and sometimes other services, while checks instruct the institution to pay money from the account when they are presented and processed.
- Check whether an ATM is inside your institution's fee-free network before withdrawing cash.
- Remember that debit-card transactions can remain pending before they fully post.
- Treat money committed to an outstanding check as already spent, even before the check clears.
KEY IDEA
Different payment methods can affect your available balance at different times, even when they all draw from the same checking account.
AUTOMATION
Use Direct Deposit and Automatic Payments Carefully
Direct deposit can move qualifying wages, benefits, or other payments electronically into a checking account. Some institutions also use qualifying direct deposits as one way to meet monthly-fee waiver requirements.
Automatic payments work in the opposite direction by moving money out of the account for recurring obligations such as rent, utilities, insurance, subscriptions, or loan payments.
- Know when regular deposits are expected to arrive.
- Track scheduled automatic withdrawals.
- Review recurring charges periodically.
- Keep enough available funds for payments that are about to post.
KEY IDEA
Automation can make everyday banking easier, but it works best when you still monitor your available balance and upcoming transactions.
VERESTLY FRAMEWORK
The Checking Account Control Loop
A checking account is easier to manage when you use a repeatable routine instead of reacting to each transaction individually. The Verestly Checking Account Control Loop organizes the main habits into five practical steps.
Know When Money Arrives
Understand when regular deposits are expected, how they enter the account, and when the funds are actually available to use.
Watch Balances and Transactions
Review your available balance, pending transactions, account alerts, and recent activity so changes do not go unnoticed.
Treat Committed Money as Unavailable
Account for checks, automatic payments, pending purchases, and other transactions that have not fully posted before using the same money again.
Compare Expected and Posted Activity
Check that deposits, purchases, withdrawals, fees, and recurring payments posted as expected, and investigate transactions you do not recognize.
Protect Access to the Account
Use strong account-security practices, protect your debit card and login credentials, and report lost cards or suspicious transactions promptly.
THE CORE IDEA
Good checking-account management is less about watching every dollar constantly and more about maintaining a reliable loop: know what is coming in, monitor what is happening, reserve money already committed, reconcile the account, and protect access to it.
The Checking Account Control Loop is a Verestly educational framework, not an official banking rule or requirement.
REAL-LIFE EXAMPLE
What Checking Account Management Can Look Like in Practice
Checking-account problems often come from timing rather than from a single large purchase. The example below shows how pending transactions, automatic payments, and available funds can interact during a normal week.
STARTING POINT
Meet Maya
Maya uses one checking account for direct deposit, everyday purchases, rent, and utility payments. A paycheck has arrived, but several transactions are still pending or scheduled.
The goal is not to predict the bank's exact posting order. It is to avoid treating money already committed to upcoming transactions as available for new spending.
| Current balance | $2,150 |
|---|---|
| Pending debit-card purchases | − $180 |
| Outstanding check | − $250 |
| Rent scheduled tomorrow | − $1,100 |
| Utility autopay scheduled | − $140 |
| Amount Maya treats as uncommitted | $480 |
APPLYING THE FRAMEWORK
Maya Uses the Checking Account Control Loop
FUND
Confirm What Has Arrived
Maya confirms that the paycheck has posted and checks how much of the deposit the institution shows as available.
MONITOR
Review Pending Activity
Maya reviews pending debit-card purchases, recent account activity, and upcoming automatic payments before making another purchase.
RESERVE
Set Aside Money Already Committed
Maya mentally reserves the money needed for the outstanding check, rent, utility payment, and pending purchases rather than treating the full displayed balance as spendable.
RECONCILE
Check What Actually Posts
Over the next few days, Maya compares expected transactions with the activity that actually posts and checks for unfamiliar charges or unexpected fees.
PROTECT
Keep Account Access Secure
Maya keeps transaction alerts enabled, protects account credentials, and is prepared to contact the institution promptly if an unfamiliar transaction appears.
THE TAKEAWAY
The Displayed Balance Is Only Part of the Picture
Maya avoids spending money twice by accounting for transactions that are pending, scheduled, or otherwise already committed. This does not replace the institution's available-balance calculation, but it provides an additional practical check before new spending.
This example is illustrative. Transaction posting, holds, balance calculations, overdraft treatment, and payment timing vary by financial institution, account terms, transaction type, and other circumstances.
CHOOSE WHAT MATTERS MOST
What Should You Look for in a Checking Account?
The right checking-account features depend on how you expect to use the account. Start with the issue most likely to affect your everyday banking, then compare the account terms that matter for that situation.
IF THIS SOUNDS LIKE YOU
You want to keep routine account costs low
If monthly fees are your main concern, compare maintenance charges, waiver requirements, minimum-balance conditions, ATM fees, and other charges you are realistically likely to encounter.
IF THIS SOUNDS LIKE YOU
Your balance sometimes gets close to zero
If timing is tight between deposits and payments, pay close attention to overdraft policies, transaction declines, linked-account options, balance alerts, and how the institution displays available funds.
IF THIS SOUNDS LIKE YOU
You rely heavily on ATMs or digital banking
If convenience matters most, compare ATM access, mobile deposits, transfers, account alerts, debit-card controls, customer support, and any branch access you expect to use.
IF THIS SOUNDS LIKE YOU
You mainly want a reliable everyday account
If your needs are straightforward, focus on the fundamentals: manageable fees, convenient access, clear balance information, useful alerts, appropriate overdraft treatment, and applicable federal deposit or share insurance.
BEFORE YOU OPEN AN ACCOUNT
Compare the Account Terms, Not Just the Headline Offer
Review the fee schedule, balance requirements, ATM access, overdraft treatment, digital tools, and applicable deposit insurance before deciding whether an account fits your needs.
Practical · Beginner-friendly · Focused on everyday banking
PRACTICAL VERESTLY RESOURCE
Review a Checking Account Before You Rely on It
A checking account can look simple until fees, balance rules, ATM access, or overdraft policies start affecting everyday use. Use this quick review to focus on the account terms that are most likely to matter.
- ✓ Check monthly fees and the exact requirements for avoiding them.
- ✓ Review ATM access, balance information, and overdraft treatment.
- ✓ Confirm the features and protections you expect before making the account your everyday banking hub.
Beginner-friendly · Practical · No product recommendation
START HERE
Does this checking account fit the way you actually bank?
WANT MORE VERESTLY RESOURCES?
Explore additional worksheets, guides, and practical resources for organizing everyday banking and other parts of your financial life.
PUT IT INTO ACTION
Your 30-Day Checking Account Action Plan
You do not need to change everything about your banking routine at once. Use the next 30 days to understand your account terms, improve transaction visibility, reduce avoidable fees, and build a simple routine for managing your checking account.
TODAY
15–30 minReview Your Checking Account Terms
Start by checking what your account actually costs and how it works. Review the current fee schedule, balance requirements, overdraft treatment, ATM access, and the features included with the account.
- Find the account's current fee schedule.
- Check whether a monthly maintenance fee applies.
- Review any fee-waiver or minimum-balance requirements.
- Confirm how the account handles insufficient funds.
WEEK 1
Build visibilityLearn How Your Balance Changes
Watch how deposits, debit-card purchases, checks, and automatic payments appear in your account. Pay particular attention to pending transactions and the difference between displayed balances.
- Compare your current and available balances.
- Notice which transactions remain pending before posting.
- Identify outstanding checks or scheduled payments.
WEEK 2
Reduce frictionTurn On the Alerts You Will Actually Use
Account alerts can make it easier to notice changes without checking the app constantly. Use the options your institution provides and focus on alerts that help you manage balances and spot unusual activity.
- Enable transaction notifications where available.
- Consider a low-balance alert.
- Review debit-card and security notification settings.
WEEK 3
Review automationAudit Automatic Deposits and Payments
Make a simple list of recurring money entering and leaving the account. This can help you see which transactions are already committed before making new spending decisions.
- Confirm recurring direct deposits.
- List automatic bill payments and subscriptions.
- Remove or update recurring payments that are no longer needed.
- Check that scheduled payments align with available funds.
WEEK 4
Build the routinePut the Checking Account Control Loop Into Practice
Finish the month by turning what you learned into a simple routine: confirm deposits, monitor activity, reserve money already committed, reconcile transactions, and protect access to the account.
- Choose a regular time to review account activity.
- Compare expected transactions with what actually posted.
- Investigate unfamiliar transactions or unexpected fees.
- Repeat the routine often enough to stay aware without needing to monitor the account constantly.
KEEP IT SIMPLE
The Goal Is a Reliable Banking Routine
You do not need to watch your checking account every hour. The goal is to understand how your account works, know which transactions are already committed, notice problems early, and maintain a repeatable routine that supports everyday money management.
AVOID THESE PITFALLS
Common Checking Account Mistakes to Avoid
Checking-account problems often come from small misunderstandings about balances, timing, fees, or automatic transactions. These are some of the most common mistakes to watch for.
Treating the Displayed Balance as Fully Spendable
Pending purchases, outstanding checks, holds, or scheduled payments can make the amount available for new spending different from the balance you first see.
Review your available balance and keep track of transactions that are already committed but have not fully posted.
Assuming a Deposit Is Immediately Available
A deposit can appear in your account before all of the funds are available to use. Availability can depend on the deposit type, amount, account, and institution.
Check the amount your institution identifies as available before relying on a recent deposit for another payment.
Ignoring the Account's Fee Schedule
An account with no monthly maintenance fee can still charge for certain ATMs, overdrafts, wires, checks, stop payments, or other services.
Review the current fee schedule and focus on the charges that could realistically apply to the way you use the account.
Forgetting About Automatic Payments
Recurring bills and subscriptions can reach the account after you have already committed the same money elsewhere.
Keep a simple list of recurring withdrawals and review them periodically so scheduled payments do not become surprises.
Assuming All Overdrafts Work the Same Way
Overdraft treatment can depend on the transaction type, the institution's policies, and whether certain services have been selected or enabled.
Read the account's overdraft disclosures and understand what happens when available funds are insufficient.
Waiting Too Long to Question Suspicious Activity
Unfamiliar transactions, lost debit cards, or unexpected account changes deserve prompt attention. Reporting timing can matter when consumer protections apply.
Review account activity regularly and contact your financial institution promptly when something appears incorrect or unauthorized.
FREQUENTLY ASKED QUESTIONS
Checking Account Questions Beginners Often Ask
These short answers cover common questions about balances, debit cards, fees, overdrafts, deposit protection, and everyday checking-account management.
Is a checking account the same as a debit card?
No. A checking account is the deposit account that holds the money. A debit card is one tool that can be connected to that account and used for purchases or ATM withdrawals. Some checking accounts may also provide checks, transfers, bill payment, and other ways to access funds.
Why is my available balance different from my current balance?
The terminology varies by institution, but the difference often reflects pending transactions, holds, deposits that are not fully available, or other activity that has not completed the institution's posting process.
Review current and available balances →Can a checking account charge a monthly fee?
Yes. Some checking accounts charge monthly maintenance fees, while others do not. An institution may also offer ways to waive a fee, such as meeting certain balance or qualifying direct-deposit requirements. The exact terms should be listed in the account disclosures.
Review checking-account fees →Can my bank charge an overdraft fee for any transaction?
Not necessarily. Federal rules include specific opt-in requirements before a financial institution can charge an overdraft fee for paying covered ATM and one-time debit-card transactions through its overdraft service. Checks and certain recurring electronic payments can be treated differently.
Review how overdrafts work →Are checking accounts federally insured?
Eligible checking deposits at an FDIC-insured bank are covered by FDIC deposit insurance subject to applicable ownership and coverage rules. At a federally insured credit union, qualifying member deposits are insured through the National Credit Union Share Insurance Fund administered by the NCUA.
The standard federal insurance amount is generally $250,000 per depositor, per insured institution, for each applicable ownership category. Multiple accounts in the same ownership category at the same institution may be combined when coverage is calculated.
How often should I review my checking account?
There is no universal schedule. A useful routine is to review the account often enough to notice pending transactions, upcoming automatic payments, unexpected fees, and unfamiliar activity before they become larger problems. Alerts can reduce the need to check manually throughout the day.
Review the 30-day account management plan →CONTINUE YOUR JOURNEY
Where to Go Next
Once you understand the basics of a checking account, the next useful step depends on what you need to improve: choosing the right account, reducing fees, understanding account protection, or building a more reliable banking routine.
COMPARE ACCOUNTS
Understand Which Account Fits Which Job
Start here if you are still deciding how checking and savings accounts should fit into your everyday banking setup.
REDUCE COSTS
Understand Fees and Overdraft Risk
Choose this path if fees, low balances, or overdraft risk are the main concerns affecting how you use your checking account.
PROTECT YOUR ACCOUNT
Learn How Checking-Account Protection Works
Use this path if you want to better understand federal deposit protection, suspicious activity, and the basic safeguards that matter when using a checking account.
BUILD A ROUTINE
Make Everyday Account Management Easier
Choose this path if you already have a checking account and want a simpler system for monitoring transactions, preparing for automatic payments, and keeping track of committed funds.
WANT MORE PRACTICAL RESOURCES?
Keep Building Your Everyday Banking System
Explore Verestly resources for additional guides, worksheets, and tools designed to make everyday money management easier to understand and maintain.
SOURCES & METHODOLOGY
How We Built This Guide
Verestly prioritizes primary government sources and financial regulators when explaining banking rules, account mechanics, consumer protections, and deposit insurance. For this guide, we reviewed current federal guidance relevant to checking accounts, fees, overdrafts, funds availability, and federally insured deposits.
LAST REVIEWED
September 2026
We periodically review this guide for changes to banking rules, consumer protections, deposit-insurance guidance, source quality, and other information that may affect readers.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and actionable resources that help readers better understand everyday financial decisions.
View author profile →VERESTLY NEWSLETTER
Make Everyday Money Decisions Easier to Understand
Get practical financial guides, tools, and beginner-friendly resources designed to help you understand how your money works and make more informed decisions.
- Beginner-friendly financial education
- Practical guides and tools
- Clear everyday money systems
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Banking Guides
Continue with three carefully selected guides that expand on checking accounts, everyday banking, and cash management.