INVESTING · BEGINNER GUIDE
Saving vs. Investing: What Is the Difference?
Learn how saving and investing differ in risk, liquidity, time horizon, and growth potential—and how each can play a different role in your financial goals.
QUICK ANSWER
The Short Answer
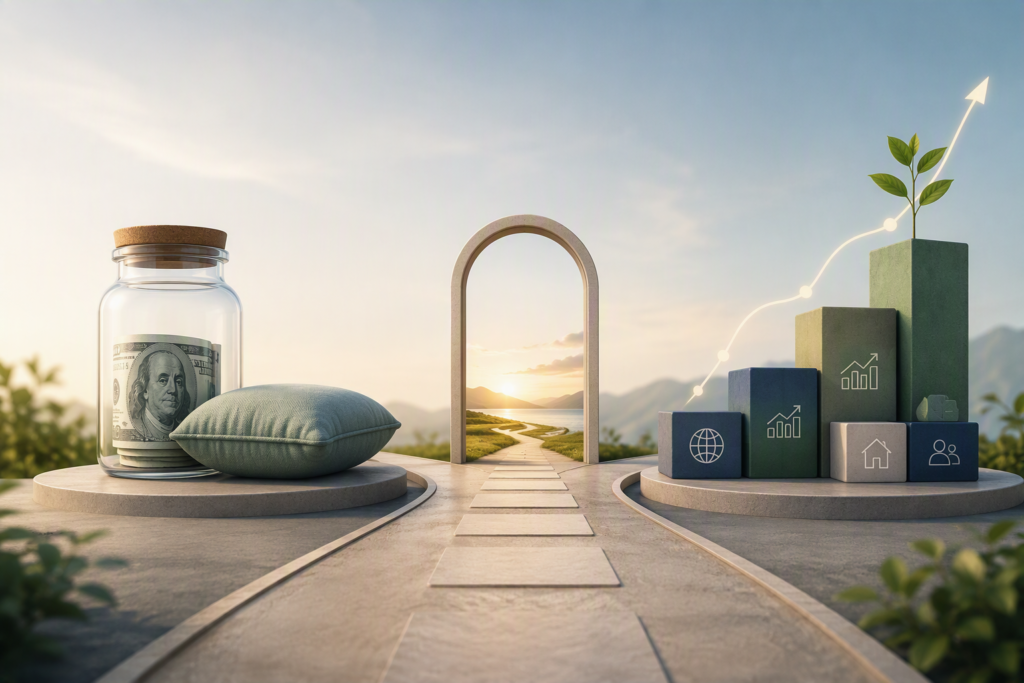
Saving and investing both involve setting money aside, but they serve different purposes. Saving generally prioritizes stability and access to money, while investing accepts more uncertainty and the possibility of loss in exchange for greater long-term growth potential. The better fit depends on the goal, time horizon, liquidity needs, and how much risk the money can reasonably tolerate.
What You'll Learn
- ✓ The core difference between saving and investing.
- ✓ How risk, liquidity, and time horizon affect the choice.
- ✓ When saving may be more appropriate for a financial goal.
- ✓ When investing may play a larger role.
- ✓ Why saving and investing can both belong in the same financial plan.
WHAT SAVING IS FOR
What Is Saving Designed to Do?
Saving is generally used for money that needs to remain relatively stable and accessible. Its role is less about maximizing growth and more about preserving funds for emergencies, near-term spending, and goals that cannot easily absorb a market decline.
Preserve money you expect to need
Saving can make sense when protecting the amount available matters more than pursuing additional return. That may include money for planned expenses or other goals where a decline could disrupt the plan.
Keep important funds accessible
Money reserved for unexpected costs or near-term goals may need to be available quickly. Many savings products are designed to provide easier access than assets whose market value may fluctuate.
Reduce exposure to market swings
Appropriate savings vehicles generally do not move up and down with financial markets the way securities can. That can be useful when short-term stability is a priority.
Accept a different kind of risk
Saving is not entirely risk-free. Money held for long periods can lose purchasing power if its growth does not keep pace with inflation, and some products may limit how or when funds can be accessed.
The purpose of saving is not to eliminate every financial risk. It is to prioritize stability and access when those qualities matter most for the goal.
COMPARE THE TWO ROLES
The Five Practical Differences Between Saving and Investing
Saving and investing can both support financial goals, but they differ in what they are designed to do. The most useful comparison is not simply which one may earn more—it is how each handles purpose, risk, return potential, liquidity, and time.
Purpose
Saving generally prioritizes preservation and access, while investing generally prioritizes potential long-term growth.
Risk
Savings may reduce exposure to market-price swings, while investments can rise or fall in value.
Return Potential
Savings typically offer more limited growth potential. Investments may offer more, but returns are not guaranteed.
Liquidity
Many savings products emphasize easy access. Investments may be sellable, but the value available at that moment can vary.
Time Horizon
Money needed sooner usually has less room to absorb a decline, while longer-term goals may allow more investment risk.
The trade-off is more important than the label
Saving is not simply the conservative version of investing, and investing is not simply saving with a higher return. Each approach exposes money to a different mix of risks and potential outcomes.
A savings vehicle may help protect money from short-term market declines, but long-term cash holdings can still lose purchasing power to inflation. An investment may offer greater growth potential, but its value can decline when the money is needed.
CORE PRINCIPLE
The right comparison starts with the job the money needs to do, then considers which risks matter most for that goal.
CONSIDER WHEN YOU NEED THE MONEY
Why Your Time Horizon Matters
Your time horizon is the amount of time before you expect to need money for a particular goal. It does not automatically determine whether you should save or invest, but it changes how much weight you may need to give to stability, liquidity, and the possibility of a decline.
START WITH THE GOAL
Every Goal Has Its Own Time Horizon
Money does not have one universal time horizon. The relevant timeframe depends on the specific goal attached to it.
Money reserved for an expense next year has a very different job from money intended for a goal decades away. Treating both pools the same can expose one of them to risks that do not fit its purpose.
KEY IDEA
Start with when the money may be needed—not with which account or investment appears to offer the highest return.
SHORTER HORIZONS
Less Time Can Make a Decline More Disruptive
When money will be needed relatively soon, there may be less opportunity to respond if its value falls shortly before the goal date.
That can make preservation and accessibility especially important for goals that cannot easily be delayed or funded from another source.
- Consider how fixed the goal date is.
- Consider whether the amount needed is negotiable.
- Consider whether a decline would force the goal to be delayed.
- Consider how quickly the money must be available.
HYPOTHETICAL EXAMPLE
The Consequence of a Loss Matters
Suppose you have $8,000 set aside for an essential purchase you expect to make next year.
If that money were invested and its value fell shortly before the purchase, you might need to delay the goal, contribute additional money, or sell the investment for less than you originally contributed.
This example is hypothetical and does not establish a universal rule. It illustrates why the impact of a potential decline can matter as much as the possibility of one.
LONGER HORIZONS
More Time Can Change Which Risks Matter Most
When a goal is much farther away, short-term access may be less important and there may be more capacity to accept fluctuations in value.
That can make investing more relevant for some long-term goals, particularly when growth potential matters. But a longer time horizon does not eliminate investment risk or guarantee a positive return.
IMPORTANT
More time may increase the capacity to accept investment risk, but it never turns an uncertain investment outcome into a guaranteed one.
ACCESS MATTERS TOO
Time Horizon and Liquidity Work Together
Knowing when you may need money is only part of the decision. You also need to consider how quickly the money must be accessible once that need arrives.
Some investments can be sold quickly, but liquidity does not guarantee price stability. An asset may be easy to sell while still being worth less than you expected at the moment you need the money.
- Time horizon asks when you expect to need the money.
- Liquidity asks how easily you can access it.
- Market risk asks what the money may be worth when you do.
AVOID A FALSE CUTOFF
There Is No Universal Date That Separates Saving From Investing
It can be tempting to use a simple rule such as “save before this date and invest after it.” Real decisions are more nuanced.
Two people with the same time horizon may reasonably place different weight on stability, liquidity, and investment risk because their goals, ability to absorb losses, risk tolerance, and wider financial circumstances are different.
CORE PRINCIPLE
Time horizon is a decision factor—not an automatic formula. Consider it together with the goal, liquidity needs, and consequences of a loss.
UNDERSTAND THE RISK
Risk Is More Than Market Volatility
Investing introduces the possibility that the value of your money can decline, but market movement is only one type of financial risk. Saving and investing expose money to different combinations of risk, so the goal is to understand which risks matter most for each goal.
Principal Risk
Investments can fall below the amount originally contributed. Depending on the asset, an investor may lose part or all of the money invested.
Volatility Risk
Investment values can move up and down over time. Those fluctuations can become especially important when money may need to be withdrawn during a market decline.
Liquidity Risk
Some assets may be difficult, costly, or slow to convert into cash. Even investments that can be sold quickly may need to be sold at an unfavorable price.
Inflation Risk
Money that grows more slowly than the cost of living can lose purchasing power over time, even when the account balance itself does not decline.
Goal Risk
A financial strategy can create problems if the value or accessibility of the money does not match when the goal needs to be funded.
THE CORE IDEA
Saving can reduce exposure to some forms of investment risk, but it does not remove every risk. Investing can provide greater growth potential, but it introduces uncertainty and the possibility of loss. The relevant question is which risks the money can reasonably tolerate.
UNDERSTAND PURCHASING POWER
How Inflation Changes the Saving vs. Investing Trade-Off
Saving can help preserve the number of dollars you have, but that does not always mean preserving what those dollars can buy. Inflation can gradually reduce purchasing power when prices rise faster than the money grows.
SIMPLE ILLUSTRATION
More Dollars Can Still Mean Less Purchasing Power
Imagine money in a savings vehicle grows by 2% over a period while the prices of the goods and services you buy rise by 3%.
The account balance increases, but the money may still buy slightly less than before. That is purchasing-power risk.
| Starting amount | $10,000 |
|---|---|
| Illustrative account growth | 2% |
| Illustrative price increase | 3% |
| Core effect | Purchasing power declines |
WHAT THIS MEANS
Inflation Creates a Different Kind of Risk
SAVE
Saving Can Prioritize Stability
Appropriate savings vehicles can help reduce exposure to market-price swings and keep money available for nearer-term needs.
INFLATION
Stability Does Not Guarantee Purchasing Power
If the money grows more slowly than prices over time, the nominal balance may rise while its real purchasing power falls.
TIME
The Trade-Off Can Grow Over Longer Periods
For money that may remain untouched for many years, the effect of inflation can become more relevant when deciding whether stability or growth potential deserves greater weight.
INVEST
Investing May Offer More Growth Potential
Investments may provide greater long-term growth potential, but their values can decline and there is no guarantee they will outpace inflation.
MATCH
Match the Risk to the Goal
Money for a near-term need may prioritize stability, while money for a much longer-term goal may place more weight on growth potential and inflation risk.
THE TAKEAWAY
Saving Can Reduce One Risk While Leaving Another
Keeping money stable can be exactly what a short-term goal requires. The trade-off is that long-term cash holdings may lose purchasing power if their growth does not keep pace with inflation. Investing changes that trade-off by adding growth potential along with market risk and the possibility of loss.
This illustration is educational only. The 2% account growth and 3% price increase are hypothetical assumptions, not forecasts or expected future results.
WHEN SAVING MAY FIT BETTER
When Might Saving Deserve More Weight?
Saving may be more appropriate when preserving access to the money matters more than pursuing additional growth. The situations below show why the purpose of the money, the timing of the goal, and the consequences of a loss all matter.
CONSIDER SAVING WHEN
The Money Is Part of an Emergency Reserve
Emergency money may need to be available with little warning. Because the timing is unpredictable, stability and accessibility can matter more than maximizing potential return.
CONSIDER SAVING WHEN
The Goal Is Relatively Near
If you expect to use the money in the foreseeable future, there may be less time to respond if an investment declines shortly before the goal date.
CONSIDER SAVING WHEN
A Decline Would Disrupt an Essential Plan
If losing part of the money would make it difficult to cover an essential expense, complete a planned purchase, or meet a fixed obligation, preserving principal may deserve greater weight.
CONSIDER SAVING WHEN
You Need Reliable Access to a Known Amount
Some goals depend not only on being able to access money, but on having a reasonably predictable amount available when it is needed. Marketable investments may be easy to sell, yet their value can still be lower at that moment.
A USEFUL WAY TO THINK ABOUT IT
Ask What Would Happen If the Money Fell in Value
If a meaningful decline would force you to delay an important goal, borrow money, or miss an essential expense, stability may deserve more weight than growth potential for that particular pool of money.
Continue to the other side of the saving vs. investing decision
WHEN INVESTING MAY FIT BETTER
When Might Investing Deserve More Weight?
Investing may become more relevant when the goal is farther away, the money does not need to remain immediately available, and you can accept the possibility that its value may decline along the way. The trade-off is greater uncertainty in exchange for greater long-term growth potential.
- ✓ The goal has a longer time horizon.
- ✓ The money does not need to remain immediately accessible.
- ✓ You can tolerate fluctuations and the possibility of loss.
Continue to the next step before using the Money-Role Framework
ASK YOURSELF
Can this money reasonably accept more uncertainty?
IMPORTANT DISTINCTION
A long time horizon may increase your capacity to accept investment risk, but it does not guarantee positive returns or eliminate the possibility of loss.
USE BOTH WITH PURPOSE
Saving and Investing Can Work Together
Saving versus investing does not have to be an either-or decision. Different pools of money can serve different purposes at the same time, depending on when the money may be needed, how accessible it should remain, and how much uncertainty the goal can tolerate.
IMMEDIATE NEEDS
High liquidityKeep Emergency Money Accessible
Money reserved for unexpected expenses may need to be available without warning. That can make stability and liquidity more important than pursuing additional return.
- The timing of the need is unpredictable.
- The money may need to be accessed quickly.
- A market decline could reduce the amount available.
NEAR-TERM GOALS
Stability mattersSeparate Money for Planned Spending
Money intended for a purchase or obligation in the foreseeable future may need a relatively predictable value when the goal date arrives.
- Identify when the money will probably be needed.
- Consider whether the goal date can be delayed.
- Consider what would happen if the balance fell.
LONGER-TERM GOALS
Growth may matter moreConsider Where Investing May Play a Role
When a goal is much farther away and the money does not need to remain immediately available, investing may become more relevant because long-term growth potential can carry more weight.
- The goal has a longer time horizon.
- Short-term market fluctuations may be more tolerable.
- Investment losses are still possible.
MULTIPLE GOALS
Different jobsLet Different Dollars Serve Different Purposes
You may simultaneously keep cash for emergencies, save for a planned purchase, and invest money intended for a distant goal. Those choices are not contradictory because each pool of money has a different job.
- Separate goals instead of treating all money the same.
- Match liquidity to the purpose of each goal.
- Match risk to the consequences of a potential loss.
REVIEW OVER TIME
Goals can changeRevisit the Role as the Goal Gets Closer
A goal that is far away today will eventually become a nearer-term goal. As timing, liquidity needs, or financial circumstances change, the way you balance stability and growth potential may need to change too.
- Review the goal's remaining time horizon.
- Reassess how much loss the goal can tolerate.
- Reconsider how accessible the money needs to be.
THE KEY DISTINCTION
You Do Not Have to Choose Between Being a Saver and an Investor
Saving and investing are tools for different financial jobs. The more useful question is whether each pool of money is being managed in a way that matches its purpose, time horizon, liquidity needs, and capacity for loss.
AVOID THESE PITFALLS
Common Financial Mistakes to Avoid
Most financial setbacks do not come from one dramatic mistake. They usually come from small structural problems that repeat over time. These are some of the most common ones to watch for.
Trying to Fix Everything at Once
When every financial goal feels urgent, it is easy to spread your money too thin and make little progress anywhere.
Choose the financial issue creating the most pressure and give that priority more attention first.
Building a Budget Around Ideal Behavior
A budget that assumes perfect spending habits may look impressive on paper but fail as soon as real life changes.
Build your plan around realistic spending patterns, irregular expenses, and normal monthly variation.
Ignoring Irregular Expenses
Annual fees, car maintenance, gifts, insurance costs, and other non-monthly expenses can make a stable budget appear broken.
Treat predictable irregular expenses as part of your monthly planning instead of waiting for them to become emergencies.
Using Credit to Replace Missing Cash Flow
Credit can be useful, but repeatedly using it to cover routine expenses may signal that your underlying cash-flow system needs attention.
Diagnose the recurring gap and work on reducing the pressure before relying on more borrowing.
Optimizing Before Building Stability
Chasing higher returns, perfect credit metrics, or minor financial optimizations can distract from more important weaknesses in your foundation.
Strengthen cash flow, emergency savings, and expensive debt management before focusing heavily on optimization.
Treating a Setback as a Failed Plan
A surprise expense or difficult month does not necessarily mean your financial system is broken.
Review what changed, adjust the system, and continue rather than restarting from zero every time.
FREQUENTLY ASKED QUESTIONS
Questions Beginners Often Ask
These short answers cover common questions that come up when you are trying to build a stronger financial foundation.
Should I save money or pay off debt first?
It often makes sense to maintain some accessible cash while also addressing expensive debt, especially if having no savings would force you to borrow again after the next unexpected expense.
Learn how to prioritize competing money goals →How much emergency savings should I build first?
Your first target does not have to be your final emergency fund. A smaller starter buffer can provide useful protection while you continue improving cash flow, debt, and savings.
Explore emergency-fund guidance →What if my income changes from month to month?
With irregular income, focus on essential spending, conservative income assumptions, cash-flow timing, and building reserves that reduce the impact of lower-income months.
Learn how to budget with irregular income →Do I need to track every purchase?
Not necessarily. Detailed tracking can be useful, but the goal is to understand your spending patterns well enough to make reliable decisions. Use as much detail as helps you.
When should I start investing?
Investing can become part of your plan once your immediate financial situation is stable enough to support long-term contributions without repeatedly pulling money back out for short-term emergencies.
Explore investing for beginners →How often should I review my financial plan?
A short monthly review is often enough for routine adjustments, while major life changes may require a deeper review sooner.
See how to review your budget each month →CONTINUE FROM HERE
What to Learn Next
Once you understand the difference between saving and investing, the next step depends on the job your money needs to do. Use the paths below to continue with the topic that best matches that role.
BUILD RESILIENCE
Strengthen Your Emergency Savings
Start here if the money's main job is protecting you from unexpected expenses and helping you avoid relying on debt when something unplanned happens.
LEARN THE BASICS
Build Your Investing Foundation
Choose this path if the goal is farther away and you want to understand how investing works before making decisions about specific investment options.
UNDERSTAND RISK
Learn How Investment Risk Works
Continue here if you want to go deeper into volatility, diversification, time horizon, and the different types of risk that can affect an investment portfolio.
BUILD THE PORTFOLIO
Understand How Investments Fit Together
Once the saving-versus-investing decision is clearer, the next layer is understanding how diversification, asset allocation, costs, and different investment types can affect a portfolio.
KEEP THE DECISION GOAL-BASED
Give the Money a Job Before Choosing the Product
Start with the goal, time horizon, liquidity need, and consequence of a potential loss. Those factors can help you decide whether the next topic to explore is saving, investing, or a deeper portfolio concept.
SOURCES & METHODOLOGY
How We Built This Guide
Verestly reviewed primary U.S. regulatory and government sources to verify the differences between saving and investing, including investment risk, time horizon, inflation risk, liquidity, and federal deposit-insurance rules.
LAST REVIEWED
September 2026
This guide was reviewed for source quality, investment-risk language, deposit-insurance accuracy, search-intent ownership, and consistency with Verestly's investing editorial standards.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical frameworks, and risk-aware investing education that helps readers make more informed financial decisions.
View author profile →VERESTLY NEWSLETTER
Make Clearer Saving and Investing Decisions
Get practical financial education, investing guides, and beginner-friendly resources designed to help you understand financial trade-offs before making decisions.
- Clear investing education
- Practical financial frameworks
- New guides and Verestly tools
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Guides
Continue with three selected guides that help you move from saving and investing fundamentals into the next relevant financial concept.