INVESTING · FOCUSED ANSWER
ETF vs. Mutual Fund: What Beginners Should Know
ETFs and mutual funds can hold similar investments, but they differ in how they trade, how they are priced, what they may cost, and how their structures can affect taxes. Here are the differences that matter most for beginners.
IN PLAIN ENGLISH
The Short Answer
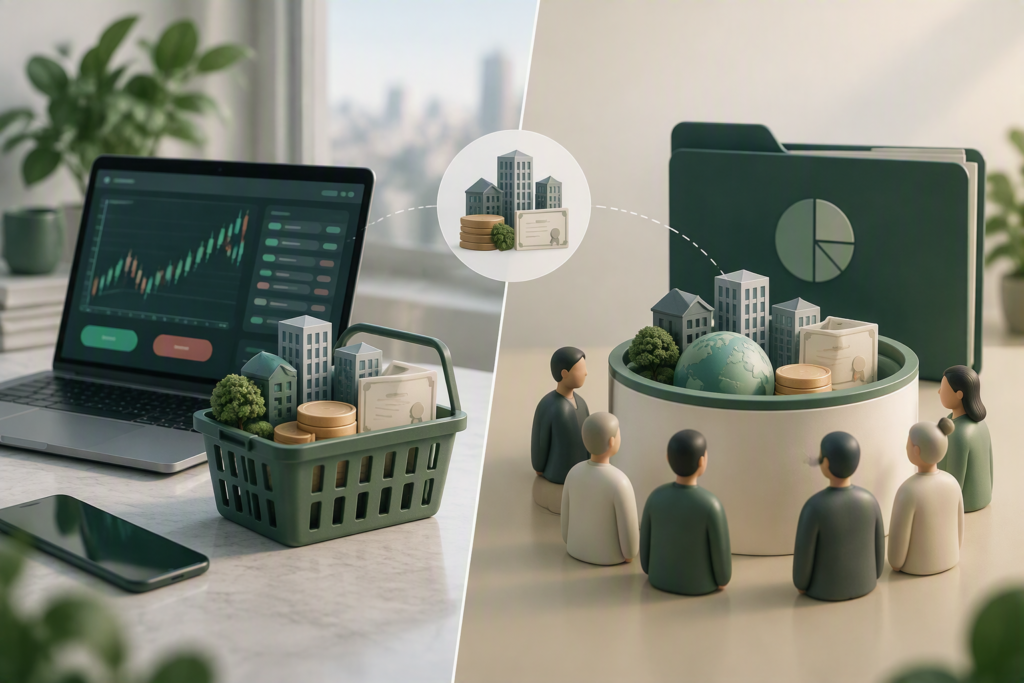
ETFs and mutual funds are both pooled investments that can hold stocks, bonds, or other assets. The main difference is how investors buy and sell their shares.
ETFs trade on an exchange during the market day at market prices. Mutual fund transactions generally occur at the fund’s next calculated net asset value, or NAV. Either structure can follow an index or use active management.
CORE DISTINCTION
The fund structure changes how shares are traded and priced, not necessarily what the fund owns.
HOW IT WORKS
How ETFs and Mutual Funds Are Bought and Priced
The biggest structural difference between ETFs and mutual funds is how investors buy and sell shares. ETFs trade on exchanges during the market day, while mutual funds generally transact at the fund's next calculated net asset value, or NAV.
ETF
ETF Shares Trade During the Market Day
Retail investors generally buy and sell ETF shares through a brokerage account on a securities exchange. The market price can change throughout the trading day.
MUTUAL FUND
Mutual Fund Orders Use the Next Calculated NAV
Mutual fund shares generally do not trade continuously on an exchange. Orders are usually completed at the fund's next calculated NAV after the order is received.
IMPORTANT DETAIL
An ETF's Market Price Can Differ From Its NAV
An ETF has a net asset value based on the value of the investments it holds, but investors trade ETF shares at market prices determined by supply and demand on the exchange.
As a result, an ETF can trade at a premium when its market price is above NAV or at a discount when its market price is below NAV.
KEY PRINCIPLE
Intraday trading is a feature of the ETF structure, not evidence that an ETF is automatically a better investment. What the fund owns, its strategy, costs, risks, and role in a portfolio still matter more.
SIMPLE EXAMPLE
Comparing the Costs of Two Similar Funds
Two funds can follow a similar strategy and still have different costs. The useful comparison is not just ETF versus mutual fund, but the total cost of owning each specific fund.
HYPOTHETICAL FUND 1
ETF
HYPOTHETICAL FUND 2
Mutual Fund
TOTAL COST VIEW
The Expense Ratio Is Only Part of the Comparison
The ETF has the lower expense ratio in this example, but that alone does not establish that it will always cost less to own. Transaction costs, spreads, account features, sales charges, and other applicable fees can change the comparison.
WHAT THIS SHOWS
A lower expense ratio can be an advantage, but the ETF or mutual-fund label does not determine total cost by itself. Compare the actual fund expenses and any additional costs tied to buying, holding, or selling the fund.
This is a simplified hypothetical example for education only. Actual fund expenses, spreads, commissions, loads, account fees, and other costs vary by fund and brokerage arrangement.
WHAT THIS MEANS FOR YOU
How Taxes and Fund Distributions Can Differ
Taxes matter most when a fund is held in a taxable account. Both ETFs and mutual funds can distribute income and capital gains, but their structures can affect how often taxable capital-gain distributions occur.
TAXABLE ACCOUNTS
Distributions Can Create Tax Consequences
A fund may distribute dividends, interest, or capital gains to shareholders. In a taxable account, those distributions may have tax consequences even when the money is automatically reinvested.
ETF STRUCTURE
Some ETFs May Distribute Fewer Capital Gains
Many ETFs can create and redeem shares through in-kind transactions. This structure can reduce the need for the fund to sell investments for cash and may help limit capital-gain distributions in some cases.
NO AUTOMATIC WINNER
Do Not Assume Every ETF Is More Tax-Efficient
ETFs can still make taxable distributions, and mutual funds can vary widely in how much taxable activity they generate. The tax impact depends on the specific fund, its portfolio activity, and the type of account holding it.
ACCOUNT TYPE MATTERS
The Same Tax Difference May Matter Less in a Tax-Advantaged Account
The tax treatment of fund distributions depends partly on the account in which the investment is held. That means a structural tax advantage that matters in a taxable brokerage account may have different relevance inside a tax-advantaged account.
PRACTICAL RULE
Treat tax efficiency as one comparison factor, not as proof that one fund structure is universally better. Costs, holdings, strategy, risk, and account type still matter.
COMMON MISUNDERSTANDINGS
What Beginners Often Get Wrong About ETFs and Mutual Funds
The ETF or mutual-fund label tells you how the fund is structured, but it does not tell you everything about how the fund invests, what it owns, or how risky it may be.
MISUNDERSTANDING
“ETF Means Index Fund”
An ETF describes a fund structure, not a specific investment strategy. Some ETFs track an index, while others use active management.
BETTER WAY TO THINK ABOUT IT
Separate the fund's structure from its strategy. An index fund can be packaged as either an ETF or a mutual fund.
MISUNDERSTANDING
“Mutual Funds Are Always Actively Managed”
Mutual funds can also follow passive index strategies. The mutual-fund structure does not automatically mean a portfolio manager is selecting securities actively.
BETTER WAY TO THINK ABOUT IT
Check whether the specific fund is passive or active instead of assuming its management style from the wrapper.
MISUNDERSTANDING
“ETFs Are Always Cheaper”
Many ETFs have low expense ratios, but the structure alone does not guarantee lower total costs. Bid-ask spreads, brokerage costs, fund expenses, and mutual-fund fees can all affect the comparison.
BETTER WAY TO THINK ABOUT IT
Compare the actual costs of the specific funds rather than assuming one wrapper is automatically less expensive.
MISUNDERSTANDING
“The Fund Type Tells Me How Risky It Is”
Risk depends much more on what the fund owns and how concentrated its strategy is. A narrowly focused ETF may be riskier than a broadly diversified mutual fund, and the reverse can also be true.
BETTER WAY TO THINK ABOUT IT
Look first at the fund's holdings, strategy, diversification, and risks. The ETF or mutual-fund label is only one structural characteristic.
REMEMBER
Start with what the fund owns and how it invests. Then compare costs, trading structure, taxes, and how the fund fits into the rest of your portfolio.
FREQUENTLY ASKED QUESTIONS
Common Questions About ETFs and Mutual Funds
These questions cover some of the most important distinctions beginners should understand before comparing specific funds.
Are ETFs always cheaper than mutual funds? +
No. Some ETFs have very low expense ratios, but some mutual funds do as well. ETFs can also involve bid-ask spreads or brokerage-related costs, while mutual funds may have sales charges, transaction fees, account fees, or other expenses. Compare the actual total costs of the specific funds you are considering.
Can a mutual fund be an index fund? +
Yes. An index fund describes an investment strategy that seeks to track an index. That strategy can be packaged as either a mutual fund or an ETF. Likewise, both ETFs and mutual funds can use active management.
Are ETFs safer than mutual funds? +
Not automatically. Investment risk depends primarily on what the fund owns, how concentrated it is, and the strategy it follows. Either an ETF or a mutual fund can rise or fall in value, and diversification does not eliminate investment risk.
Do you need a brokerage account to buy an ETF? +
Retail investors generally buy and sell ETF shares through a brokerage account because ETFs trade on securities exchanges. Mutual funds may be available through a brokerage account, retirement plan, or directly from a fund company, depending on the fund and account arrangement.
Are ETFs always more tax-efficient than mutual funds? +
No. Some ETFs may distribute fewer capital gains because of how shares are created and redeemed, but the result depends on the specific fund, its portfolio activity, and the account in which it is held. Both ETFs and mutual funds can make taxable distributions.
WHAT TO READ NEXT
Put the Fund Structure in Context
ETF versus mutual fund is only one part of the decision. Understanding the broader investing process and the role of index funds can help you compare funds more clearly.
Investing for Beginners: How to Start Without Overcomplicating It
See how funds, accounts, risk, diversification, costs, and long-term planning fit into a broader beginner investing framework.
What Is an Index Fund? A Beginner’s Guide
Learn why an index fund is an investment strategy rather than a fund wrapper, and how that strategy can appear in either an ETF or a mutual fund.
SOURCES & METHODOLOGY
How We Verified This Answer
Verestly prioritizes primary regulatory and investor-education sources when verifying how ETFs and mutual funds trade, how they are priced, what they may cost, and how their structures can affect taxable distributions.
LAST REVIEWED
September 2026
This article is periodically reviewed for accuracy, source quality, clarity, and relevant changes to fund mechanics, costs, and investor guidance.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and useful financial tools.
View author profile →VERESTLY NEWSLETTER
Get Clearer Answers to Everyday Money Questions
Get beginner-friendly financial education, practical tools, and simple explanations designed to help you make more informed money decisions.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED ANSWERS
Keep Exploring
Continue with three closely related guides selected to deepen your understanding of investing fundamentals.