SAVING · FOCUSED ANSWER
Statement Balance vs. Current Balance vs. Minimum Payment
Your statement balance, current balance, and minimum payment represent different parts of your credit card bill. Understanding what each number means can help you know what is due, what you currently owe, and what happens when you make a payment.
IN PLAIN ENGLISH
The Short Answer
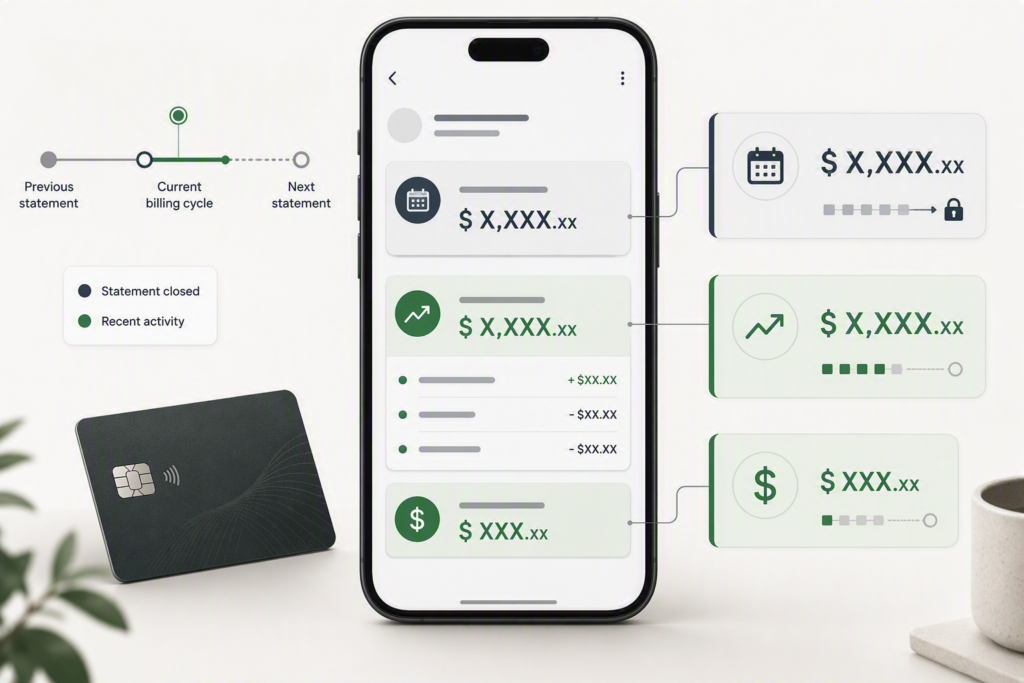
Your statement balance is what you owed when your last billing cycle closed. Your current balance is a more up-to-date view that can include activity after that closing date.
Your minimum payment is different: it is the smallest amount your card issuer requires you to pay by the due date. For many cards with a purchase grace period, paying the full statement balance by the due date is generally the amount that matters for paying that billing cycle in full.
SIMPLE COMPARISON
Last closed cycle · Account now · Minimum required
HOW IT WORKS
How These Three Credit Card Amounts Work
The easiest way to understand these numbers is to separate what happened when your billing cycle closed from what has happened since then.
STATEMENT BALANCE
Your Statement Balance Is Set When the Billing Cycle Closes
This amount reflects what you owed at the end of your most recent billing cycle. Activity that happens after the closing date generally belongs to the next cycle.
CURRENT BALANCE
Your Current Balance Keeps Changing
New purchases, payments, refunds, credits, fees, or other posted activity can change your current balance after the statement has already closed.
IMPORTANT DETAIL
The Minimum Payment Answers a Different Question
The minimum payment is the smallest amount your card issuer requires you to pay by the due date for that statement. It does not represent your total balance.
Paying only the minimum can leave most of the statement balance unpaid, and interest may apply to the remaining balance depending on your account terms.
KEY PRINCIPLE
Statement balance tells you what was owed when the cycle closed, current balance shows more recent account activity, and minimum payment tells you the least amount required by the due date.
SIMPLE EXAMPLE
How the Three Balances Can Appear on the Same Account
A simple timeline makes it easier to see why your statement balance, current balance, and minimum payment can all be different at the same time.
WHEN THE CYCLE CLOSES
Statement Balance
AFTER NEW ACTIVITY
Current Balance
PAYMENT DUE
The Minimum Payment Is Still a Separate Number
Even though the current balance has increased to $720, the statement may show a much smaller minimum payment due. That minimum does not mean the rest of the balance disappears.
WHAT THIS SHOWS
The $600 statement balance belongs to the completed billing cycle. The $720 current balance includes a newer $120 purchase. The $30 minimum payment is simply the smallest required payment for the statement and is not the same as paying the statement balance in full.
This is a simplified example. Actual balances, minimum-payment calculations, grace periods, and interest treatment depend on the terms of your account.
WHAT THIS MEANS FOR YOU
Which Credit Card Balance Should You Pay?
The amount that matters depends on what you are trying to do. The minimum payment keeps you from paying less than the required amount, while the statement balance is generally the key number when your goal is to pay that billing cycle in full.
MINIMUM REQUIRED
Pay at Least the Minimum by the Due Date
The minimum payment is the smallest amount your issuer requires for that statement. Paying less than the required amount by the due date can result in a missed or late payment.
PAY THE BILL IN FULL
The Statement Balance Is Usually the Key Number
If your card offers a grace period on purchases and its conditions are met, paying the full statement balance by the due date is generally what pays that completed billing cycle in full.
PAY NEWER ACTIVITY EARLY
Paying the Current Balance Can Go Beyond What Is Due
If the current balance is higher than the statement balance, the difference may come from newer purchases or other activity. Paying the full current balance can therefore pay some charges before they appear on the next statement.
IF YOU CANNOT PAY IN FULL
Paying More Than the Minimum Can Reduce What Remains
If you cannot pay the full statement balance, paying more than the minimum reduces the amount left outstanding. When interest applies, a smaller remaining balance may also reduce future interest compared with paying only the minimum.
QUICK DECISION GUIDE
Match the Amount to Your Goal
Use the minimum payment to identify the least required amount, the statement balance to understand the completed billing cycle, and the current balance to see a more recent account total.
PRACTICAL RULE
Do not assume the largest number on your account is automatically the amount currently due. Check the statement balance, minimum payment, due date, and your account terms before deciding how much to pay.
IMPORTANT EXCEPTIONS
When Paying the Statement Balance May Not Tell the Whole Story
Paying the full statement balance is a useful rule for many everyday purchase accounts, but some situations have different interest or payment rules. Your statement and cardholder agreement control what applies to your account.
CARRIED BALANCE
You Already Carried a Balance From a Previous Cycle
If you did not previously pay your statement balance in full, interest may already be applying. Depending on your account, your purchase grace period may also be affected.
CASH ADVANCES
Cash Advances Can Follow Different Interest Rules
Cash advances often do not receive the same grace-period treatment as ordinary purchases. Interest may begin accruing sooner, depending on your card terms.
PROMOTIONAL BALANCES
Promotional Financing May Create a Different Amount to Watch
Balance transfers, deferred-interest offers, or other promotional financing can have separate rates, expiration dates, or payment requirements that are not obvious from the current balance alone.
INSTALLMENT PLANS
Your Statement May Show a Special Payment Amount
Some issuers offer installment or payment-plan features that can create a separate amount due, such as an interest-saving balance or plan payment. Follow the labels on your actual statement.
BEFORE YOU PAY
Check the Payment Section of Your Statement
If your account includes special financing or a previously unpaid balance, do not rely only on the labels “statement balance” and “current balance.” Review the amount due, interest information, and any special payment notices.
KEY PRINCIPLE
The statement balance is a useful reference for a typical purchase account, but your actual interest and payment obligations always depend on the terms and activity of your specific card.
FREQUENTLY ASKED QUESTIONS
Common Questions About Credit Card Balances
These are some of the most common questions that come up when statement balance, current balance, and minimum payment all appear on the same account.
Why is my current balance higher than my statement balance? +
Your current balance can be higher if new purchases, fees, or other activity posted after the billing cycle closed. Those newer amounts generally were not part of the previous statement balance.
Why is my current balance lower than my statement balance? +
Payments, refunds, statement credits, or other account adjustments that posted after the statement closed can reduce the current balance without changing the previous statement balance.
Do I need to pay the current balance in full every month? +
Not necessarily. If your goal is to pay the completed billing cycle in full, the statement balance is generally the relevant amount. Paying the current balance can also cover newer activity that may not yet be due.
Is paying the minimum payment enough? +
Paying the minimum may satisfy the minimum payment requirement for that statement, but it does not usually mean the full balance has been paid. Any unpaid amount can remain outstanding, and interest may apply depending on your account terms.
Why does my statement balance still show after I made a payment? +
The statement balance is a record of what was owed when that billing cycle closed. A payment made afterward may reduce your current balance while the original statement balance remains visible for reference.
WHAT TO READ NEXT
Understand the Rest of Your Credit Card Statement
Once the three balance numbers make sense, the next step is understanding how the rest of your card statement fits together.
How to Read a Credit Card Statement
Learn how payment information, transactions, balances, dates, fees, and interest sections work together on a typical credit card statement.
How Credit Cards Work: A Beginner’s Guide
Review the broader mechanics of credit limits, purchases, billing cycles, payments, and borrowing costs.
QUICK REMINDER
Before making a payment, check your statement balance, current balance, minimum payment, due date, and any special payment or financing notices shown on your account.
SOURCES & METHODOLOGY
How We Verified This Answer
Verestly prioritizes primary government sources and authoritative consumer-finance references when verifying credit card billing, payment, grace-period, and statement information.
LAST REVIEWED
September 2026
This answer is periodically reviewed for clarity, accuracy, source quality, and relevant changes to consumer credit-card guidance.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and useful financial tools.
View author profile →VERESTLY NEWSLETTER
Get Clearer Answers to Everyday Money Questions
Get beginner-friendly financial education, practical tools, and simple explanations designed to help you make more informed money decisions.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED ANSWERS
Keep Exploring
Continue with three closely related guides selected to deepen your understanding of credit cards, statements, and responsible account management.