BANKING · ACCOUNT COMPARISON
Checking vs. Savings Accounts: What Is the Difference?
Learn how checking and savings accounts differ in everyday use, access, interest, fees, and money management—and how each account can serve a different role in your financial system.
QUICK ANSWER
The Short Answer
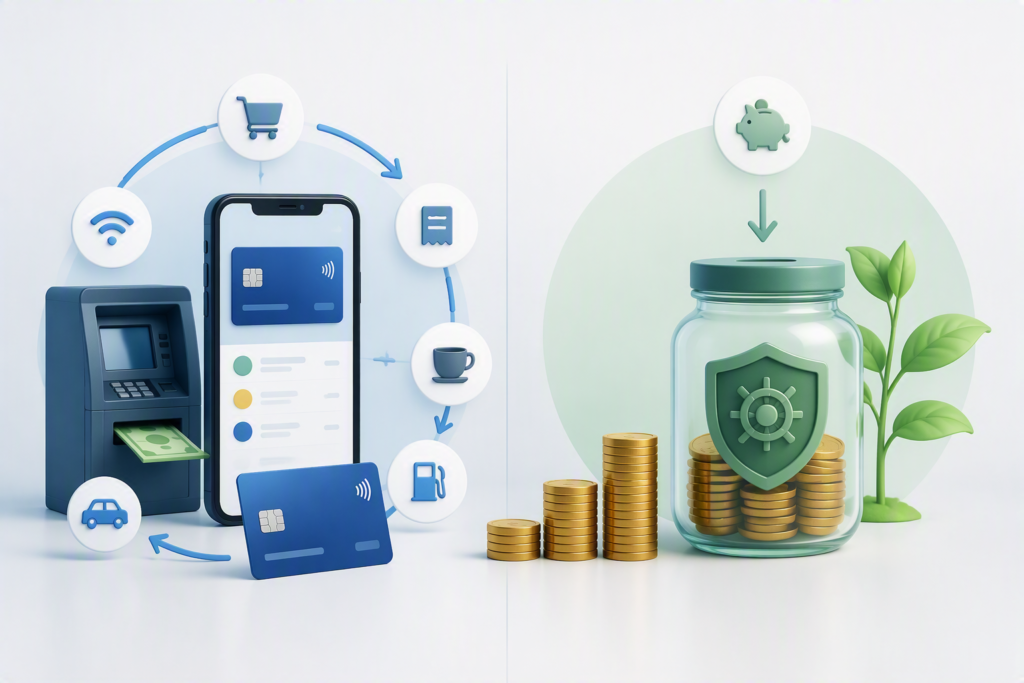
A checking account is generally designed for frequent transactions such as deposits, bills, purchases, and ATM withdrawals, while a savings account is generally designed to hold money separately from everyday spending and may earn interest. Many people use both because each account can serve a different cash-management purpose.
What You'll Learn
- ✓ How checking and savings accounts differ in purpose.
- ✓ How access, transactions, and withdrawals can differ.
- ✓ How interest, APY, fees, and minimum balances can affect each account.
- ✓ When using both checking and savings may make sense.
- ✓ What to compare before choosing an account setup.
HOW CHECKING WORKS
How Does a Checking Account Work?
A checking account is generally designed to handle money that moves frequently. It can act as the transaction hub for income, bills, purchases, cash withdrawals, and transfers, depending on the features offered by your bank or credit union.
Money comes into the account
Paychecks and other deposits can be added to checking through direct deposit, electronic transfers, mobile deposits, or other methods supported by the institution.
Everyday payments come out
Checking accounts are commonly used for recurring bills, debit-card purchases, checks when available, and other routine transactions.
You can access and move your money
Depending on the account, you may be able to withdraw cash at ATMs, transfer money to other accounts, send electronic payments, or use online and mobile banking.
Your available balance changes as money moves
Deposits, purchases, transfers, holds, and fees can all affect how much money is available to use. Your available balance may therefore differ from your current balance.
Checking-account features are not universal. Debit-card access, ATM networks, fees, minimum balances, interest, overdraft terms, and deposit availability can vary by bank, credit union, and account.
HOW SAVINGS WORKS
How Does a Savings Account Work?
A savings account is generally designed to hold money that you do not need for routine spending. It can help separate reserves from everyday cash flow while potentially earning interest, depending on the account and institution.
Money enters savings
Funds can be added through transfers, deposits, or other methods supported by the institution.
Money stays separate
Keeping savings apart from routine spending can make it easier to preserve money intended for later use.
Interest may accrue
Many savings accounts pay interest, although the APY, balance requirements, and rate structure vary by account.
Access remains available
You can generally move or withdraw savings, but the available methods, timing, limits, and fees depend on the institution and account terms.
Money moves when needed
Funds can be transferred back to checking or accessed through other methods supported by the account.
The main difference is the account's job
Checking accounts are commonly built around frequent money movement. Savings accounts are generally built around holding money apart from those everyday transactions.
That separation does not mean savings is inaccessible. Instead, the account gives money a different role while keeping it available under the institution's access and transfer rules.
CORE PRINCIPLE
A savings account is not simply a checking account with interest. Its practical value often comes from separating money you want to hold from money you expect to spend regularly.
COMPARE THE ACCOUNTS
The Core Differences Between Checking and Savings Accounts
Checking and savings accounts can both hold money, but they are usually designed for different jobs. The most useful comparison is not simply which account is better—it is how each account handles access, transactions, interest, and everyday use.
DIFFERENCE 1
Their Primary Purpose Is Different
Checking accounts are generally built for money that needs to move frequently. They are commonly used for deposits, recurring bills, purchases, cash withdrawals, and other everyday transactions.
Savings accounts are generally built for money you want to keep apart from routine spending while still keeping it accessible when needed.
KEY IDEA
Checking usually supports everyday money movement. Savings usually supports separation and holding.
DIFFERENCE 2
Checking Usually Offers More Transaction-Focused Access
Checking accounts commonly provide tools intended for frequent transactions, such as debit cards, bill payments, checks when supported, ATM withdrawals, and electronic transfers.
Savings accounts may also provide ATM or transfer access, but they are generally not intended to function as the primary account for repeated everyday purchases and payments.
- Checking is commonly used for bills and purchases.
- Savings is commonly used to hold money for later.
- ATM and debit-card features vary by institution and account.
- Transfer methods and availability can also differ.
DIFFERENCE 3
Savings Accounts Are More Commonly Built to Earn Interest
Many savings accounts pay interest and disclose an annual percentage yield, or APY. The rate can vary by institution, account type, balance level, and market conditions.
Checking accounts can also pay interest, so interest is not an absolute dividing line between the two account types. Some interest-bearing checking accounts may also include balance, transaction, or other requirements.
DIFFERENCE 4
Either Account Can Have Fees or Minimum Requirements
Neither checking nor savings should automatically be assumed to be free. Banks and credit unions may charge maintenance fees, require minimum balances, or apply other account-specific conditions.
Some institutions waive certain fees when qualifying requirements are met, but those requirements vary. Always review the current fee schedule and account disclosures before opening an account.
DIFFERENCE 5
The Available Banking Tools Can Differ
A checking account is more likely to be built around transaction tools such as a debit card, checks, bill pay, and frequent ATM access.
A savings account may offer some of the same access methods, but not necessarily all of them. The exact features depend on the bank or credit union and the specific account.
DIFFERENCE 6
The Account Label Does Not Tell You Everything
Two checking accounts can have very different fees, ATM networks, interest rates, overdraft policies, and minimum requirements. The same is true for savings accounts.
That is why comparing only the words “checking” and “savings” is not enough. The account disclosures determine how a specific product actually works.
BEFORE YOU CHOOSE
Compare purpose first, then review access, APY, fees, minimums, transfer rules, and other account terms.
VERESTLY FRAMEWORK
The Verestly Flow-and-Reserve Framework
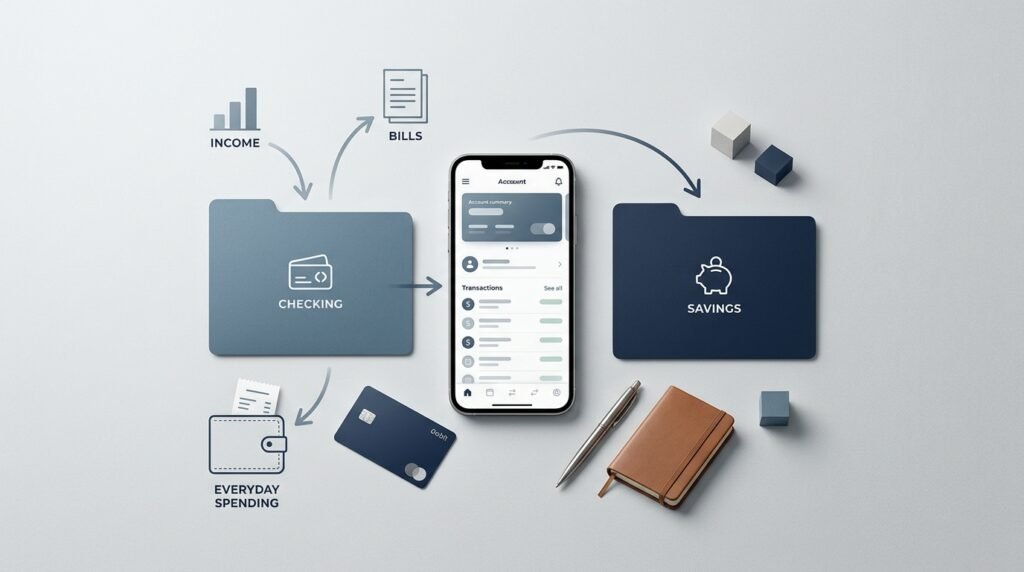
Checking and savings do not have to compete for the same job. One practical approach is to use checking for money that needs to move regularly and savings for money you want to keep separated from everyday spending.
Money Enters Checking
Income can enter your checking account through direct deposit, transfers, or other deposit methods supported by your bank or credit union.
Checking Handles Routine Activity
Bills, debit-card purchases, ATM withdrawals, and other frequent transactions can move through checking when those features are available.
Move Reserve Money to Savings
Money that does not need to remain in your everyday spending flow can be moved to savings, creating a clearer separation between current transactions and money held for later.
Savings Holds the Reserve
Savings keeps that money outside routine spending activity and may earn interest, depending on the account's APY, balance rules, and other terms.
Move Money Back When Needed
When reserve money is needed, it can generally be transferred or withdrawn using the methods available for that savings account, subject to the institution's timing and access rules.
THE CORE IDEA
In this Verestly educational framework, checking is the Flow account and savings is the Reserve account. The framework is not an official banking rule or a required setup—it is simply a way to give different portions of your cash different jobs.
REAL-LIFE EXAMPLE
What Checking and Savings Can Look Like in Practice
The difference between checking and savings becomes clearer when you see how money can move through both accounts. The example below shows one possible setup for everyday cash flow and short-term reserves.
STARTING POINT
Meet Maya
Maya receives $3,600 in take-home pay each month and uses one checking account for most of her day-to-day banking. She also wants to keep money for upcoming expenses separate from what she uses for bills and purchases.
Instead of asking one account to do every job, Maya uses checking for frequent money movement and savings for money she wants to hold apart from routine spending.
| Take-home pay deposited | $3,600 |
|---|---|
| Planned bills and routine spending | $2,850 |
| Amount kept in checking for near-term use | $450 |
| Amount transferred to savings | $300 |
| Checking role | Bills and transactions |
| Savings role | Money held for later |
APPLYING THE FRAMEWORK
How Maya Uses Both Accounts
RECEIVE
Income Arrives in Checking
Maya's paycheck is deposited into checking, giving her one central account for recurring payments and everyday transactions.
PAY
Routine Expenses Stay in Checking
Rent, utilities, groceries, and other planned transactions are paid from checking using the payment methods supported by the account.
SEPARATE
Reserve Money Moves to Savings
Maya transfers $300 to savings so that money intended for later is no longer sitting beside her everyday spending balance.
HOLD
Savings Keeps the Money Separate
The savings balance remains available for future use while staying outside Maya's normal transaction flow. Depending on the account, it may also earn interest.
ACCESS
Money Can Move Back When Needed
If Maya needs part of the savings balance, she can transfer or withdraw it using the methods available under her institution's account rules.
THE TAKEAWAY
Different Accounts Can Give Your Money Different Jobs
Maya is not using savings because checking is inadequate, or checking because savings is inaccessible. She is using each account for the role it is better suited to perform: checking for frequent transactions and savings for money she wants to keep separate from everyday spending.
This example is illustrative. Account features, transfer timing, fees, minimum balances, interest rates, and access methods vary by bank, credit union, and account.
MOVE AND ACCESS YOUR MONEY
How Transfers and Withdrawals Can Differ
Both checking and savings accounts can give you access to your money, but the available methods, transaction rules, and timing can differ. Before moving money, it helps to understand how your specific account handles each type of transaction.
BETWEEN YOUR OWN ACCOUNTS
Internal Transfers May Be the Simplest
If your checking and savings accounts are held at the same institution, you may be able to transfer money between them through online or mobile banking.
CHECK Availability and transfer timing →BETWEEN DIFFERENT INSTITUTIONS
External Transfers Can Take Longer
Moving money between different banks or credit unions may involve an ACH transfer or another supported transfer method. Processing time and funds availability can vary.
CHECK Transfer speed, holds, and possible fees ↗FOR CASH OR DIRECT ACCESS
Access Tools Depend on the Account
Checking accounts commonly provide debit-card and ATM access. Savings accounts may also provide ATM access or other withdrawal methods, but those features should not be assumed.
CHECK ATM access, card features, and withdrawal methods →FOR SAVINGS WITHDRAWALS
The Old Federal Six-Transfer Limit No Longer Applies
Federal Regulation D no longer requires savings accounts to be limited to six convenient transfers or withdrawals per month. However, a bank or credit union can still impose its own transaction limits or fees under the account agreement.
CHECK Your institution's current savings-account policy ↗BEFORE YOU MOVE MONEY
Check the Account Terms, Not Just the Account Type
Transfer timing, withdrawal methods, transaction limits, holds, ATM access, and fees can differ by institution and account. A checking or savings label alone does not tell you exactly how quickly or easily money can be accessed.
Review the current account agreement and fee schedule before relying on a transfer or withdrawal method.
COMPARE THE TERMS
Compare Fees, Minimums, and APY Before You Choose
The words “checking” and “savings” do not tell you whether an account is inexpensive, easy to use, or competitive. Review the actual account terms so you understand what the account may cost, what conditions apply, and whether it can earn interest.
- ✓ Check whether the account charges a monthly maintenance fee.
- ✓ Review minimum-balance or qualifying activity requirements.
- ✓ Compare APY and any conditions required to earn the stated rate.
Account terms vary by bank, credit union, and product. Always review the current disclosures and fee schedule.
BEFORE OPENING AN ACCOUNT
Which terms can change the real value of the account?
IMPORTANT DISTINCTION
A higher APY does not automatically make an account better if fees, balance requirements, limited access, or other conditions make the account a poor fit for how you plan to use it.
UNDERSTAND THE PROTECTION
Are Checking and Savings Accounts Federally Insured?
Eligible checking and savings deposits can both receive federal protection when they are held at the appropriate insured institution. The insurance system depends on whether you use a bank or a federally insured credit union.
START HERE
Institution typeIdentify Whether You Use a Bank or Credit Union
Banks and credit unions use different federal insurance systems. Checking and savings accounts at an FDIC-insured bank are covered through the FDIC, while qualifying accounts at a federally insured credit union are covered through the National Credit Union Share Insurance Fund.
- Bank → look for FDIC-insured status.
- Credit union → look for federal NCUA insurance.
- Do not assume every financial company is federally insured.
AT A BANK
FDICEligible Deposits at an FDIC-Insured Bank Can Be Covered
FDIC deposit insurance covers eligible deposit products, including checking and savings accounts, when they are held at an FDIC-insured bank.
- Checking deposits can qualify.
- Savings deposits can qualify.
- Coverage is automatic for eligible deposits at an insured bank.
COVERAGE LIMIT
Ownership mattersThe Standard FDIC Limit Is Not Simply Per Account
The standard FDIC insurance amount is $250,000 per depositor, per insured bank, for each account ownership category. Deposits held in the same ownership category at the same insured bank are generally combined when coverage is calculated.
- The limit is not automatically $250,000 for every separate account.
- Ownership categories affect how coverage is calculated.
- More complex ownership structures may require a separate coverage review.
AT A CREDIT UNION
NCUA / NCUSIFFederally Insured Credit Unions Use Share Insurance
At a federally insured credit union, qualifying share accounts are protected by the National Credit Union Share Insurance Fund, which is administered by the NCUA.
- Share draft accounts can receive coverage.
- Share savings accounts can receive coverage.
- The standard share insurance framework generally provides $250,000 per share owner, per insured credit union, for each ownership category.
VERIFY
Before relying on coverageConfirm the Institution and Your Coverage
Federal insurance depends on the institution, the type of deposit, ownership structure, and applicable coverage rules. If your balances are substantial or your accounts have multiple owners or beneficiaries, verify the coverage rather than assuming it.
- Confirm that the bank is FDIC insured.
- Confirm that the credit union is federally insured when relying on NCUA coverage.
- Review the applicable ownership category for larger or more complex balances.
IMPORTANT DISTINCTION
Checking Is Not More or Less Insured Simply Because It Is Checking
Eligible checking and savings deposits can both receive federal insurance. What determines coverage is the insured institution, ownership category, balance, and other applicable insurance rules—not whether the deposit account is labeled checking or savings.
CHOOSE YOUR SETUP CAREFULLY
Common Checking and Savings Account Mistakes to Avoid
Choosing between checking and savings is usually less about finding one universally better account and more about matching each account to the job your money needs it to perform. These common mistakes can make that comparison harder.
Using One Account for Every Purpose
Keeping bills, everyday spending, and money intended for later in the same transaction balance can make it harder to see what is actually available to spend.
Consider whether checking should handle frequent transactions while savings holds money you want separated from routine spending.
Choosing Based Only on APY
A higher advertised APY can be appealing, but it does not reveal the full cost or usability of an account. Fees, minimums, access, and qualifying requirements can also matter.
Compare APY together with fees, balance requirements, access methods, and account conditions.
Assuming All Savings Accounts Have the Same Withdrawal Rules
The former federal six-transfer limit is no longer required, but individual institutions can still apply their own transaction policies or fees.
Read the current savings-account agreement instead of relying on the old six-withdrawal rule.
Ignoring Fees and Minimum-Balance Requirements
A checking or savings account can carry maintenance fees, minimum-balance conditions, or other requirements that affect its practical cost.
Review the fee schedule and any waiver requirements before opening the account.
Assuming Every Account Has the Same Access Features
Debit cards, ATM access, checks, bill pay, external transfers, and other banking tools vary by institution and product.
Confirm the specific transaction and access features you expect to use before choosing the account.
Assuming Federal Insurance Works Per Individual Account
Federal deposit or share insurance is not calculated simply by giving every separate checking or savings account its own independent $250,000 limit.
Verify the institution and understand how ownership categories affect FDIC or NCUA coverage.
FREQUENTLY ASKED QUESTIONS
Checking vs. Savings Account FAQs
These short answers cover common questions about choosing, using, and organizing checking and savings accounts.
Do I need both a checking and a savings account?
Not necessarily. One account may be enough if it gives you the access and organization you need. Using both, however, can make it easier to separate money for frequent transactions from money you want to hold for later.
Which account should my paycheck go into?
Checking is often a practical destination for direct deposit because it is typically designed for bills, purchases, withdrawals, and other frequent transactions. Some people then transfer part of that money to savings.
Is a savings account safer than a checking account?
Not simply because it is a savings account. Eligible checking and savings deposits can both receive federal insurance at the appropriate insured institution and within applicable coverage rules. Savings can provide additional practical separation from everyday spending, but that is different from having stronger federal insurance.
Can a checking account earn interest?
Yes. Some checking accounts pay interest, although not all do. Interest-bearing checking accounts may also have balance, transaction, or other requirements, so compare the complete account terms rather than interest alone.
Are savings accounts still limited to six withdrawals per month?
No federal Regulation D rule currently requires the old six-per-month limit on convenient savings transfers or withdrawals. A bank or credit union can still maintain its own transaction limits or fees, so check the current account agreement.
Can I have checking and savings accounts at different banks?
Yes. You can generally maintain deposit accounts at different banks or credit unions. If you do, compare external transfer timing, access methods, fees, and federal insurance status so you understand how the accounts work together.
CONTINUE LEARNING
Where to Go Next
Now that you understand the difference between checking and savings, you can go deeper into the account type or banking feature that matters most for how you plan to manage your money.
EVERYDAY BANKING
Learn More About Checking Accounts
Go deeper if you want to understand how checking accounts handle deposits, debit-card purchases, ATM access, balances, fees, and other everyday transactions.
HOLD AND SEPARATE
Learn More About Savings Accounts
Continue here if you want to compare savings-account features, understand APY and access rules, or learn what to review before choosing an account.
COMPARE INSTITUTIONS
Compare Banks and Credit Unions More Carefully
Once you know which account type you need, compare institutions based on fees, minimums, access, ATM networks, digital features, deposit insurance, and the account terms that matter to you.
REDUCE BANKING FRICTION
Understand Fees and Overdrafts
If account costs or low-balance situations are a concern, continue with the dedicated banking guidance on account fees, overdraft policies, minimum balances, and other costs that can affect your everyday banking.
KEEP THE DECISION SIMPLE
Start With the Job Your Money Needs the Account to Perform
If money needs to move frequently, focus on checking features. If money needs to stay separated from everyday spending, focus on savings features. If you need both functions, compare a two-account setup and then evaluate the specific terms offered by your bank or credit union.
SOURCES & METHODOLOGY
How We Built This Guide
Verestly prioritizes primary government and regulatory sources when explaining banking rules and account mechanics. For this guide, we reviewed federal guidance covering checking and savings account features, transaction rules, deposit insurance, and credit-union share insurance.
LAST REVIEWED
September 2026
We reviewed this guide for banking accuracy, source quality, current savings-account transaction rules, and federal deposit and share-insurance information.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and actionable resources that help readers make more informed money decisions.
View author profile →VERESTLY NEWSLETTER
Build a Better Money System, One Step at a Time
Get practical guides, financial tools, and beginner-friendly resources designed to help you make clearer money decisions.
- Practical financial education
- New calculators and tools
- Actionable money systems
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Banking Guides
Continue with carefully selected guides about checking, savings, account features, and everyday banking.