RETIREMENT · FOCUSED ANSWER
What Does Vesting Mean in a 401(k)?
Vesting determines how much of certain employer contributions to your 401(k) you permanently own. Here is how vesting works, what is always yours, and why your vested balance can matter when you leave a job.
IN PLAIN ENGLISH
The Short Answer
Vesting determines how much of certain employer contributions in your 401(k) you permanently own. Your own contributions from your paycheck are always 100% vested.
Some employer contributions are immediately vested, while others become yours over time under your plan’s vesting schedule. That means the total balance shown in your account may be higher than the amount you are currently entitled to keep if you leave your job.
SIMPLE EXAMPLE
Employer contributions × vested percentage
HOW IT WORKS
How 401(k) Vesting Schedules Work
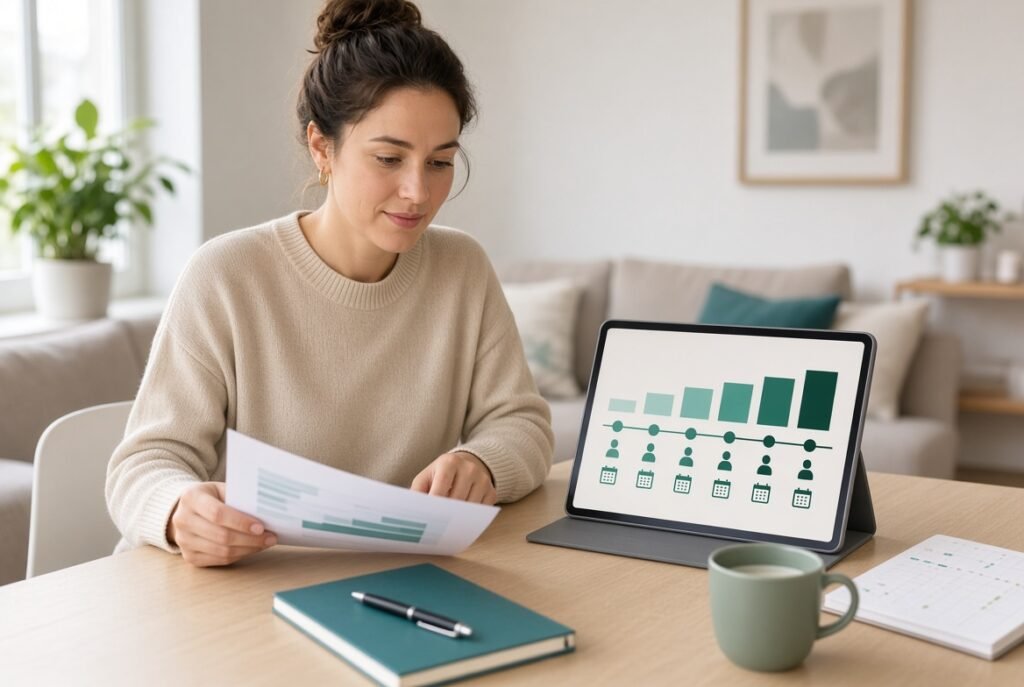
Employer contributions can become yours immediately or over time, depending on your plan and the type of contribution. When vesting happens over time, two common structures are cliff vesting and graded vesting.
CLIFF VESTING
Ownership Can Jump From 0% to 100%
With cliff vesting, affected employer contributions may remain unvested for a period and then become fully vested once you reach the required service milestone.
GRADED VESTING
Ownership Can Increase in Stages
With graded vesting, your vested percentage increases over multiple service milestones until the affected employer contributions become fully vested.
IMPORTANT DETAIL
Some Employer Contributions Are Immediately Vested
Not every employer contribution requires you to wait for ownership. Some plans provide immediate vesting, meaning the eligible employer contribution is 100% yours when it is made.
Different contribution types can also follow different vesting rules within the same plan, so your plan documents determine which schedule applies to each source of employer money.
KEY PRINCIPLE
Vesting schedules apply to eligible employer contributions. The money you contribute from your own paycheck is always 100% vested.
SIMPLE EXAMPLE
Account Balance vs. Vested Balance
Your 401(k) can show a total account balance that is larger than the amount you currently own if some employer contributions are still subject to vesting.
YOUR CONTRIBUTIONS
Employee Money
EMPLOYER CONTRIBUTIONS
Employer Money
VESTED BALANCE
Now Combine the Amounts You Own
The account shows $16,000 in this simplified example, but only $14,000 is currently vested because half of the employer contribution is still unvested.
WHAT THIS SHOWS
Your own $12,000 is fully vested. Of the $4,000 in employer contributions, only $2,000 is vested at 50%. That creates a $16,000 account balance but a $14,000 vested balance.
This is a simplified illustration. Actual vested balances can change with investment gains or losses, contribution sources, and the specific rules of your 401(k) plan.
WHAT THIS MEANS FOR YOU
What Vesting Can Mean When You Leave a Job
Leaving your employer does not cause you to lose the money you contributed to your 401(k). The part to review is any employer contribution that has not yet become fully vested under your plan.
CHECK YOUR VESTED BALANCE
Do Not Rely Only on the Total Account Balance
Your account may show both vested and unvested employer money. Before assuming the full balance is yours to keep, look for your vested balance or vested percentage in your plan records.
REVIEW THE NEXT MILESTONE
See Whether a Vesting Date Is Approaching
If your employer uses cliff or graded vesting, another service milestone may increase the percentage of employer contributions you own. Your plan documents should explain when those milestones are reached.
UNDERSTAND THE UNVESTED PORTION
Unvested Employer Money May Not Be Yours to Keep
If employment ends before certain employer contributions are fully vested, the unvested portion may eventually be forfeited under the terms of the plan. Your own contributions remain 100% vested.
KEEP IT IN PERSPECTIVE
Treat Vesting as One Factor in a Job Decision
Knowing how much employer money is vested can help you understand the financial effect of leaving, but vesting alone does not determine whether staying or changing jobs makes sense for you.
VESTING CHECK
Want to Map Your Vesting Milestones?
A vesting schedule tracker can help you organize your plan’s service milestones, vested percentages, and employer contribution amounts in one place.
PRACTICAL RULE
Before leaving an employer, compare your total 401(k) balance with your vested balance so you understand how much of the employer-funded portion you currently own.
COMMON MISUNDERSTANDINGS
What People Often Get Wrong About 401(k) Vesting
Vesting is straightforward once you separate your own contributions from employer contributions, but a few common assumptions can still create confusion.
MISUNDERSTANDING
“Vesting Applies to the Money I Contribute From My Paycheck”
Your own elective 401(k) contributions are always 100% vested. You do not need to wait to gain ownership of money you chose to defer from your paycheck.
BETTER WAY TO THINK ABOUT IT
Vesting generally matters when determining ownership of eligible employer contributions, not your own contributions.
MISUNDERSTANDING
“If the Money Appears in My 401(k), I Already Own All of It”
Your account can display employer contributions before those amounts are fully vested. The total account balance may therefore be higher than the amount you currently have a permanent right to keep.
BETTER WAY TO THINK ABOUT IT
Check both your total account balance and your vested balance when employer contributions are subject to a vesting schedule.
MISUNDERSTANDING
“Every 401(k) Uses the Same Vesting Schedule”
Plans can use different vesting structures and may vest employer contributions faster than the general federal minimum schedules. Some employer contributions may also be immediately vested.
BETTER WAY TO THINK ABOUT IT
Your plan documents determine the schedule and contribution rules that apply to your account.
MISUNDERSTANDING
“If I Leave Before I Am Fully Vested, I Lose My Entire 401(k)”
Leaving before full vesting does not erase your own contributions. The amount at risk is generally the unvested portion of employer contributions that remains subject to the plan’s rules.
BETTER WAY TO THINK ABOUT IT
Separate what is already 100% yours from any employer-funded amount that is still unvested.
REMEMBER
Your plan’s Summary Plan Description and account records are the best places to confirm which employer contributions are subject to vesting and what percentage is currently yours.
FREQUENTLY ASKED QUESTIONS
Common Questions About 401(k) Vesting
These are some of the most common questions beginners have after learning how vested and unvested employer contributions work.
Are my own 401(k) contributions always vested? +
Yes. Money you contribute to your 401(k) through elective salary deferrals is always 100% vested. Vesting generally affects eligible employer contributions instead.
Does every employer use the same vesting schedule? +
No. Plans can use different vesting structures, including immediate vesting, cliff vesting, and graded vesting. Your plan documents determine which schedule applies to each type of employer contribution.
What happens to unvested employer contributions if I leave? +
If you leave before certain employer contributions are fully vested, the unvested portion may eventually be forfeited under the rules of your plan. Your own contributions remain yours.
Where can I find my vesting schedule? +
Check your Summary Plan Description, 401(k) account portal, benefits materials, or information from your plan administrator. Look for terms such as vesting schedule, vested percentage, vesting service, or vested balance.
Can employer contributions be vested immediately? +
Yes. Some plans provide immediate vesting for employer contributions, while other employer contribution types may become vested over time. The specific treatment depends on your plan and the type of contribution.
WHAT TO READ NEXT
Understand the Bigger 401(k) Picture
Vesting makes more sense when you understand how employer contributions fit into the broader structure of a 401(k) plan.
How Does a 401(k) Work? A Beginner’s Guide
Learn how employee contributions, employer contributions, investment choices, and other core 401(k) mechanics fit together.
What Is a 401(k) Employer Match and How Does It Work?
See how employer matching contributions are calculated before vesting determines when those contributions become permanently yours.
WANT TO TRACK YOUR OWN MILESTONES?
Use the Vesting Schedule Tracker to organize your plan’s service milestones, vested percentages, and employer contribution amounts in one place.
SOURCES & METHODOLOGY
How We Verified This Answer
Verestly prioritizes primary government and regulatory sources when verifying retirement-plan rules, vesting requirements, and plan-participant protections.
LAST REVIEWED
September 2026
This answer is periodically reviewed for accuracy, source quality, clarity, and changes to retirement-plan rules that could affect 401(k) vesting.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and useful financial tools.
View author profile →VERESTLY NEWSLETTER
Get Clearer Answers to Everyday Money Questions
Get beginner-friendly financial education, practical tools, and simple explanations designed to help you make more informed money decisions.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED ANSWERS
Keep Exploring
Continue with three closely related retirement guides selected to deepen your understanding.