MONEY BASICS · PRACTICAL GUIDE
How to Make a Five-Year Financial Plan You Can Actually Follow
Learn how to turn your priorities into realistic financial goals, break them into manageable milestones, and build a flexible five-year plan that can adapt as your life changes.
QUICK ANSWER
The Short Answer
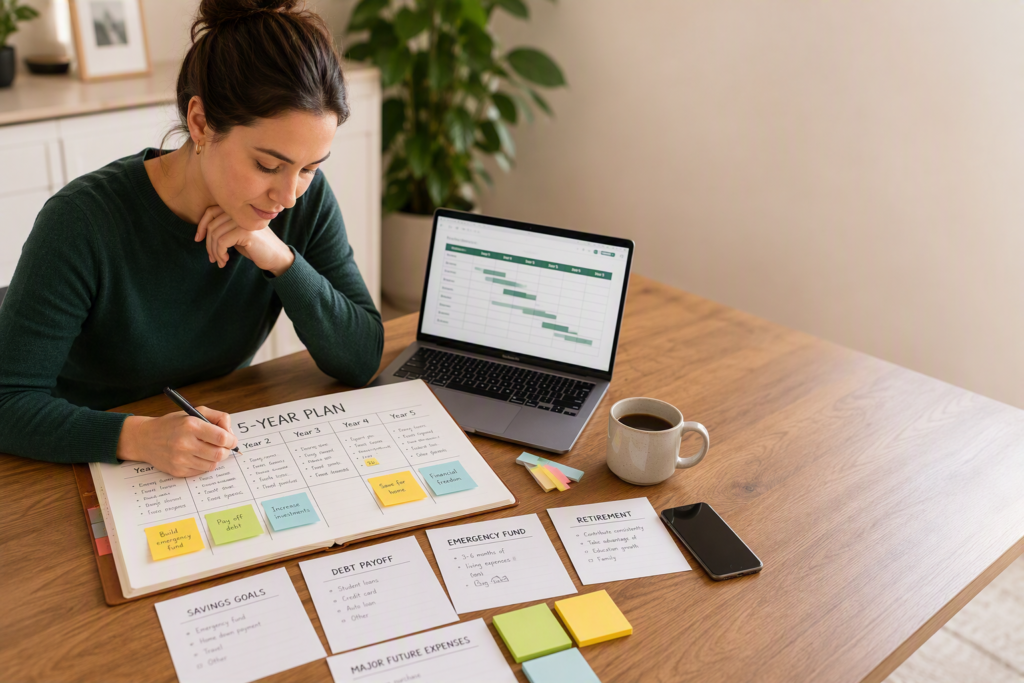
A five-year financial plan is a practical roadmap that connects where your finances stand today with the goals you want to work toward over the next several years. The goal is not to predict your future perfectly, but to create enough direction to make better decisions now and adjust the plan as your life changes.
What You'll Do
- ✓ Review where your finances stand today.
- ✓ Turn your priorities into specific financial goals.
- ✓ Break larger goals into realistic milestones.
- ✓ Review and adjust the plan when your circumstances change.
WHY THIS MATTERS
Why a Five-Year Plan Gives Your Financial Goals More Direction
Financial goals are easier to act on when you can see how today’s decisions connect to what you want your money to make possible several years from now.
Without a longer-term view, financial decisions can become disconnected. You may save for one goal, spend toward another, and take on new commitments without seeing how those choices compete for the same income and available cash flow.
A five-year plan creates a shared timeline for those priorities. It helps you identify which goals matter, which ones have real deadlines, and which ones can develop more gradually over time.
The plan also gives you a way to evaluate progress without expecting your life to unfold exactly as predicted. When income, expenses, responsibilities, or priorities change, you can update the roadmap while keeping sight of the larger direction.
RELATED FOUNDATION Money Basics: Build a Strong Financial Foundation →KEY IDEA
A five-year financial plan is not a prediction. It is a direction-setting roadmap that helps today’s decisions support the goals that matter to you.
STEP-BY-STEP METHOD
How to Build Your Five-Year Financial Plan
Start with your current financial reality, decide what you want the next several years to make possible, and work backward into goals and milestones you can realistically act on.
STEP 1
Build a Snapshot of Where You Are Today
Before planning several years ahead, get a clear picture of your current finances. You do not need perfect records, but you should understand the main numbers shaping your options today.
- Take-home income
- Regular and irregular expenses
- Current savings
- Outstanding debts
- Existing financial commitments
- Major expenses you already expect
PRACTICAL TIP
The goal is orientation, not accounting perfection. Use numbers that are accurate enough to show what your current financial capacity actually looks like.
STEP 2
Decide What You Want the Next Five Years to Make Possible
Think about the life changes, opportunities, and pressures that may matter to you over the next several years before turning everything into dollar targets.
- Changing careers
- Moving to a new city
- Buying a home
- Returning to school
- Starting or growing a family
- Creating more financial flexibility
STEP 3
Turn Your Priorities Into Specific Financial Goals
A broad intention such as “save more” is difficult to plan around. Give each important goal a purpose, an estimated amount, and a target date when possible.
These numbers are illustrative. Your own target should reflect the goal, timeline, costs, and circumstances that apply to you.
STEP 4
Decide Which Goals Need Attention First
If several goals are competing for the same money, avoid assuming they all need equal attention at the same time. Instead, compare what each goal is asking from your finances.
- Does this goal protect your current financial stability?
- Does it have a real deadline?
- Can it begin gradually instead of receiving full attention now?
- Would delaying it materially change the outcome?
IMPORTANT
This is an educational prioritization framework, not a universal financial sequence. Different households can reasonably put the same goals in a different order.
STEP 5
Break Large Goals Into Smaller Milestones
Five years is useful for setting direction, but it is too distant for many everyday decisions. Work backward from larger goals and identify what meaningful progress could look like during each year.
Milestones do not have to be equal. A goal may accelerate, pause, or change as your circumstances develop.
STEP 6
Check Whether the Plan Fits Your Current Cash Flow
Estimate what your selected goals would require during the next year and compare that with the money you realistically have available after your current obligations.
If the numbers do not fit, that is useful information. You may need to change a target, extend a deadline, reduce the number of goals being funded at once, or reconsider the goal.
- Can the next-year actions fit your current cash flow?
- Are several goals depending on the same available money?
- Would the plan create pressure on normal expenses?
- Does a target or timeline need to change?
REAL-LIFE EXAMPLE
What a Five-Year Financial Plan Can Look Like
A five-year plan becomes easier to follow when broad goals are translated into a sequence of priorities, milestones, and realistic adjustments over time.
EXAMPLE SCENARIO
Jordan Wants More Financial Flexibility Over the Next Five Years
Jordan has three priorities: strengthen financial stability, build a $10,000 career-transition fund, and begin preparing for a possible future home purchase. Rather than trying to fully fund all three goals at once, Jordan gives each one a different role across the five-year timeline.
| Year | Main Focus |
|---|---|
| Year 1 | Strengthen financial stability |
| Year 2 | Increase career-fund progress |
| Year 3 | Reach or reassess career goal |
| Year 4 | Redirect capacity to next priority |
| Year 5 | Reassess home goal and next horizon |
| Career-fund target | $10,000 |
| Built-in flexibility | Annual review |
WHAT THIS SHOWS
Jordan Does Not Try to Maximize Every Goal at the Same Time
The plan gives Jordan a sequence without turning that sequence into a permanent rule. Financial stability receives more attention first, while the career-transition goal develops alongside it.
After the career goal is reached or reassessed, some of that financial capacity can move toward the next priority. If the home goal no longer fits Jordan’s life, the roadmap can change.
GOAL BREAKDOWN
THE TAKEAWAY
A useful five-year plan gives your goals a sequence and a timeline without assuming that every year will unfold exactly as expected.
This example is illustrative, not a recommendation. Your goals, timeline, available cash flow, and financial priorities may be different.
ADAPT THE METHOD
What Changes If Your Situation Is Different?
The basic planning process can stay the same while the goals, pace, and order of priorities change. Your five-year plan should reflect your actual financial circumstances rather than force every situation into the same sequence.
UNSTABLE STARTING POINT
If Your Current Finances Still Feel Unstable
A five-year plan does not require you to ignore immediate financial pressure. Your first milestones may focus more on creating stability and reducing short-term strain before larger goals receive additional attention.
LIMITED CASH FLOW
If You Cannot Fund Every Goal at the Same Time
Reduce the number of goals receiving active funding, extend a deadline, or lower a target rather than forcing unrealistic contributions into the plan. A slower plan can still be a useful plan.
MAJOR LIFE CHANGE
If a Major Change Happens Before Year Five
A job change, move, relationship change, new child, health event, or other major shift can change what your money needs to accomplish. Revisit the roadmap rather than trying to preserve goals that no longer fit.
MORE FINANCIAL MARGIN
If Your Income or Available Margin Improves
More available money does not automatically mean every goal should accelerate. Revisit your priorities first, then decide whether the additional capacity belongs with an existing goal, a new goal, or greater financial flexibility.
NOT SURE WHAT TO CHANGE?
Start with the part of the plan that no longer matches your reality. You may need to change the goal, the amount, the timeline, or the order of priorities—not necessarily rebuild the entire five-year plan.
FREE VERESTLY TOOL
Prioritize the Goals Inside Your Five-Year Plan
When several goals are competing for the same money, the Financial Goal Prioritizer can help you compare them and identify which priorities may deserve attention first. Use the result as a starting point for your five-year roadmap, not as a permanent financial order.
- ✓ Compare multiple financial goals in one place.
- ✓ Clarify which goals may be more urgent or important right now.
- ✓ Build a practical starting order that you can reassess as circumstances change.
Free · Beginner-friendly · Built for competing financial priorities
FIVE-YEAR PLAN
Competing Goals
Illustrative preview · Not a personalized recommendation
NEED THE BIGGER PICTURE?
Review the Money Basics hub to connect financial stability, cash flow, goals, priorities, and other foundational concepts before adding more detail to your five-year plan.
TAKE ACTION
Your Five-Year Financial Planning Action Plan
You do not need to map every financial decision for the next five years today. Start by defining the direction, turn the most important goals into milestones, and build a review process that keeps the plan useful.
TODAY
20–30 minutes
Define Your Starting Point and Priorities
Write down where your finances stand today and identify the few life or money goals that matter most over the next several years.
- Review your take-home income, expenses, savings, and debts.
- List major changes or opportunities you may want to prepare for.
- Choose the goals that deserve a place in the five-year plan.
THIS WEEK
Build the roadmap
Turn Priorities Into Milestones
Give each major goal a reasonable target, timeline, and next milestone. Then compare those goals with the financial capacity you actually have available.
- Estimate the amount and target date for each major goal.
- Decide which goals need attention first.
- Break larger goals into annual or shorter milestones.
- Adjust goals that do not currently fit your cash flow.
ONGOING
Review and adjust
Review the Plan Without Constantly Rebuilding It
Use shorter check-ins to monitor progress and a broader review to decide whether your goals, amounts, timelines, or priorities still reflect your life.
- Check whether the actions supporting each active goal are happening.
- Review the broader roadmap periodically.
- Reassess after a major financial or life change.
- Update the plan when new information changes your priorities.
QUICK CHECK
A Useful Five-Year Plan Should Answer One Simple Question
Can you clearly explain what your most important financial goals are, what needs attention next, and when you will review the plan again?
COMMON MISTAKES
Mistakes That Can Make a Five-Year Plan Hard to Follow
A five-year plan becomes less useful when it is too rigid, too crowded, or disconnected from your actual financial capacity. These are some of the most common problems to avoid.
MISTAKE
Treating the Plan Like a Prediction
Income, expenses, relationships, opportunities, and priorities can all change over five years. A plan that only works if everything happens exactly as expected is too fragile.
BETTER APPROACH
Use the plan as a direction-setting roadmap and expect to update goals, amounts, or timelines as new information appears.
MISTAKE
Trying to Fund Too Many Goals at Once
A plan can look ambitious on paper while asking the same limited cash flow to support several major goals at the same time.
BETTER APPROACH
Decide which goals need active attention now and which can begin later or progress more gradually.
MISTAKE
Setting Goals Without Checking Cash Flow
A target can sound reasonable in isolation and still be difficult to support once normal expenses and existing obligations are taken into account.
BETTER APPROACH
Compare the next stage of each goal with your actual available cash flow before committing to the timeline.
MISTAKE
Assuming Every Goal Needs a Precise Number Today
Some future costs are still uncertain. Forcing false precision into a home, education, career, or family goal can make the plan look more certain than it really is.
BETTER APPROACH
Use a reasonable estimate for now, document the assumption, and update the target when better information becomes available.
MISTAKE
Never Revisiting the Original Plan
A plan written once and ignored for several years can become disconnected from your actual life. Even a well-designed roadmap eventually needs new information.
BETTER APPROACH
Use shorter progress check-ins, review the broader roadmap periodically, and reassess it when a major financial or life change occurs.
REMEMBER
A useful five-year financial plan is not the one that stays unchanged. It is the one that gives you enough structure to make better decisions and enough flexibility to respond when your circumstances change.
FREQUENTLY ASKED QUESTIONS
Common Questions About Five-Year Financial Planning
These questions cover the decisions that often come up when turning longer-term priorities into a financial plan you can actually maintain.
How many goals should be in a five-year financial plan? +
There is no universal number. A smaller group of meaningful goals is often easier to monitor than a long list competing for the same income and available cash flow.
The right number depends on how demanding each goal is, how much financial capacity you have, and whether some goals can wait or progress gradually.
Is a five-year financial plan the same as a budget? +
No. A budget focuses mainly on how income and expenses are managed over a shorter period. A five-year financial plan focuses on what you want your finances to make possible over several years.
Your budget can support the plan by providing the monthly actions that move your larger goals forward.
Review the Money Basics cash-flow foundation →What if I cannot afford all of my five-year goals? +
That is useful planning information. You may need to extend a deadline, lower a target, fund fewer goals at the same time, or reconsider whether a goal still belongs in the current plan.
The purpose of the plan is partly to reveal those trade-offs before they create financial strain.
Compare competing goals with the Financial Goal Prioritizer →Should a five-year financial plan include retirement? +
It can acknowledge retirement and other goals that extend beyond five years. The five-year plan can show what role those longer-term priorities play during the current planning window.
Detailed retirement projections, account choices, and contribution strategies belong in a dedicated retirement planning process.
Explore Retirement →Should investing be part of a five-year financial plan? +
The plan can identify goals that may eventually involve investing, but the appropriate way to hold money depends partly on when you expect to need it and how much risk is appropriate for that goal.
Investment selection, portfolio design, and risk management require their own analysis and should not be reduced to a single rule inside a general five-year plan.
Explore Investing →How often should I update my five-year financial plan? +
There is no required schedule. Shorter check-ins can help you monitor whether current actions are happening, while a broader periodic review can reassess goals, amounts, timelines, and priorities.
A major life or financial change is also a good reason to revisit the plan instead of waiting for the next scheduled review.
KEEP LEARNING
Continue With the Next Most Useful Resources
Use these resources to clarify priorities, strengthen your financial foundation, and connect your five-year plan to the money decisions you are making today.
Financial Goal Prioritizer
Compare competing financial goals and build a clearer starting order for where your available money may need to go first.
Use the free tool → BUILD STABILITYHow to Build a Strong Financial Foundation on an Average Income
Strengthen the financial base that supports goals extending beyond the next few months.
Read the guide → SEE THE BIGGER SYSTEMPersonal Finance for Beginners: 10 Simple Steps to Manage Your Money
See how spending, saving, debt, goals, financial protection, and longer-term planning fit together in one beginner roadmap.
Read the beginner guide →NEED THE BIGGER PICTURE?
Return to Money Basics to see how cash flow, financial stability, goals, priorities, net worth, and other foundational concepts connect before moving into more specialized financial topics.
SOURCES & METHODOLOGY
How We Verified This Guide
Verestly prioritizes primary government sources and regulators when verifying financial concepts. For this guide, we reviewed official guidance on financial well-being, goal setting, planning for life events, revising goals, and matching financial goals to appropriate time horizons.
LAST REVIEWED
September 2026
This guide was reviewed for accuracy, source quality, search-intent alignment, and consistency with Verestly's beginner-focused Money Basics framework.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on practical systems, clear explanations, and actionable financial tools.
View author profile →VERESTLY NEWSLETTER
Build Better Money Habits One Step at a Time
Join Verestly for beginner-friendly financial education, practical planning frameworks, new tools, and resources designed to help you make clearer money decisions.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED GUIDES
Continue Building Your Financial Plan
Explore additional Money Basics guides that can help you strengthen your financial foundation, clarify priorities, and understand the cash flow supporting your longer-term goals.