MONEY BASICS · FOCUSED ANSWER
Income, Expenses, and Cash Flow Explained in Plain English
Income is money coming in, expenses are costs that use your money, and cash flow shows how money moves in and out over time. Here is how the three work together and why timing matters.
IN PLAIN ENGLISH
The Short Answer
Income is money coming into your financial life. Expenses are costs that use some of that money. Cash flow describes how money moves in and out over time.
If more money comes in than goes out during a period, your net cash flow is positive. If more goes out than comes in, it is negative. But the total is only part of the picture: when income arrives and when expenses are due also matters.
SIMPLE FORMULA
Cash inflows − cash outflows = net cash flow
HOW IT WORKS
How Income and Expenses Create Cash Flow
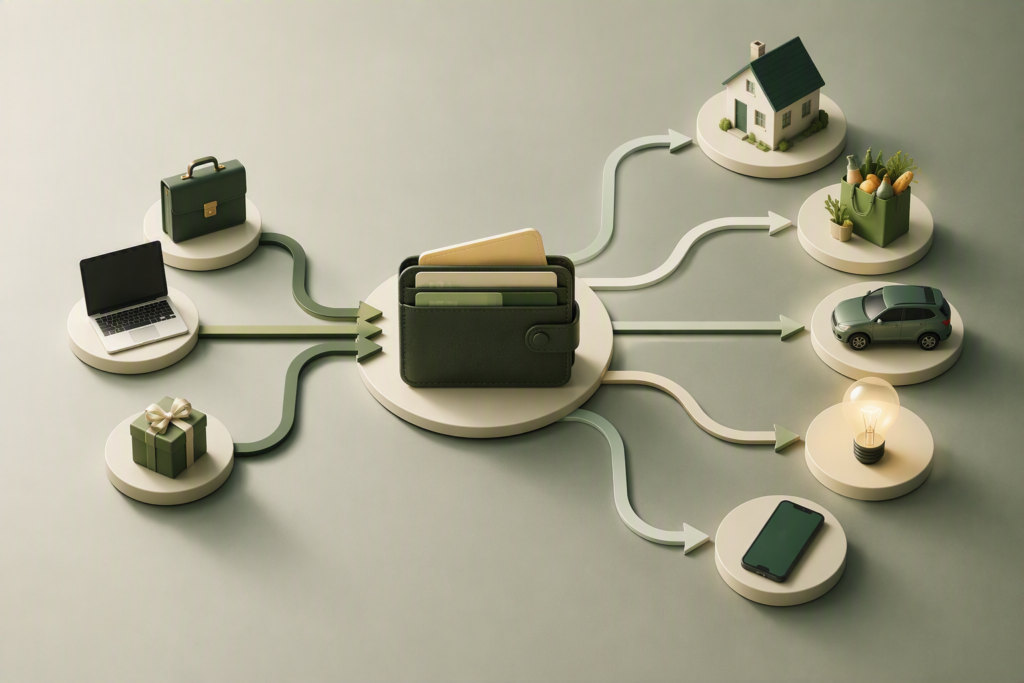
Cash flow starts with money coming in and money going out. Looking at both sides together shows whether you have more cash entering than leaving over a given period.
MONEY COMING IN
Income Creates Cash Inflows
Paychecks, freelance income, benefits, and other money you receive add cash to your financial picture. For everyday cash flow, take-home income is often the most useful amount to track because it reflects money that actually becomes available to you.
MONEY GOING OUT
Expenses Create Cash Outflows
Housing, food, transportation, utilities, insurance, and other spending reduce the cash available to you. Some costs happen every month, while others appear only occasionally.
PUTTING IT TOGETHER
Net Cash Flow Shows the Difference
Subtract total cash outflows from total cash inflows for the period you are reviewing. If the result is above zero, more money came in than went out. If it is below zero, more money went out than came in.
In this example, $4,000 of cash inflows minus $3,500 of cash outflows leaves a positive net cash flow of $500.
KEY PRINCIPLE
Cash flow is not just the final number. It also matters when income arrives and when cash outflows happen, because timing can affect how much money is actually available during the month.
SIMPLE EXAMPLE
What Cash Flow Looks Like in a Simple Month
A basic example makes it easier to see how income and expenses combine to produce a net cash flow result.
CASH INFLOWS
Money Coming In
CASH OUTFLOWS
Money Going Out
NET CASH FLOW
Now Compare What Came In With What Went Out
In this simplified month, $4,000 came in and $3,500 went out. The difference between those two amounts is the month's net cash flow.
WHAT THIS SHOWS
The example has positive net cash flow because cash inflows exceed cash outflows by $500. That does not tell you what the $500 should be used for—it simply describes what happened to the money during the period.
This is a simplified educational example, not a recommended spending pattern or financial target.
WHAT THIS MEANS FOR YOU
How to Look at Your Own Cash Flow
You do not need a complete budgeting system just to understand your cash flow. Start by identifying what comes in, what goes out, and when those movements happen.
MONEY COMING IN
Identify the Income That Actually Becomes Available
Start with money that reaches you, such as take-home pay, freelance income, benefits, or other regular sources. For everyday cash flow, the usable amount is usually more helpful than looking only at gross income.
INCOME TIMING
Notice When That Money Arrives
Income may arrive weekly, every two weeks, monthly, or on an irregular schedule. Knowing the timing helps explain whether cash is available when bills and other outflows need to be paid.
MONEY GOING OUT
Include More Than Just Your Regular Bills
Housing, food, transportation, utilities, insurance, and everyday spending all affect cash flow. Remember that some expenses happen only occasionally, so one typical month may not show the whole picture.
OUTFLOW TIMING
Pay Attention to When Money Leaves
Look at due dates, automatic payments, and periods when several expenses happen close together. Your monthly totals can look manageable while the timing still creates a temporary cash shortage.
QUICK CASH-FLOW CHECK
Compare the Two Sides Before Trying to Optimize Them
First ask whether more money is coming in than going out. Then ask whether the timing of those inflows and outflows creates difficult points during the month.
PRACTICAL RULE
Understanding your cash flow comes before choosing a budgeting method or deciding how to change your spending. First identify what is happening; then you can decide what needs attention.
COMMON MISUNDERSTANDINGS
What People Often Get Wrong About Cash Flow
Cash flow is a simple idea, but a few common assumptions can make your financial picture look better or worse than it really is.
MISUNDERSTANDING
“If My Income Is High, My Cash Flow Must Be Healthy”
Income tells you how much money comes in, but it does not show how much leaves. A higher income can still be paired with high expenses or other large cash outflows.
BETTER WAY TO THINK ABOUT IT
Look at income and cash outflows together. Cash flow depends on the relationship between the two, not income alone.
MISUNDERSTANDING
“If the Month Ends Positive, Timing Does Not Matter”
You can have positive net cash flow for the month and still run short before a paycheck arrives if several bills are due close together.
BETTER WAY TO THINK ABOUT IT
Review both the total amount of money moving and the timing of when cash comes in and goes out.
MISUNDERSTANDING
“Every Dollar Leaving My Checking Account Is an Expense”
Some cash outflows are transfers rather than spending. Moving money from checking to your own savings account reduces the cash available in checking, but the money still belongs to you.
BETTER WAY TO THINK ABOUT IT
Separate actual expenses from transfers when you want a clearer picture of where your money is going.
MISUNDERSTANDING
“One Typical Month Shows the Whole Picture”
Some expenses happen quarterly, annually, seasonally, or only occasionally. Looking at one unusually quiet month can make your cash flow appear stronger than it is over a longer period.
BETTER WAY TO THINK ABOUT IT
Include less-frequent costs when reviewing your overall financial pattern, even if they do not appear every month.
REMEMBER
Cash flow is most useful when you look at both amount and timing. The monthly total tells one part of the story; when money moves tells the other.
FREQUENTLY ASKED QUESTIONS
Common Questions About Income, Expenses, and Cash Flow
These questions help clarify the differences between money coming in, money going out, and the cash you actually have available during the month.
Is cash flow the same thing as income? +
No. Income is money coming in. Cash flow looks at both money coming in and money going out over time. Two people can have the same income but very different cash flow because their expenses and payment timing are different.
What is positive cash flow? +
Positive net cash flow means more cash came in than went out during the period you are reviewing. For example, $4,000 of inflows and $3,500 of outflows would produce positive net cash flow of $500.
Review the cash-flow example →What is negative cash flow? +
Negative net cash flow means more cash went out than came in during the period. One negative month does not explain the cause by itself, so it is useful to look at which outflows were regular, unusual, or less frequent.
Can I have positive monthly cash flow and still run short of money? +
Yes. Your total monthly inflows can exceed your total outflows while several bills are due before your next paycheck arrives. This is why cash-flow timing matters in addition to the final monthly total.
Is moving money to savings an expense? +
Not necessarily. Moving money from checking to your own savings account is a cash outflow from checking, but the money still belongs to you. That is different from an expense such as rent, groceries, or a utility bill.
WHAT TO LEARN NEXT
Turn What You See Into a Financial Plan
Understanding income, expenses, and cash flow gives you the foundation. The next step is learning how these pieces connect to a spending plan and to your broader financial life.
Learn How Budgeting Works
Budgeting takes the income and expense information you already understand and turns it into a plan for how money will be used.
Explore Personal Finance Basics
See how cash flow connects with saving, debt, banking, credit, investing, retirement, and other parts of your financial life.
WANT TO REVIEW YOUR OWN CASH FLOW?
Start with four questions: what comes in, when it arrives, what goes out, and when it leaves.
SOURCES & METHODOLOGY
How We Verified This Answer
Verestly prioritizes primary government sources and authoritative consumer-finance guidance when verifying foundational concepts such as income, expenses, cash flow, and the timing of money coming in and going out.
LAST REVIEWED
September 2026
This answer is periodically reviewed for clarity, accuracy, source quality, and relevant changes.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and useful financial tools.
View author profile →VERESTLY NEWSLETTER
Get Clearer Answers to Everyday Money Questions
Get beginner-friendly financial education, practical tools, and simple explanations designed to help you make more informed money decisions.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED ANSWERS
Keep Exploring
Continue with three closely related guides selected to deepen your understanding of everyday money management.