BUDGETING METHODS
Cash Stuffing and the Envelope Method: How They Work
Cash stuffing turns your spending plan into visible category limits. You assign money to envelopes for expenses such as groceries, dining, or personal spending, then use each envelope to see how much remains before making another purchase.
QUICK ANSWER
What is cash stuffing?
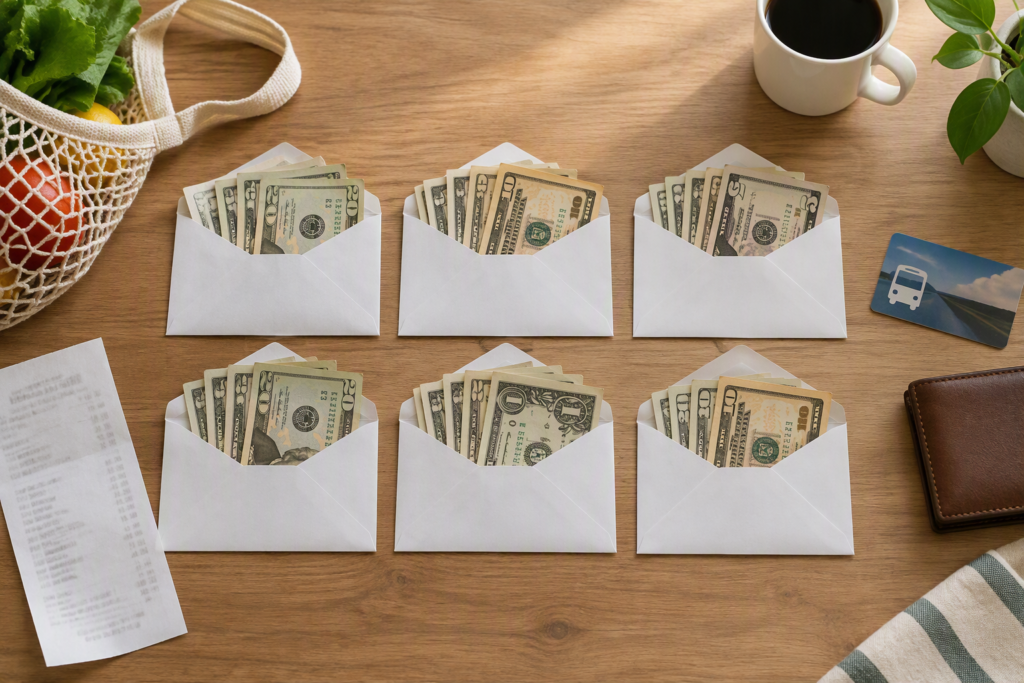
Cash stuffing is a physical version of the envelope budgeting method. You decide how much money is available for selected spending categories and separate those amounts into labeled envelopes. As you spend, the money remaining in each envelope shows how much of that category's original allocation is still available.
You do not have to use physical cash to apply the same principle. Digital categories, separate balances, or a hybrid system can create similar spending boundaries.
Envelope budgeting helps organize the money you have available. It cannot by itself solve a situation where essential expenses are greater than available income.
UNDERSTAND THE METHOD
Cash Stuffing and Envelope Budgeting Are the Same Core Idea
The envelope method gives selected spending categories a visible limit. Cash stuffing applies that idea with physical money, but the same system can also work digitally or through a hybrid setup.
With envelope budgeting, you decide how much of your available money will be assigned to specific categories before you spend it. Each category then receives its own envelope or tracked balance.
For example, you might create separate envelopes for groceries, dining out, entertainment, personal spending, or household purchases. When you spend from one of those categories, you reduce that category's remaining balance.
The purpose is not to make every purchase feel restrictive. It is to make the trade-off visible. Instead of asking, "Do I still have money in my account?" you ask, "How much is still available for this category?"
PHYSICAL
Cash Envelopes
Withdraw cash and divide it among labeled envelopes for selected spending categories.
DIGITAL
Digital Envelopes
Track category balances inside a budgeting app, spreadsheet, banking feature, or another digital system.
HYBRID
Mix Both Systems
Keep fixed expenses digital while using cash or separate balances for the categories where clearer spending boundaries are most useful.
The envelope is not the budget itself
Your broader budget determines how much money is available and what priorities need to be covered. The envelope method is simply one way to manage selected categories inside that budget.
You still need to account for income, bills, irregular expenses, savings priorities, and other obligations before deciding how much belongs in each envelope.
WHY THE BALANCE MATTERS
Each envelope turns an abstract budget number into a visible decision
Seeing $40 left in a dining envelope communicates something more useful than seeing a larger checking-account balance that also needs to cover rent, utilities, transportation, and other priorities.
The category balance does not make the decision for you. It gives you clearer information so you can decide whether to spend, pause, move money from another category, or adjust the plan.
Example only — your category amounts should reflect your own income, priorities, and expenses.
HOW IT WORKS
How the Envelope Method Works Step by Step
The method is simple: decide which categories need clearer boundaries, assign part of your available spending money to each one, track what you use, and adjust the plan when real life differs from what you expected.
START WITH YOUR BUDGET
Decide how much money is actually available
Before creating envelopes, account for the income you expect to have available and the obligations that need to be covered. Your envelope amounts should come from the money that remains available for the categories you want to manage.
The envelope system does not create additional money. It helps organize the money already available inside your broader spending plan.
CHOOSE CATEGORIES
Start with spending that is flexible enough to manage
Envelope budgeting is usually most useful for categories where the amount can change based on your decisions during the month.
You do not need an envelope for every expense. Fixed bills can remain in your normal payment system if that is simpler.
ASSIGN THE MONEY
Give each envelope a planned amount
Use your recent spending, priorities, upcoming needs, and available income to decide how much belongs in each category. These amounts should fit within your overall budget rather than being copied from someone else's percentages.
These numbers illustrate the process only. Your own amounts should reflect your household, income, priorities, and cost of living.
SPEND FROM THE CATEGORY
Reduce the envelope balance when you make a purchase
If you are using physical cash, spend directly from the appropriate envelope. If you use a digital system, record or categorize the purchase so the remaining balance stays accurate.
The goal is to keep each purchase connected to the category it affects.
CHECK WHAT REMAINS
Use the remaining balance as a decision signal
Suppose your dining envelope started with $150 and you have already spent $110. The remaining $40 tells you how much of the original dining allocation is still available.
That does not mean you are forbidden from changing the plan. It means any additional spending now requires an intentional decision.
MAKE THE TRADE-OFF VISIBLE
Decide what happens if an envelope runs low or reaches zero
If a category reaches its planned limit before the period ends, you have several reasonable options. The important part is recognizing the trade-off rather than spending without updating the plan.
Wait until the next budgeting period if the purchase can be delayed.
Reduce another category and transfer part of its allocation to the category that needs more.
If the original amount was unrealistic, use that information when building the next budget.
REVIEW AND RESET
Use the results to improve the next round
At the end of the budgeting period, compare your planned amounts with what actually happened. Some envelopes may have money left. Others may have needed more.
Those differences are useful information. They can help you refine your categories, adjust your limits, or simplify the system before the next month or paycheck.
Learn how to review your budget →THE CORE LOOP
Plan → Assign → Spend → Check → Adjust
Envelope budgeting works best as a feedback system. The goal is not to predict every expense perfectly. The goal is to make your spending decisions visible enough that you can respond deliberately when the plan and reality differ.
CHOOSE YOUR FORMAT
Physical Cash vs. Digital Envelopes
You do not have to carry cash to use the envelope method. The core idea is separating money by category and keeping each category's remaining balance visible enough to guide spending decisions.
PHYSICAL METHOD
Cash Envelopes
You withdraw cash and divide it among labeled envelopes for selected categories. Purchases are made directly from the appropriate envelope.
What it can make easier
- Seeing exactly how much remains in a category.
- Separating spending money from the rest of your account.
- Creating a physical pause before spending more.
What can be less convenient
- Online purchases may not fit naturally into the system.
- Carrying larger amounts of cash may be impractical.
- Receipts or manual notes may be needed for detailed tracking.
DIGITAL METHOD
Digital Envelopes
You keep the money in your accounts but track category balances through a budgeting app, spreadsheet, banking feature, or another digital system.
What it can make easier
- Paying bills and shopping online without handling cash.
- Keeping all spending in one digital workflow.
- Updating balances automatically or with fewer manual steps.
What requires more attention
- Your checking-account balance may look larger than what is actually available for a single category.
- Category balances must stay accurate for the system to be useful.
- It can be easier to ignore the limit if you stop checking it.
QUICK COMPARISON
The mechanism is the same — the experience is different
| Feature | Cash Envelopes | Digital Envelopes |
|---|---|---|
| Money location | Physical envelopes | Bank accounts or digital balances |
| Category visibility | Very tangible | Depends on the tool and how often you check it |
| Online spending | Less convenient | Usually easier |
| Updating balances | Physical balance changes immediately | May be automatic or require categorization |
| Best fit | People who prefer a tangible system | People who prefer digital payments and tracking |
A PRACTICAL MIDDLE GROUND
A hybrid system may be easier to maintain
Many households do not need to choose between fully physical and fully digital budgeting. You can keep recurring bills, subscriptions, and other fixed expenses in your normal digital payment system while using envelopes only for categories that benefit from clearer limits.
- Rent or mortgage
- Utilities
- Insurance
- Subscriptions
- Groceries
- Dining out
- Entertainment
- Personal spending
CHOOSE BASED ON FRICTION
Use the version you are most likely to keep using
The better system is not automatically the one with more rules. It is the one that makes category limits clear without creating so much maintenance that you stop using it.
Do you prefer seeing and handling the money physically?
Do most of your purchases happen online or by card?
Which categories actually need stronger spending boundaries?
How much manual tracking are you realistically willing to maintain?
SEE IT IN PRACTICE
Example: How an Envelope Budget Can Look in a Real Month
The amounts below are only an illustration. The useful part is the structure: decide what needs to be covered first, identify flexible categories, assign realistic amounts, and then track what remains.
EXAMPLE HOUSEHOLD
$4,200 of monthly take-home income
Imagine a household with approximately $4,200 in take-home income for the month. Before creating envelopes, it accounts for fixed bills, essential obligations, planned savings, and other priorities.
After those commitments are included in the broader budget, the household decides to use envelopes for several flexible spending categories that tend to vary throughout the month.
EXAMPLE ALLOCATION
Divide the $800 across categories that need clearer limits
| Envelope | Planned | Why it is included |
|---|---|---|
| Groceries | $400 | Frequent purchases where spending can vary from week to week. |
| Dining out | $150 | Discretionary spending that can be adjusted when needed. |
| Personal spending | $100 | Creates a defined amount for individual purchases. |
| Entertainment | $75 | Keeps optional leisure spending visible. |
| Household | $75 | Covers smaller variable household purchases. |
| Total envelopes | $800 | Matches the amount available for these categories. |
MID-MONTH CHECK
Now the balances start informing decisions
Suppose the household checks the envelopes halfway through the month. Some categories are still comfortably within plan, while others are being used faster than expected.
Groceries
$230 leftDining out
$40 leftPersonal spending
$65 leftTHE DECISION POINT
The dining envelope is almost used up. What happens next?
The $40 balance does not automatically mean something went wrong. It simply shows that most of the original dining allocation has already been used.
Keep the remaining $40
Reduce dining purchases for the rest of the month and stay within the original allocation.
Move money from another envelope
If dining matters more this month, intentionally reduce a different flexible category and move part of that money.
Adjust next month's amount
If the $150 limit repeatedly proves unrealistic, revisit the allocation rather than treating the same shortfall as a surprise.
EXAMPLE TRADE-OFF
Moving money changes priorities — it does not create new money
Suppose the household wants another $30 for dining. It could move $30 from the entertainment envelope.
Dining would gain flexibility, but entertainment would now have $30 less available. That is the trade-off the envelope system makes visible.
IMPORTANT CONTEXT
Your numbers may look completely different
A household with higher housing costs, children, medical expenses, irregular income, transportation needs, or different priorities may have much less — or much more — available for these categories. Envelope budgeting helps allocate available income; it does not set a universal standard for what each category should receive.
Learn how to choose budget categories →KNOW THE TRADE-OFFS
Where Envelope Budgeting Can Help — and Where It Can Be Awkward
Envelope budgeting can make flexible spending easier to see and manage, but that does not mean every expense or every household needs to use it. The method works best when it solves a specific budgeting problem without adding more maintenance than it is worth.
MAY BE A GOOD FIT
When clearer category boundaries would help
Flexible spending keeps running over plan
Categories such as groceries, dining, entertainment, and personal spending can benefit from a visible remaining balance.
Your bank balance is giving you the wrong signal
A checking account may show plenty of money even though much of it is already needed for bills or other priorities. Envelopes separate what is available by purpose.
You prefer visible or tangible limits
Some people find it easier to make spending decisions when the category balance is obvious before the purchase happens.
You want a simple way to practice trade-offs
Moving money between categories makes the cost of changing priorities more explicit instead of letting the total account balance absorb the difference.
MAY BE LESS NATURAL
When another budgeting structure may be simpler
Most of your expenses are fixed or automated
Rent, insurance, loan payments, subscriptions, and other recurring bills may not benefit much from being turned into physical envelopes.
You rely heavily on online or card payments
A cash-only system may create unnecessary friction when most purchases happen digitally. A digital or hybrid envelope system may fit better.
Tracking every category would become too complicated
Too many envelopes can turn a simple method into a maintenance problem. It is reasonable to use the system only for a few categories that need attention.
The main problem is not spending control
If essential expenses already exceed available income, dividing money into envelopes does not close that gap. The underlying cash-flow problem still needs to be addressed.
KEEP EXPECTATIONS REALISTIC
What the envelope method can — and cannot — do
- See how much remains in selected spending categories.
- Notice when one category is using money faster than planned.
- Make transfers between categories more intentional.
- Learn from real spending and refine future allocations.
- Guarantee that every planned amount will be realistic.
- Remove unexpected expenses from your life.
- Make insufficient income cover expenses that exceed it.
- Replace the need to review and adjust your broader budget.
THREE COMMON SCENARIOS
The same method can be used very differently
Envelope budgeting does not require every household to use the same categories, format, or number of envelopes.
One problem category
Someone who regularly spends more than intended on dining may use a single dining envelope while leaving the rest of the budget unchanged.
Several flexible categories
A household may use envelopes for groceries, household purchases, personal spending, entertainment, and dining while keeping bills automated.
Most discretionary spending
Someone who strongly prefers cash may use physical envelopes for most day-to-day discretionary categories while leaving fixed obligations in the bank.
IF YOUR INCOME CHANGES
Irregular income changes how much you can safely stuff
When income changes from month to month, the envelope method still can be used, but the amounts should be based on money actually available or on a conservative planning amount rather than assuming every month will look the same.
In that situation, the income-planning process comes first. The envelopes come after you know how much is available to assign.
Learn how to budget with irregular income →BOTTOM LINE
Use envelopes where they improve decisions — not everywhere by default
A small, focused envelope system can be just as valid as a full cash-stuffing setup. Start with the categories where a clearer boundary would actually help, then expand only if the additional structure makes your budget easier to manage.
SET BETTER LIMITS
How to Set Realistic Envelope Limits
The goal is not to pick the lowest number possible. A useful envelope limit should reflect what you can afford, what the category usually costs, and what trade-offs you are willing to make.
A SIMPLE FRAMEWORK
Use four inputs before choosing an amount
Instead of copying someone else's cash-stuffing numbers, build each envelope from your own financial reality.
What you have available
Start with the money remaining after higher-priority obligations are accounted for. The total of all envelopes needs to fit inside that amount.
What you actually spend
Review recent transactions or receipts so your starting amount is based on real behavior rather than a guess.
What needs to change
Decide whether the category needs to stay roughly the same, increase, or decrease based on your priorities and available income.
What is realistically maintainable
A target that is technically possible but consistently unrealistic may create repeated transfers and frustration instead of useful guidance.
START WITH EVIDENCE
Use recent spending as a baseline, not a rule
Suppose you spent an average of about $475 per month on groceries over the last three months. Setting the first grocery envelope at $250 simply because that number looks better on paper may not be realistic.
A more useful question is whether your recent spending reflects necessary costs, avoidable purchases, unusual events, or a mix of all three.
EXAMPLE REVIEW
ADJUST WITH INTENTION
Reduce a category by changing the plan behind the number
A lower envelope amount works only if the underlying spending can actually change. The number itself does not create the savings.
“I will cut groceries from $475 to $300.”
The target changes, but there is no explanation of what behavior or purchasing pattern will make the lower amount possible.
“I will test $425 and change how I shop.”
The lower target is connected to a specific adjustment, such as planning meals, reducing convenience purchases, or shifting spending from another category.
CATEGORY MATTERS
Not every envelope should be treated the same way
Some expenses are highly flexible. Others have a practical minimum that may be difficult to reduce without affecting essential needs.
Dining and entertainment
These categories may allow larger adjustments because individual purchases can often be delayed, reduced, or skipped.
Groceries and household spending
There may be room to adjust how money is spent, but the category still needs to cover real household needs.
Transportation or essential care
Costs may vary, but some spending may be difficult to reduce because it supports work, caregiving, healthcare, or other essential responsibilities.
TEST, THEN REFINE
Your first envelope amount does not have to be perfect
Think of the first month as a test. Set a reasonable amount, use the system, and compare the result with what actually happened.
If the same envelope repeatedly runs out despite reasonable spending, the limit may be too low. If a large amount is left every month, you may have room to reallocate part of that money.
Use recent spending and available income.
Use the amount through a full budgeting period.
Compare the plan with actual spending.
Change the amount when the evidence supports it.
WATCH FOR THESE SIGNALS
Your envelope limits may need another look if...
You transfer money into the same envelope almost every period.
Essential purchases regularly exceed the amount you assigned.
Large balances remain unused in other categories month after month.
The system requires so many adjustments that you stop trusting the limits.
GO DEEPER
Need help deciding what each category can reasonably receive?
Category amounts should work together inside the full budget, not be chosen in isolation.
TAKE ACTION
How to Start Your First Envelope Budget
You do not need dozens of envelopes or a perfect system on day one. Start with a few categories that would benefit from clearer spending boundaries, test the method for one budgeting period, and refine it using what actually happens.
CHECK YOUR PLAN
Confirm how much money is available
Start with your broader budget. Account for income, bills, required expenses, and other priorities before deciding how much can be assigned to envelope categories.
PICK A FEW CATEGORIES
Choose two to five categories to test
Focus on areas where spending varies or where you regularly wonder how much is still safe to spend. You can add more envelopes later if the system proves useful.
CHOOSE THE FORMAT
Decide between cash, digital, or hybrid
Use physical cash if tangible balances help you. Use digital categories if most purchases happen by card or online. Combine both if that makes the system easier to maintain.
SET STARTING AMOUNTS
Base the first limits on real spending
Review recent transactions and choose reasonable starting amounts that fit inside the money available. Treat those numbers as a test, not permanent rules.
USE THE BALANCES
Check the envelope before making decisions
When you spend, reduce the appropriate balance. Before another purchase, look at what remains so the category — rather than the total bank balance — informs the decision.
REVIEW THE RESULT
Adjust the system after a full budgeting period
Notice which categories ran low, which had money left, and which envelopes did not add enough value to justify the extra tracking. Keep what worked and simplify what did not.
A SIMPLE FIRST SETUP
You can start with only three envelopes
For example, someone who wants more visibility around variable spending could begin with groceries, dining, and personal spending while leaving every other part of the budget unchanged.
Frequent essential spending that can vary during the month.
Flexible spending where a visible limit may be useful.
A defined amount for discretionary individual purchases.
IF YOU USE PHYSICAL CASH
Keep the process simple and practical
Label each envelope clearly so purchases are easy to categorize.
Withdraw only the amount you intentionally assigned to cash categories.
Keep receipts or notes if you want more detail than the remaining cash shows.
Avoid carrying more cash than you are comfortable keeping with you.
IF YOU USE DIGITAL ENVELOPES
Make the category balance easy to check
Create clear categories that match the way you actually spend.
Record or categorize purchases soon enough that balances remain useful.
Check the category balance before relying on the total account balance.
Keep the system simple enough that updating it does not become a burden.
YOU DO NOT HAVE TO FUND EVERYTHING AT ONCE
Envelopes can be funded by paycheck
If your income arrives throughout the month, you can assign part of each paycheck to the envelopes needed before the next payday instead of fully funding every monthly category at the beginning of the month.
The important point is to coordinate the envelope amounts with your cash-flow timing so money is available when expenses occur.
Learn how paycheck budgeting works →TRY A ONE-MONTH TEST
Judge the method by whether it improves your decisions
At the end of the first budgeting period, do not ask only whether every envelope stayed under its original limit. Ask whether the system gave you better information and made trade-offs easier to see.
Did you check category balances before spending?
Were the starting limits reasonably realistic?
Did any envelope require repeated transfers?
Was the system simple enough to maintain?
YOUR NEXT MOVE
Start smaller than you think you need to
Choose a few categories, set reasonable starting amounts, and run the system through one complete budgeting period. You can always add more structure later.
COMMON MISTAKES
Common Envelope Budgeting Mistakes — and How to Adjust
Most problems with cash stuffing come from the way the system is set up or maintained, not from failing to follow it perfectly. When something repeatedly does not work, treat that as information and adjust the structure.
TOO MANY ENVELOPES
Creating a category for every small expense
A system with dozens of envelopes can become harder to maintain than the spending problem it was supposed to solve. Small purchases may require constant categorization, transfers, and balance updates.
Start with a few broad categories where clearer boundaries would actually improve your decisions. Add detail only when it provides useful information.
UNREALISTIC LIMITS
Setting amounts based on what you wish you spent
A low target may look disciplined on paper, but if it does not reflect actual costs or realistic behavior changes, the envelope may run out repeatedly.
Use recent spending as a starting point, then make deliberate changes in manageable steps. A useful limit should guide behavior without ignoring the real cost of the category.
TREATING TRANSFERS AS FAILURE
Assuming that moving money means the budget failed
Real spending rarely matches a plan exactly. Moving money from one flexible category to another can be a reasonable response when priorities change.
Make the transfer intentionally and acknowledge the trade-off. If dining receives another $30, another category has $30 less. The goal is awareness, not rigid perfection.
IGNORING DIGITAL PURCHASES
Spending by card without updating the envelope
A physical envelope stops being accurate when purchases from the same category happen digitally but are not reflected in its balance.
Record card and online purchases against the corresponding category, or use a hybrid system that keeps digitally paid categories digital from the beginning.
USING THE BANK BALANCE INSTEAD
Checking the account balance and forgetting the category balance
Your checking account may contain money that is already assigned to rent, bills, groceries, and other priorities. Looking only at the total balance can make more money appear spendable than the category actually has available.
Check the envelope or category balance before making the purchase. The category tells you what remains for that purpose; the account balance tells you only how much money is physically in the account.
NEVER REVIEWING THE SYSTEM
Reusing the same limits when the evidence says they do not fit
If the same category runs out early every month or another consistently has a large balance left, repeating the original allocation may not be useful.
Review the results at the end of each budgeting period and change category amounts when your spending, priorities, or costs have changed.
EXPECTING ENVELOPES TO FIX A CASH-FLOW GAP
Trying to solve insufficient income with smaller categories
If essential expenses exceed available income, reducing every envelope does not necessarily solve the underlying problem. Some costs may already be near their practical minimum.
Use the envelope system to clarify where available money is going, but evaluate the larger cash-flow picture separately. The method can organize limited resources; it cannot create resources that are not there.
QUICK DIAGNOSTIC
If the system keeps breaking, identify what is actually happening
Different problems require different adjustments. Use the pattern you are seeing to decide what to change next.
Recheck the category amount and the spending behavior behind it.
Revisit the broader allocation and confirm whether total spending targets fit available income.
Simplify the categories or switch to a digital or hybrid system with less manual work.
Check whether the original limits are too rigid or whether several categories should be combined.
WHEN YOU OVESPEND
Reset the plan instead of abandoning it
Going over one envelope does not require starting the entire budget over. Update the numbers, decide how the extra spending will be absorbed, and keep tracking the rest of the period.
Determine how much the category exceeded its allocation.
Reduce another category, use available margin, or revise upcoming spending.
Make the revised category balances reflect the decision.
Continue tracking instead of treating one overage as the end of the budget.
IF OVESPENDING KEEPS HAPPENING
The issue may be bigger than the envelope system
Repeated overspending can point to unrealistic category limits, missing expenses, cash-flow timing problems, or a budget that needs broader adjustment.
FREQUENTLY ASKED QUESTIONS
Common Questions About Cash Stuffing and Envelope Budgeting
The envelope method is flexible by design. These answers clarify how to handle cash, digital purchases, leftover money, overspending, and category changes without turning the system into a rigid set of rules.
Is cash stuffing the same as the envelope method?
Cash stuffing is the physical-cash version of envelope budgeting. The broader envelope method simply assigns money to specific categories and tracks each category separately. You can apply that idea with cash, digital balances, or a combination of both.
Do I have to use cash for every expense?
No. Many people keep rent, utilities, insurance, subscriptions, and other recurring bills digital while using envelopes only for selected variable categories such as groceries, dining, entertainment, or personal spending.
What happens when an envelope runs out of money?
Reaching zero means the original allocation has been used. You can pause additional spending, intentionally move money from another flexible category, or revise the plan if the amount was unrealistic. The important part is recognizing the trade-off.
What should I do with money left in an envelope?
There is no single required approach. You might leave the money in the category for the next budgeting period, reallocate it to another priority, or use the result as evidence that the category limit could be adjusted.
The right choice depends on your broader budget and what that money needs to accomplish next.
How many cash envelopes should a beginner use?
There is no universal number. A beginner can start with only two to five categories where clearer limits would be useful. A smaller system is often easier to test and maintain than creating an envelope for every expense immediately.
Can I use the envelope method with credit or debit cards?
Yes. The important part is updating the appropriate category balance when a purchase happens. A digital envelope system can work with card spending as long as the category balances remain accurate enough to guide future decisions.
Does cash stuffing work with irregular income?
It can, but income planning comes first. When income changes from month to month, fund envelopes from money that is actually available or from a conservative planning amount rather than assuming every month will be the same.
Learn how irregular-income budgeting works →Is envelope budgeting supposed to stop overspending completely?
No budgeting method can guarantee that. Envelope budgeting makes category limits and trade-offs more visible, which may help you notice overspending earlier. You still need to review what happened and adjust when the plan does not match reality.
QUICK TAKEAWAY
The envelope method is a boundary system, not a punishment system
Its purpose is to show how much of a category's planned money remains and make trade-offs easier to see. The system can be adjusted when income, expenses, priorities, or real-life needs change.
RELATED LEARNING
Keep Building Your Budgeting System
These guides cover the next questions that usually come up after you understand how envelope budgeting works.
BUDGET CATEGORIES
Best Budget Categories for a Simple Monthly Spending Plan
Learn how to organize expenses into useful categories without making your budget unnecessarily complicated.
Explore Budget Categories →MONTH-END REVIEW
How to Review Your Budget at the End of the Month
Compare your plan with actual spending and use the results to improve next month's allocations.
Review Your Budget →BUDGET TROUBLESHOOTING
Why Your Budget Keeps Failing—and How to Fix It
Identify whether repeated budget problems come from unrealistic limits, missing expenses, timing, or a system that needs to be simplified.
Fix Your Budget →SOURCES & METHODOLOGY
How We Built This Guide
This guide combines official consumer-finance guidance with educational material on budgeting, spending tracking, cash-flow planning, and the envelope method. Examples are illustrative and are not intended as universal spending targets.
Consumer.gov
Making a Budget
Supports the article's explanation of budgeting as a monthly planning process that includes income, expenses, spending tracking, and end-of-month review.
View source ↗Consumer Financial Protection Bureau
Track Your Spending With This Easy Tool
Supports the use of actual spending history to understand where money is going before setting or adjusting category amounts.
View source ↗Consumer Financial Protection Bureau
Your Money, Your Goals Toolkit
Supports cash-flow planning, tracking income and bills, spending decisions, and coordinating available resources with the timing of expenses.
View source ↗Utah State University Extension
Budgeting Methods
Supports the role of the envelope method primarily within variable-expense management and the broader budgeting system.
View source ↗Verestly does not treat one budgeting method, category split, or spending limit as universally correct. The examples in this guide are designed to explain how envelope budgeting works and how readers can adapt it to their own available income, expenses, priorities, and cash-flow needs.
LAST REVIEWED
October 2026
This guide is periodically reviewed for accuracy, clarity, source quality, link integrity, and changes that may affect readers.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on practical systems, clear explanations, and actionable financial tools that help readers make more informed money decisions.
View author profile →THE VERESTLY NEWSLETTER
Build a Better Money System, One Step at a Time
Get practical guides, financial tools, and beginner-friendly
resources designed to help you make clearer money decisions.
✓ Practical financial education
✓ New calculators and tools
✓ Actionable money systems
No spam. Just practical money guidance. Unsubscribe anytime.
RELATED ANSWERS
Keep Exploring
Continue with three closely related guides selected to deepen your understanding.