TAXES · PRACTICAL GUIDE
How to Read Your Pay Stub
Learn how to read your pay stub from gross pay to take-home pay, including taxable wages, tax withholding, paycheck deductions, employer contributions, and year-to-date totals.
QUICK ANSWER
The Short Answer
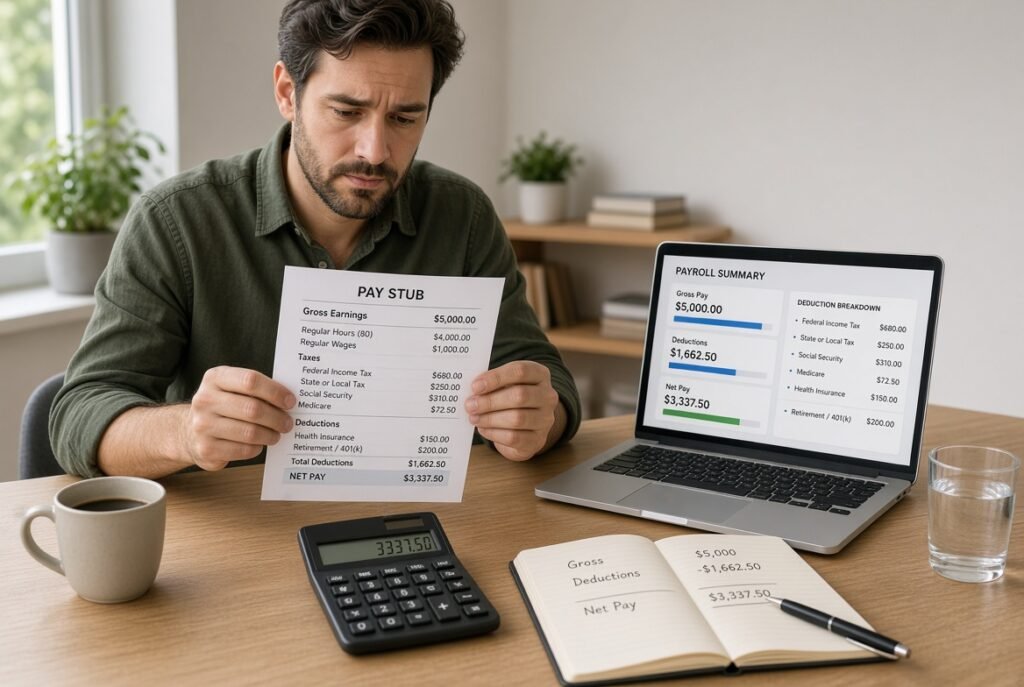
A pay stub shows how your gross earnings become take-home pay. Start with the pay period and earnings, then review taxable wages, taxes withheld, other deductions, employer contributions, net pay, and year-to-date totals.
What to Check
- ✓ Confirm the pay period, pay date, hours, rate, or salary earnings.
- ✓ Compare gross pay with federal, Social Security, and Medicare wages.
- ✓ Separate tax withholding from benefits and other paycheck deductions.
- ✓ Verify net pay and year-to-date totals for anything unexpected.
WHY THIS MATTERS
Why Your Pay Stub Is Worth Reviewing
Your pay stub is the record that connects what you earned with what was withheld, deducted, contributed, and ultimately paid to you.
A paycheck deposit only shows the amount that reached your account. Your pay stub explains how your employer arrived at that number.
It can show whether your hours or salary were recorded correctly, how much federal income tax was withheld, what went toward Social Security and Medicare, and which benefits or other deductions came out of your pay.
Reviewing those details can also help you notice unexpected changes, understand why your take-home pay moved, and keep more accurate records for tax season.
PARENT GUIDE Taxes for Beginners: How Federal Income Taxes Work →KEY IDEA
Your bank deposit tells you how much you received. Your pay stub tells you how that amount was calculated.
STEP-BY-STEP METHOD
How to Read Your Pay Stub From Top to Bottom
Pay stub layouts vary, but the same basic information usually appears in some form. Read each section in order so you can trace how your earnings became your final take-home pay.
STEP 1
Confirm the Pay Period and Pay Date
Start by checking which dates the pay stub covers. The pay period shows when the earnings were recorded, while the pay date shows when you were paid.
These dates may be different. Verifying them first helps prevent you from comparing the wrong hours, deductions, or paycheck amount.
PRACTICAL TIP
If something looks unusual, confirm that you are reviewing the correct pay period before assuming there is a payroll error.
STEP 2
Review Your Earnings and Gross Pay
Next, look at how your earnings were calculated. Depending on your job, the earnings section may include regular wages, salary, overtime, bonuses, commissions, paid time off, or other compensation.
- Regular hours and hourly rate
- Overtime hours and rate
- Salary earnings
- Bonuses or commissions
- Paid time off or other earnings
KEY TERM
Gross pay is generally your earnings before taxes and employee deductions are subtracted.
STEP 3
Compare Gross Pay With Taxable Wages
Your pay stub may show several wage amounts, such as federal taxable wages, Social Security wages, and Medicare wages. These numbers do not always have to match your gross pay.
Different benefits and payroll deductions can receive different tax treatment. A deduction that reduces wages for one tax may not reduce wages for another.
EXAMPLE ASSUMPTION
This simplified example assumes a traditional pre-tax 401(k) contribution that reduces wages subject to federal income tax withholding but remains subject to Social Security and Medicare taxes. Your actual payroll treatment depends on the deduction and plan.
STEP 4
Identify Taxes and Other Deductions
Separate tax withholding from other amounts taken out of your pay. They may appear together on the stub, but they do not all represent the same type of deduction.
- Federal income tax withholding
- Social Security tax
- Medicare tax
- State or local taxes, when applicable
- Health or insurance deductions
- Retirement or other benefit contributions
IMPORTANT
Do not assume every deduction labeled “pre-tax” reduces every type of tax. The treatment depends on the benefit and the applicable tax rules.
STEP 5
Find Your Net Pay
Net pay is the amount left after applicable taxes and employee deductions have been taken out. It is often called your take-home pay.
Compare the net amount on the pay stub with the amount actually distributed to you. If your pay is split between multiple accounts, compare the combined deposits rather than only one account.
SIMPLE FLOW
Gross earnings → taxable-wage adjustments → taxes and deductions → net pay.
STEP 6
Check the Year-to-Date Totals
Finally, review the year-to-date, or YTD, column. It generally shows cumulative payroll amounts from the beginning of the year through the current paycheck.
- Do gross earnings increase as expected?
- Are tax-withholding totals moving consistently?
- Are benefit and retirement deductions still appearing?
- Does anything look unexpectedly different from the prior stub?
Comparing current-period and YTD figures can make unexpected payroll changes easier to spot.
REAL-LIFE EXAMPLE
How the Numbers on a Pay Stub Fit Together
Instead of focusing on a fictional worker, this example follows one simplified paycheck from gross earnings to net pay.
SIMPLIFIED PAYCHECK
Start With $3,000 in Gross Earnings
Assume a biweekly paycheck starts with $3,000 in gross earnings. The employee contributes $150 to a traditional 401(k). For this example, that contribution reduces federal taxable wages but does not reduce Social Security or Medicare wages.
| Pay Stub Item | Amount |
|---|---|
| Gross earnings | $3,000.00 |
| Traditional 401(k) contribution | −$150.00 |
| Federal taxable wages | $2,850.00 |
| Social Security wages | $3,000.00 |
| Medicare wages | $3,000.00 |
| Federal income tax withheld | −$240.00 |
| Social Security tax | −$186.00 |
| Medicare tax | −$43.50 |
| Total employee taxes and deductions | −$619.50 |
| Net pay | $2,380.50 |
FOLLOW THE FLOW
The Same Paycheck Can Show Different Wage Numbers
Gross earnings begin at $3,000, but federal taxable wages fall to $2,850 under the assumptions in this example because of the $150 traditional 401(k) contribution.
Social Security and Medicare wages remain at $3,000 here because traditional 401(k) employee deferrals generally remain subject to those payroll taxes even when they reduce wages subject to federal income tax withholding.
PAYCHECK FLOW
THE TAKEAWAY
Do not read a pay stub as one long list of subtractions. First identify earnings, then taxable wages, then taxes and deductions, and finally net pay.
This example is illustrative and uses simplified assumptions. The $240 federal income tax withholding amount is hypothetical and is not calculated using a flat tax rate. Actual withholding, taxable wages, deductions, and net pay depend on compensation, Form W-4 information, benefit elections, location, and other circumstances.
READ THE DIFFERENCES
Why the Numbers on Your Pay Stub May Look Different
Not every pay stub will show the same wage amounts, deductions, or tax lines. The differences often come from compensation type, benefit elections, payroll taxes, and year-to-date thresholds.
TAXABLE WAGES
If Gross Pay Is Higher Than Federal Taxable Wages
Some payroll deductions can reduce wages subject to federal income tax withholding. A traditional 401(k) contribution is one common example, although the exact treatment depends on the type of deduction and plan.
WITHHOLDING
If Federal Income Tax Withholding Changes
Federal withholding can change when wages change, when bonus or other supplemental pay is included, or when the information used from Form W-4 changes.
BENEFITS
If a Benefit Deduction Appears, Changes, or Disappears
Health coverage, retirement contributions, insurance, HSA or FSA elections, and other workplace benefits can affect the deductions shown on your pay stub.
YEAR-TO-DATE
If a Payroll Tax Line Changes Later in the Year
Some payroll taxes use annual wage thresholds. For example, Social Security tax applies only up to the annual Social Security wage base, while Medicare does not use the same wage-base limit.
SOMETHING STILL LOOKS OFF?
Compare the current pay stub with the prior one and identify which section changed first: earnings, taxable wages, taxes, deductions, or employer contributions. That usually narrows down the source of the difference quickly.
OFFICIAL IRS TOOL
Review Your Federal Tax Withholding
If the federal income tax withholding on your pay stub looks higher or lower than expected, the IRS Tax Withholding Estimator can help you review your current withholding using your recent pay information and other relevant tax details.
- ✓ Use recent pay stubs to enter current wages and federal withholding.
- ✓ Compare current withholding with an estimate based on the information you provide.
- ✓ Review whether a Form W-4 adjustment may be worth considering.
Free · Official IRS resource · Uses your current tax information
RECENT PAY STUB
Current period
Illustrative pay-stub inputs
BEFORE YOU START
Have recent pay stubs available, along with information about other income and your expected tax situation. The estimator's result depends on the information you provide.
TAKE ACTION
Your Pay Stub Review Plan
You do not need to audit every payroll calculation. A short, repeatable review can help you confirm the main numbers, notice changes, and identify when something deserves a closer look.
START HERE
5–10 minutes
Confirm the Basic Payroll Details
Begin with the information that should be easiest to verify against your own records.
- Confirm the pay period and pay date.
- Review regular hours, overtime, salary, bonus, or commission amounts.
- Check that gross earnings look consistent with what you expected.
NEXT
Trace the deductions
Review Taxable Wages, Taxes, and Benefits
Look at the amounts between gross earnings and net pay. Separate taxes from benefit deductions instead of treating everything as one category.
- Compare gross pay with federal, Social Security, and Medicare wages.
- Review federal, state, and local withholding shown on the stub.
- Confirm expected retirement, insurance, HSA, FSA, or other benefit deductions.
- Distinguish employee deductions from employer contributions.
FINISH
Verify the result
Compare Net Pay and Year-to-Date Totals
Finish by confirming what was actually paid and whether the cumulative totals still make sense compared with prior pay stubs.
- Compare net pay with the amount distributed to your accounts.
- Review YTD earnings, taxes, and deductions for unexpected changes.
- Compare the current stub with the previous one if something moved.
- Ask payroll or review official guidance if you cannot explain a material difference.
QUICK CHECK
A Useful Pay Stub Review Should Answer One Question
Can you explain how your gross earnings became the net pay that was actually deposited?
COMMON MISTAKES
Common Pay Stub Mistakes to Avoid
Most pay stub confusion comes from treating different payroll numbers as if they mean the same thing. A few simple distinctions make the document much easier to read.
MISTAKE
Treating Gross Pay as Take-Home Pay
Gross pay is your earnings before applicable taxes and employee deductions are taken out. It is not the amount you should expect to see deposited into your bank account.
BETTER APPROACH
Start with gross earnings, then trace the deductions and taxes until you reach net pay.
MISTAKE
Assuming All Wage Numbers Should Match
Federal taxable wages, Social Security wages, Medicare wages, and gross pay can differ because different payroll deductions may receive different tax treatment.
BETTER APPROACH
Read each wage line according to the tax it applies to instead of assuming every wage base should be identical.
MISTAKE
Treating Every Deduction as a Tax
Health insurance, retirement contributions, HSA or FSA amounts, union dues, and other payroll deductions are not the same as federal income tax, Social Security, or Medicare withholding.
BETTER APPROACH
Separate taxes, employee benefit deductions, and employer contributions into different categories.
MISTAKE
Comparing Federal Withholding Directly With Your Tax Bracket
Federal income tax withholding is not calculated by simply multiplying your gross paycheck by your marginal tax rate. Payroll withholding uses applicable IRS withholding methods and information from Form W-4.
BETTER APPROACH
Review withholding in the context of your projected annual income and tax situation rather than judging one paycheck by a single tax-bracket percentage.
MISTAKE
Looking at Only One Pay Stub in Isolation
A single paycheck shows only one payroll period. Changes in earnings, withholding, benefits, or annual thresholds can be easier to understand when you compare the current stub with prior pay periods and year-to-date totals.
BETTER APPROACH
Use both current-period and YTD figures, and compare the current pay stub with the previous one when something looks unexpectedly different.
REMEMBER
The goal is not to memorize every payroll rule. It is to know what each major section represents so you can spot a change, ask the right question, and verify the number when needed.
FREQUENTLY ASKED QUESTIONS
Common Questions About Reading a Pay Stub
These questions address the pay stub terms and differences that most often confuse employees when they review their paycheck details.
What does YTD mean on a pay stub? +
YTD means year to date. It generally shows the cumulative amount from the beginning of the payroll year through the current paycheck.
You may see YTD totals for gross earnings, taxable wages, federal withholding, Social Security tax, Medicare tax, retirement contributions, and other deductions.
Why is my federal taxable pay lower than my gross pay? +
Certain payroll deductions may reduce wages subject to federal income tax withholding. A traditional 401(k) contribution is one common example.
Different deductions can receive different tax treatment, so gross pay, federal taxable wages, Social Security wages, and Medicare wages do not always have to match.
Is Social Security tax the same as federal income tax withholding? +
No. Federal income tax withholding is a payment toward federal income tax. Social Security tax is a separate payroll tax.
Medicare tax is also separate. Social Security and Medicare taxes are commonly associated with FICA payroll taxes.
Why did my federal withholding change? +
Federal income tax withholding can change when your wages change, when bonus or other supplemental compensation is paid, or when the information used from Form W-4 changes.
A change in withholding does not automatically mean an error occurred. Compare the current stub with the prior one and review what changed in your earnings or withholding information.
Review your withholding with the IRS estimator →Why did my net pay change if my salary stayed the same? +
Net pay can change even when base salary stays the same. Possible reasons include withholding changes, retirement contributions, insurance premiums, benefit elections, bonuses, payroll corrections, state or local taxes, or other deductions.
Compare the current pay stub with the previous one and identify which section changed first: earnings, taxable wages, taxes, deductions, or employer contributions.
Should the numbers on my pay stub match my W-2 exactly? +
Not every number should be assumed to match automatically. A pay stub shows information for individual payroll periods and often includes year-to-date totals, while Form W-2 is an annual tax reporting document.
Different W-2 boxes also use different wage definitions, so compare each amount according to what the field represents rather than expecting every figure to be identical.
KEEP LEARNING
Continue With the Next Most Useful Tax Guides
These topics help connect the information on your pay stub with withholding, tax documents, and the broader filing process.
What Is Tax Withholding?
Learn why employers withhold federal income tax from paychecks and how withholding connects with your annual federal tax return.
Related tax guide →Tax Documents Checklist: What to Gather Before You File
Organize the tax forms and records you may need before preparing your federal return.
Related tax guide →Tax Deductions vs. Tax Credits: What Is the Difference?
Learn why reducing taxable income and reducing tax itself are two different concepts.
Related tax guide →WANT THE BIGGER PICTURE?
Return to the Taxes foundation guide to understand how paycheck withholding connects with taxable income, federal income tax, filing, refunds, and balances due.
SOURCES & METHODOLOGY
How We Verified This Guide
Verestly reviewed current IRS guidance and U.S. Department of Labor recordkeeping information to verify the payroll-tax, withholding, taxable-wage, and pay-record concepts explained in this guide.
LAST REVIEWED
September 2026
This guide was reviewed against current 2026 federal payroll-tax and withholding guidance. Tax rules and payroll procedures can change, so time-sensitive figures are checked against current official sources.
ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and careful use of authoritative sources.
View author profile →THE VERESTLY NEWSLETTER
Build a Better Money System, One Step at a Time
Get practical guides, financial tools, and beginner-friendly
resources designed to help you make clearer money decisions.
✓ Practical financial education
✓ New calculators and tools
✓ Actionable money systems
No spam. Just practical money guidance. Unsubscribe anytime.
RELATED ANSWERS
Keep Exploring
Continue with three closely related guides selected to deepen your understanding.