BUDGETING · BEGINNER GUIDE
Budgeting for Beginners: A Complete Step-by-Step Guide
Learn how to understand your income, organize expenses, build a practical budget, make trade-offs, track your spending, and adjust your plan as your finances change.
QUICK ANSWER
The Short Answer
Budgeting is the process of deciding how the money available to you will be used. A practical budget starts with your take-home income, accounts for regular and less-frequent expenses, assigns money according to your priorities, and gives you a system for tracking and adjusting the plan when real life differs from what you expected.
What You'll Learn
- ✓ How to calculate the income available for your budget.
- ✓ How to identify and organize your actual expenses.
- ✓ How to assign money across bills, priorities, and future expenses.
- ✓ How common budgeting methods can add structure without becoming rigid rules.
- ✓ How to review, adjust, and improve your budget over time.
STEP 1 · KNOW YOUR AVAILABLE INCOME
Start With the Income You Can Actually Use
Before assigning money to expenses or goals, identify how much income will actually be available during the period you are budgeting. For most beginners, that means starting with take-home pay and adding only other income you can reasonably expect to receive.
Start with take-home pay
If you receive a paycheck, use the amount that reaches your account after taxes, insurance, retirement contributions, and other payroll deductions. That is usually more useful for budgeting than your gross salary.
Add other reliable income
Include income you reasonably expect during the budgeting period, such as wages, recurring self-employment income, benefits, support payments, pension income, or other dependable household income.
Be cautious with uncertain income
Overtime, bonuses, commissions, tips, and side income can fluctuate. Avoid building required expenses around money that may not arrive. You can decide how to allocate extra income after it becomes available.
Adjust the process if income changes
If your income varies substantially from month to month, you can still budget. The difference is that your plan needs to account for changing income instead of assuming every month will provide the same amount.
Use realistic income numbers rather than optimistic ones. A budget built around money you can reasonably expect gives you a more reliable starting point for every allocation that follows.
STEP 2 · BUILD YOUR SPENDING BASELINE
Find Out What You Actually Spend
Before changing your spending, understand what is already happening. Review several months of real transactions so your first budget is based on evidence rather than estimates that may be too optimistic.
Gather Your Records
Review bank accounts, credit card statements, payment apps, receipts, and other places where spending appears.
Look Back Several Months
One month can miss seasonal bills, medical costs, maintenance, gifts, or other less-frequent expenses.
Record What Really Happened
Use actual amounts instead of replacing them with what you think you should have spent.
Separate Patterns From Surprises
Notice recurring costs, flexible spending, and expenses that are irregular but still reasonably predictable.
Build Your Baseline
Use the patterns you found as the starting point for the categories and allocations in your first budget.
Accuracy comes before optimization
Beginners often try to create an ideal budget before they understand their current spending. That can make the plan look disciplined on paper while creating targets that are difficult to use in real life.
If groceries have recently averaged $620 per month, entering $450 simply because it feels like a better target does not improve the budget. First record the $620 baseline. Then decide whether reducing it is realistic and what would need to change for that reduction to happen.
Review both recurring expenses—such as housing, utilities, insurance, transportation, and minimum debt payments—and flexible spending such as groceries, dining, entertainment, household purchases, and personal spending.
CORE PRINCIPLE
Your first spending baseline should describe reality before it tries to improve it. Better budgeting decisions begin with numbers you can trust.
STEP 3 · ORGANIZE YOUR SPENDING
Organize Your Expenses Into Useful Categories
Budget categories turn individual transactions into groups that are easier to plan and adjust. You do not need a perfect category system. Start with enough structure to see your obligations, flexible spending, and competing priorities clearly.
CATEGORY GROUP 1
Start With Required Expenses
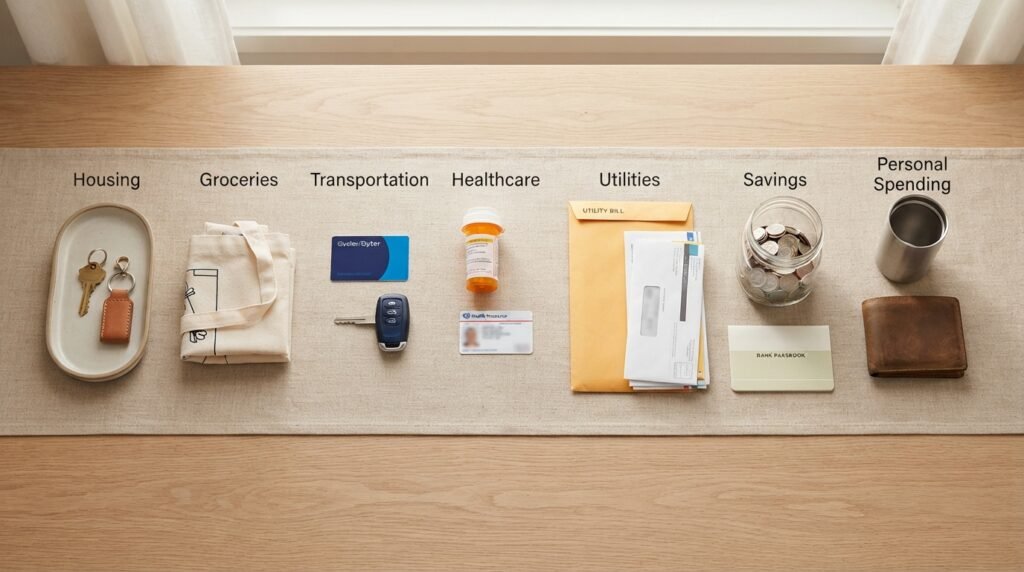
Begin with expenses that need to be covered for the month to function, such as housing, utilities, basic transportation, insurance, childcare, healthcare, and required debt payments.
These costs often take up a large share of available income, so identifying them first helps you see how much flexibility remains for other categories.
KEY IDEA
Required does not always mean permanently fixed. It means the expense needs to be accounted for in your current plan.
CATEGORY GROUP 2
Separate Variable Essentials
Some necessary expenses change from month to month. Groceries, fuel, electricity, prescriptions, and household supplies are common examples.
Because the amount can move even when the expense itself is necessary, these categories usually benefit from realistic estimates based on recent spending rather than rigid targets.
- Groceries and basic household supplies.
- Fuel, transit, or other everyday transportation costs.
- Utilities that change with usage or season.
- Routine healthcare and prescription expenses.
CATEGORY GROUP 3
Identify Flexible Spending
Flexible categories are areas where the timing, amount, or frequency of spending can usually be adjusted more easily. Examples can include dining out, entertainment, hobbies, clothing, and discretionary shopping.
Flexible does not mean unnecessary. These categories may support enjoyment, convenience, relationships, or quality of life. Their role in the budget is to show where trade-offs are possible when priorities compete.
CATEGORY GROUP 4
Include Required Debt Payments
Debt payments belong in your budget because they affect how much income remains available for everything else. At minimum, account for the payments required during the budgeting period.
Choosing which debt to pay off first, whether to make extra payments, or whether consolidation makes sense requires a separate debt strategy. Here, the budgeting job is simply to make the cash-flow impact visible.
CATEGORY GROUP 5
Give Future Priorities a Place in the Budget
If part of your income is intended for a future expense or financial goal, include that allocation in the budget instead of waiting to see what is left at the end of the month.
This can include money reserved for future purchases, planned expenses, or savings goals. The detailed strategy for emergency funds, sinking funds, and savings priorities belongs in dedicated Saving guidance.
BUDGETING ROLE
The budget decides how much money is assigned. A dedicated saving system determines how that money is stored and managed.
CATEGORY GROUP 6
Customize the Categories Around Your Life
No category list works identically for every household. Caregiving, healthcare, housing, transportation, work, disability, education, location, and family responsibilities can all change which expenses are necessary and how much flexibility exists.
Use categories that help you make decisions. If a category is so broad that you cannot tell what is happening, split it. If several tiny categories create more tracking work than useful information, combine them.
CORE PRINCIPLE
Categories are planning tools, not moral labels. Their job is to make allocation and trade-offs easier to understand.
STEP 4 · PLAN BEYOND THIS MONTH
Plan for Expenses That Do Not Happen Every Month
A monthly budget can look balanced and still fail when annual, seasonal, or irregular-but-predictable expenses arrive. Bring those costs into your plan before they are due so they do not automatically become financial surprises.
Identify Non-Monthly Costs
Look for expenses such as insurance premiums, vehicle registration, school costs, gifts, medical expenses, home maintenance, travel, and annual subscriptions.
Estimate the Expected Cost
Use recent bills, past transactions, renewal notices, or a reasonable estimate to determine how much the expense may cost when it arrives.
Convert It Into a Planning Amount
If an expense occurs annually or periodically, divide the expected cost across the months or pay periods available before it is due.
Include It in Your Budget
Give the future expense a place in your current allocation so the money is not accidentally committed to another category.
Update the Estimate Over Time
Compare the amount you planned with the amount you eventually pay. Use that information to make the next budget more accurate.
VERESTLY EDUCATIONAL FRAMEWORK
Think in terms of Notice → Estimate → Divide → Allocate → Adjust. This is an educational budgeting framework, not a universal rule. Its purpose is to keep predictable future costs visible in the spending plan before they become due.
SIMPLE EXAMPLE
If you expect approximately $600 in vehicle registration and maintenance costs over the next year, planning an average of $50 per month can make those future costs easier to absorb. The actual amount may still need to be adjusted.
BEGINNER BUDGET EXAMPLE
What a Beginner Budget Can Look Like
A sample budget can make the allocation process easier to see. The example below shows how one household might assign $4,000 of monthly take-home income across current expenses, future priorities, and some room for adjustment.
EXAMPLE HOUSEHOLD
A $4,000 Monthly Budget
This household has $4,000 in monthly take-home income. The goal is not to follow a universal percentage formula. It is to make sure the money available has clear jobs before the month begins.
The exact amounts would look different for another household with different housing, transportation, healthcare, childcare, debt, or family costs.
| Housing | $1,400 |
|---|---|
| Utilities and internet | $260 |
| Groceries | $500 |
| Transportation | $400 |
| Insurance and healthcare | $300 |
| Required debt payments | $250 |
| Future expenses and savings | $350 |
| Personal and household | $200 |
| Dining and entertainment | $200 |
| Adjustment room | $140 |
| Total planned | $4,000 |
HOW TO READ THE EXAMPLE
Five Lessons From This Budget
MATCH
The Plan Fits Available Income
Total planned allocations equal the $4,000 available. There is no unassigned income and no planned deficit.
PRIORITIZE
Required Costs Come First
Housing, utilities, food, transportation, healthcare, and required debt payments are visible before more flexible allocations are considered.
PREPARE
Future Costs Are Included
Part of the monthly income is deliberately assigned to future expenses or savings instead of depending on whatever happens to remain at month-end.
FLEX
Some Categories Can Move
Dining, entertainment, personal spending, and other flexible areas can be adjusted when another category requires more money than expected.
ADJUST
The Numbers Can Change
If actual spending differs from the plan, the household can reallocate money and use the result to improve the next month's budget.
THE TAKEAWAY
The Allocation Matters More Than the Percentages
This example is not a recommended spending split. A household paying more for housing, childcare, healthcare, transportation, or other required costs may need a very different allocation. The useful principle is that available income is assigned deliberately, the trade-offs are visible, and the plan can be adjusted when circumstances change.
This example is illustrative, not a universal recommendation. Real budgets depend on income, household responsibilities, local costs, required expenses, priorities, and other individual circumstances.
STEP 5 · CHECK WHETHER THE PLAN FITS
Compare Your Planned Outflows With Available Income
Once your expenses and future allocations are visible, compare their total with the income available for the same period. The result tells you whether money is still unassigned, the plan already balances, or changes are needed before the month begins.
IF INCOME IS HIGHER
You Have Money Left to Assign
If available income is greater than your planned expenses and allocations, the difference is not automatically extra spending money. It is money that still needs a job in the plan.
Depending on your circumstances, you might strengthen a current category, prepare for a future expense, support a savings goal, make an additional debt payment, or leave more room for expected variability.
IF THE TOTALS MATCH
Every Dollar Already Has a Planned Job
If planned outflows equal available income, your budget is balanced on paper. That can be a workable structure, but the numbers are still estimates until the month actually happens.
A balanced plan does not require every category to finish at exactly its original amount. The overall budget can remain workable even when individual categories move.
IF PLANNED OUTFLOWS ARE HIGHER
Your First Plan Does Not Fit the Income Available
A planned deficit means more money has been assigned than you expect to have. The next step is to identify which allocations can realistically change and which expenses are difficult to move in the current period.
Look first at timing, optional allocations, adjustable categories, and estimates that may be too high or too low. The goal is to make realistic trade-offs—not force every expense into the same reduction.
IF ESSENTIALS ALONE EXCEED INCOME
The Problem May Be Bigger Than the Budget
If housing, basic food, healthcare, transportation, required payments, and other essential costs already exceed available income, the shortfall is not simply a category-management problem.
A budget can clarify the constraint and help protect the most important obligations, but it cannot create income that is not available. A large structural shortfall requires solutions beyond ordinary spending adjustments.
MAKE THE TRADE-OFFS VISIBLE
Assign the Money You Have, Not the Money You Wish You Had
When several priorities compete for the same dollars, budgeting cannot make all of them fit automatically. It helps you see the decision clearly enough to choose what gets funded now, what is reduced, and what may need to wait.
If three priorities each need $150, the budget makes the $250 shortfall visible so you can decide how to allocate the $200 that actually exists.
CHOOSE A BUDGETING STRUCTURE
Which Budgeting Method Fits the Problem You Need to Solve?
You do not need a named budgeting method to manage your money. The basic process still comes first: understand your income, plan your expenses, assign available money, track what happens, and adjust. A budgeting method simply adds structure when that structure is useful.
- ✓ Use a percentage framework when broad allocation guidance helps.
- ✓ Use detailed assignment when you want every expected dollar to have a purpose.
- ✓ Use timing-based or variable-income methods when the calendar matters as much as the monthly total.
No method is universally better. Choose the structure that addresses your current budgeting problem, and adapt it when your household, income, or expenses change.
START WITH THE PROBLEM
What kind of structure would make your budget easier to use?
YOU CAN ALSO KEEP IT SIMPLE
If your current budget already helps you assign income, cover expenses, anticipate future costs, and make adjustments, you do not need to switch methods just because another framework is popular.
OPERATE · REVIEW · ADJUST
How to Use Your Budget During the Month
A budget is not something you create once and judge at the end of the month. Use it as a working plan: confirm what is coming in, monitor what is going out, adjust when reality changes, and use what you learn to improve the next budget.
BEFORE THE PERIOD BEGINS
Confirm the planCheck Income, Bills, and Known Changes
Start by confirming the assumptions behind your budget. Review expected take-home income, upcoming bills, due dates, unusual expenses, and any priorities that have changed since your last plan.
- Confirm the income you reasonably expect to receive.
- Review bills and their due dates.
- Add known one-time or seasonal expenses.
EARLY IN THE MONTH
Protect required spendingKeep Required Expenses Visible
Make sure housing, utilities, transportation, healthcare, required debt payments, and other necessary obligations remain covered before flexible categories absorb more of the available cash than planned.
- Check which required payments are still ahead.
- Watch for bills that differ from your estimate.
- Avoid treating money reserved for later bills as available spending.
DURING THE MONTH
Compare plan vs. actualTrack Enough to Know Whether the Plan Still Works
You do not necessarily need to record every transaction by hand. What matters is being able to compare planned and actual spending closely enough to see when a category is moving away from the original estimate.
- Watch categories that can change quickly, such as groceries and fuel.
- Check flexible spending before it becomes difficult to adjust.
- Keep an eye on cash timing as well as monthly totals.
WHEN REALITY CHANGES
ReallocateAdjust the Budget Instead of Abandoning It
If one category costs more than expected, check whether another flexible category can absorb the difference without putting required obligations at risk.
- Identify how large the difference is.
- Decide which flexible allocation can change.
- Update the plan so the new trade-off is visible.
If groceries are $70 above plan and entertainment is $120 below plan, moving $70 between those categories can keep the overall budget balanced.
AT THE END OF THE PERIOD
Learn and improveUse Actual Results to Build the Next Budget
Compare the original plan with what actually happened. The purpose is not to score the month as a success or failure. It is to identify which assumptions were accurate, which categories need different amounts, and what changed.
- Review the largest differences between planned and actual spending.
- Identify categories that repeatedly need adjustment.
- Carry what you learned into the next budget.
CORE PRINCIPLE
A Budget Is a Forecast, Not a Promise
Actual spending will not always match the original plan. Changing the budget when income, expenses, or priorities change is part of the process. Repeated differences are useful information: they show you where the next plan needs to become more realistic.
AVOID THESE PITFALLS
Common Beginner Budgeting Mistakes
A budget usually becomes difficult to use because the plan does not match reality—not because you failed at budgeting. These are some of the most common structural problems to watch for when building and using your first budget.
Budgeting From Ideal Numbers
Lowering a category on paper does not automatically reduce what you actually spend. Unrealistic targets can make the budget appear broken even when the real problem is the estimate.
Start with recent actual spending, then make deliberate changes once you understand the baseline.
Forgetting Non-Monthly Expenses
Annual fees, vehicle costs, medical expenses, gifts, school costs, insurance premiums, and other periodic expenses can make an otherwise balanced month fall apart.
Identify predictable future costs and assign part of your current income toward them before they are due.
Making Categories Too Complicated
Dozens of tiny categories can create more tracking work than useful information, especially when you are still learning how your spending behaves.
Use enough categories to support decisions. Split a category only when the added detail is genuinely useful.
Treating Every Category as Fixed
Some costs are difficult to change in the current month, while others can move more easily. Treating every expense the same can hide where useful trade-offs actually exist.
Separate required obligations from categories where timing, amount, or frequency can realistically change.
Abandoning the Budget After Overspending
Spending more than planned in one category does not automatically mean the entire budget failed. It may simply mean the original allocation needs to change.
Reallocate where possible, protect required expenses, and use the difference to improve your next plan.
Assuming a Budget Can Fix an Income Shortfall
If essential expenses consistently exceed available income, cutting small discretionary categories may not be enough to close the gap.
Use the budget to measure the shortfall, protect the most important obligations, and distinguish allocation problems from deeper income or cost constraints.
FREQUENTLY ASKED QUESTIONS
Budgeting Questions Beginners Often Ask
These short answers address common questions that come up when you are building, using, and adjusting a budget for the first time.
Do I need to track every purchase?
Not necessarily. You need enough visibility to compare planned and actual spending and notice when important categories are moving away from your plan. Manual transaction-by-transaction tracking is only one way to do that.
What should I do if I keep overspending the same category?
Repeated overspending may mean the category target is too low for your actual circumstances. Review the underlying transactions, set a more realistic amount if needed, and make the corresponding trade-off elsewhere in the budget.
What if my income changes from month to month?
You can still budget, but a fixed monthly income assumption may not work well. Use conservative income estimates, prioritize required expenses, and adapt the plan as actual income becomes known. A dedicated irregular-income method can add more structure when variability is significant.
Should savings be included in my budget?
Yes, if setting aside money is one of the jobs you want your income to perform. The budget determines how much is allocated. Detailed emergency-fund targets, sinking-fund systems, and savings priorities belong in dedicated Saving guidance.
Which budgeting method is best for beginners?
There is no single best method for every beginner. 50/30/20, zero-based budgeting, paycheck budgeting, and irregular-income budgeting solve different planning problems. Start with the basic budgeting process, then use a method only if its structure makes your plan easier to operate.
How often should I review my budget?
Review the budget during the month often enough to catch meaningful changes before they become difficult to manage, then complete a fuller review at the end of the budgeting period. Major changes in income, expenses, or household responsibilities may require an earlier adjustment.
CONTINUE YOUR BUDGETING JOURNEY
Where to Go Next
Once you understand the basic budgeting process, the next useful step depends on what makes your own cash flow harder to manage. Go deeper only where additional structure solves a real problem.
MANAGE TIMING
Budget Around Your Paychecks
Choose this path if your monthly totals look manageable but bills and spending often fall at awkward points between paydays. Paycheck budgeting focuses on when money arrives and which expenses each paycheck needs to cover.
HANDLE VARIABLE INCOME
Adapt Your Budget When Income Changes
Use this path if commissions, tips, freelance work, seasonal earnings, or other variable income make a fixed monthly income assumption unreliable. The goal is to build flexibility without pretending every month will look the same.
PLAN AHEAD
Prepare for Future and Irregular Expenses
If annual bills, repairs, gifts, travel, or other predictable future costs keep disrupting your monthly plan, budgeting can identify the allocation—but a dedicated saving system can help you manage those reserves more deliberately.
IMPROVE THE SYSTEM
Review What Happened and Improve the Next Budget
Choose this path if you already have a working budget and want a more structured end-of-month process for comparing planned and actual spending, identifying recurring differences, and improving your next set of allocations.
KEEP BUILDING THE SYSTEM
Use the Next Resource That Solves Your Next Budgeting Problem
You do not need every budgeting method, calculator, or worksheet at once. Start with the process in this guide, then add another resource only when it makes allocation, timing, tracking, or adjustment easier.
SOURCES & METHODOLOGY
How We Built This Budgeting Guide
This guide was developed using primary U.S. government sources and consumer-finance guidance. We used these references to verify core budgeting concepts, including income and expense planning, reviewing actual spending, accounting for less-frequent costs, comparing planned outflows with take-home pay, and adjusting a budget as circumstances change.
LAST REVIEWED
September 2026
We reviewed this guide for budgeting accuracy, source quality, beginner clarity, search-intent ownership, and consistency with current Verestly editorial standards.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and actionable tools that help readers make more informed money decisions.
View author profile →VERESTLY NEWSLETTER
Build a Budget That Gets More Useful Over Time
Get practical guides, budgeting tools, and beginner-friendly resources designed to help you plan your money, understand trade-offs, and make clearer financial decisions.
- Practical budgeting education
- New calculators and resources
- Beginner-friendly money systems
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Budgeting Guides
Continue with guides that go deeper into the budgeting method, cash-flow pattern, or adjustment process that is most relevant to your situation.