BUDGETING · PRACTICAL GUIDE
How to Budget by Paycheck Without Running Short Between Paydays
Learn how to match each paycheck to upcoming bills, everyday spending, and planned priorities so you know what needs to be covered before the next payday arrives.
QUICK ANSWER
The Short Answer
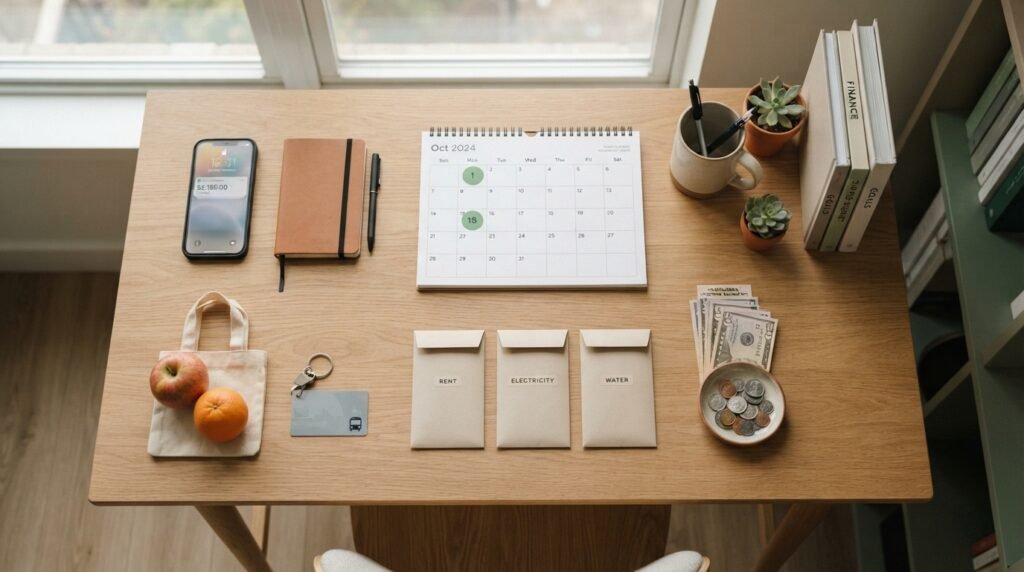
Paycheck budgeting means assigning each paycheck to the bills, everyday expenses, and planned priorities that need to be covered before the next paycheck arrives. Instead of planning only by calendar month, you organize your spending around the timing of your actual income.
What You'll Do
- ✓ Map each paycheck to the bills due before the next one.
- ✓ Estimate groceries, transportation, and other everyday costs for that pay period.
- ✓ Reserve money now for obligations that arrive before a later paycheck can cover them.
- ✓ Adjust the plan when timing or spending changes before the next payday.
WHY THIS MATTERS
Why Monthly Budgets Can Still Leave You Short Between Paydays
A monthly budget can balance on paper and still leave you short during part of the month. The missing piece is often not how much money you have overall, but when that money becomes available.
A monthly budget answers an important question: where should your available income go this month? But monthly totals do not always show whether enough cash will be available on the specific days your expenses need to be paid.
Bills are rarely distributed evenly. One paycheck might need to cover rent, utilities, groceries, transportation, and other recurring obligations, while the next paycheck has fewer immediate demands.
That creates an important distinction. If your total planned expenses fit within your available monthly income but one part of the month is still short, you may have a timing shortage. If your necessary expenses consistently exceed the income available for the month, the problem is broader than paycheck timing.
Paycheck budgeting adds a timing layer to your existing spending plan. It helps you decide which expenses each paycheck needs to support before the following payday arrives.
PARENT GUIDE Budgeting for Beginners: A Complete Step-by-Step Guide →KEY IDEA
A monthly budget tells you where your money needs to go. A paycheck budget adds when that money needs to be available.
STEP-BY-STEP METHOD
How to Build a Paycheck Budget
Start with your actual paydays, then decide what each paycheck needs to cover before the next one arrives. The goal is not to make every pay period identical, but to give each paycheck a realistic job.
STEP 1
Write Down Your Paycheck Dates and Amounts
Start with the money that is expected to reach your account. Use take-home pay rather than gross income, and list each paycheck separately with its expected date.
Your actual payroll schedule matters. Someone paid twice per month will have a different calendar from someone paid every two weeks, even if both usually receive two paychecks in a month.
PRACTICAL TIP
If you are paid every two weeks, plan from the real dates on your payroll calendar. Some months will contain three paychecks instead of two.
STEP 2
Define What This Paycheck Must Cover
Treat the period from one payday to the next as a coverage window. Identify the bills and recurring obligations that need money during that period.
- Rent or mortgage
- Utilities
- Insurance
- Required debt payments
- Subscriptions
- Childcare or transportation costs
Also look just beyond the next payday. If an important bill is due before a later paycheck will be available, part of the current paycheck may need to remain reserved for it.
GO DEEPER Learn how to plan your budget before the month begins →STEP 3
Estimate Everyday Spending Until the Next Payday
After identifying scheduled obligations, estimate what you realistically need for groceries, transportation, household supplies, and other routine expenses during the same coverage window.
These amounts are illustrative, not recommended limits. Your own categories and amounts should reflect the expenses that actually occur between your paydays.
STEP 4
Look Ahead for Expenses That Need Funding Now
Some expenses do not occur during every pay period but are predictable enough to plan for. If one is approaching, reserve the portion of the current paycheck that your spending plan needs to protect.
- Car maintenance
- Annual or semiannual premiums
- Upcoming medical costs
- School or seasonal expenses
- Other known non-monthly obligations
Paycheck budgeting only needs to identify how these costs affect the current allocation. A dedicated sinking-fund system goes deeper into how money is accumulated for predictable future expenses.
GO DEEPER Learn how sinking funds can prepare for future expenses →STEP 5
Assign the Rest to Your Planned Priorities
Once the paycheck can cover its immediate bills, everyday costs, and any amount that needs to remain available for an upcoming obligation, decide how the rest fits into your broader spending plan.
That may include flexible spending, saving, additional debt payments, or another financial priority. The detailed strategy for those goals belongs in the relevant saving or debt plan; here, the job is simply to make sure the paycheck can support them without leaving the current coverage window short.
IMPORTANT
Do not assign more to later priorities than the paycheck can realistically support after near-term expenses are accounted for.
STEP 6
Review What Happened Before the Next Payday
A paycheck budget is meant to adjust. Before the next paycheck arrives, compare the plan with what actually happened and use that information when building the next coverage window.
- Did any bill cost more or arrive earlier than expected?
- Were your everyday spending estimates realistic?
- Did an unexpected expense change the plan?
- Was enough money still available when the next payday approached?
REAL-LIFE EXAMPLE
What a Paycheck Budget Can Look Like
The purpose of paycheck budgeting is not to divide every monthly expense evenly. It is to match each paycheck with the expenses that need money before the next payday arrives.
EXAMPLE SCENARIO
Jordan Receives a $1,900 Paycheck on the 1st
Jordan's next paycheck arrives on the 15th. Several larger expenses fall during this first coverage window, so this paycheck carries more immediate obligations than the next one.
| Planned use | Amount |
|---|---|
| Rent | $850 |
| Utilities | $140 |
| Required debt payment | $200 |
| Groceries | $180 |
| Transportation | $90 |
| Household / personal | $80 |
| Reserved for an upcoming obligation | $250 |
| Flexible spending | $60 |
| Total assigned | $1,850 |
| Remaining margin | $50 |
WHAT THIS SHOWS
The First Paycheck Does Not Have to Match the Second
Jordan's first paycheck has more immediate demands because rent, utilities, and a required debt payment all fall before the next payday. Groceries, transportation, and other routine costs also need to be funded for the same period.
Jordan also reserves $250 for an upcoming obligation instead of treating that money as available simply because it is still sitting in the account.
The next paycheck can have a different allocation because its coverage window may contain different bills and spending needs. Paycheck budgeting follows timing rather than forcing both paychecks into identical category amounts.
SIMPLE MATH
THE TAKEAWAY
A paycheck budget does not need each payday to look the same. It needs each paycheck to cover the right expenses at the right time.
This example is illustrative, not a recommended spending plan. Your paycheck amounts, bill dates, categories, and available margin will depend on your own circumstances.
ADAPT THE METHOD
What Changes If Your Situation Is Different?
The basic paycheck-budgeting process stays the same, but the way you apply it may need to change depending on your income pattern, bill timing, and how much room your current budget has.
IRREGULAR INCOME
If Your Paycheck Amount Changes From One Period to the Next
Paycheck budgeting can still help, but variable income requires a more flexible framework. Build each coverage window from the income you can reasonably expect rather than assuming every paycheck will match a higher-income period.
TIGHT CASH FLOW
If One Paycheck Has Too Many Bills Attached to It
First determine whether the problem is timing or a broader income shortage. If the month works overall, review bill due dates, automatic payments, and whether part of an earlier paycheck needs to stay reserved.
EARLY-MONTH BILLS
If Large Bills Are Due Before Your First Paycheck of the Month
Do not wait for the calendar to reset before planning them. Part of the final paycheck from the previous month may already need to be assigned to rent, insurance, or another obligation due before the next paycheck arrives.
MORE FINANCIAL MARGIN
If Your Paycheck Budget Already Has Extra Room
Extra room gives you more flexibility, but it still helps to decide what that money is for before it disappears into unplanned spending. Assign the surplus according to the priorities already established in your broader financial plan.
NOT SURE WHICH VERSION FITS?
Start by identifying the pressure point: changing income, crowded due dates, early-month obligations, or simply deciding what to do with extra room. The paycheck-budgeting structure can stay the same while the allocation changes.
FREE VERESTLY TOOL
Build Your Paycheck Budget Around Your Actual Paydays
The Paycheck Budgeting Pro helps you organize each paycheck around the bills, everyday expenses, and upcoming obligations that need to be covered before the next payday arrives.
- ✓ Match bills and recurring obligations to the paycheck that needs to cover them.
- ✓ Estimate how much is available for everyday and flexible spending between paydays.
- ✓ Identify money that needs to stay reserved for an upcoming obligation.
Free · Beginner-friendly · Built for paycheck-based planning
PAYCHECK 1
June 1
Illustrative example
WANT A CALENDAR VIEW?
Use the Paycheck Cash-Flow Calendar to compare paycheck dates with upcoming bills and other planned expenses across the month.
TAKE ACTION
Your Paycheck Budget Action Plan
You do not need to build a perfect system today. Start with the next paycheck, test the plan, and improve it using what actually happens before the following payday.
TODAY
15–20 minutes
Map Your Next Paycheck
Write down your next expected take-home paycheck, the following payday, and the expenses that need to be covered between those two dates.
- Confirm the next payday and expected take-home amount.
- List bills and automatic payments due before the following payday.
- Estimate groceries, transportation, and other routine needs.
- Look ahead for an obligation that may need money reserved now.
THIS PAY PERIOD
Assign before spending
Give the Paycheck a Clear Job
Assign the paycheck before treating the full account balance as available to spend. Cover the current coverage window first, then decide what remains genuinely flexible.
- Fund bills and required obligations in this coverage window.
- Set realistic amounts for everyday spending.
- Reserve money needed for an upcoming obligation.
- Leave margin where your cash flow allows rather than forcing every dollar into immediate spending.
BEFORE NEXT PAYDAY
Review and adjust
Compare the Plan With What Actually Happened
Check whether your estimates matched reality. The purpose is not to judge the pay period—it is to make the next paycheck plan more accurate.
- Check which expenses were higher or lower than expected.
- Note any bill, automatic payment, or routine cost you missed.
- See whether the amount reserved for upcoming obligations was enough.
- Adjust the next coverage window before the next paycheck arrives.
QUICK CHECK
A Workable Paycheck Budget Should Answer One Simple Question
After assigning the paycheck, can you clearly see what must be paid, what needs to remain reserved, and what is actually available to spend before the next payday?
COMMON MISTAKES
Mistakes That Can Break a Paycheck Budget
Most paycheck-budgeting problems come from timing assumptions, missing expenses, or plans that leave too little room for real-life variation. These are the issues to watch for first.
MISTAKE
Treating the Monthly Budget as the Paycheck Plan
A monthly budget may balance overall while still leaving one part of the month short because it does not show which paycheck needs to cover which expenses.
BETTER APPROACH
Keep the monthly budget as the overall plan, then assign each paycheck to its own coverage window.
MISTAKE
Treating the Full Account Balance as Spendable
Money can still be sitting in your account while already being needed for rent, insurance, an automatic payment, or another upcoming obligation.
BETTER APPROACH
Separate money that is genuinely available to spend from money that has already been assigned to a future expense.
MISTAKE
Dividing Every Monthly Expense in Half
Splitting categories evenly between two paychecks can look organized, but it may not reflect when bills actually come due or when everyday spending is needed.
BETTER APPROACH
Let due dates and the length of each coverage window determine the allocation instead of forcing a 50/50 split.
MISTAKE
Forgetting Expenses That Do Not Happen Every Pay Period
Annual fees, maintenance, medical costs, school expenses, and other non-monthly obligations can disrupt a paycheck plan when they are not considered until the payment is close.
BETTER APPROACH
Look ahead for known upcoming costs and account for the portion that affects the current paycheck. Use a dedicated sinking-fund system when you need a longer-term accumulation strategy.
MISTAKE
Assuming the First Paycheck Plan Should Work Perfectly
Your first plan is an estimate. Real spending may reveal a bill that arrives earlier than expected, groceries that cost more than planned, an automatic payment you overlooked, or categories where you actually have more room.
BETTER APPROACH
Review each coverage window before the next payday and use what actually happened to make the next paycheck plan more accurate.
REMEMBER
A good paycheck budget does not predict every dollar perfectly. It gives you enough visibility to see what is already committed, what is actually available, and what needs to change before the next payday.
FREQUENTLY ASKED QUESTIONS
Common Questions About Paycheck Budgeting
These questions cover the situations that most often come up when you start planning around individual paychecks instead of relying only on monthly totals.
Is paycheck budgeting different from monthly budgeting? +
Yes, but the two can work together. A monthly budget shows how your available income is allocated across the month. A paycheck budget adds timing by showing which expenses each paycheck needs to support before the next payday arrives.
The paycheck method is especially useful when income dates and bill due dates do not line up evenly.
What should I do if one paycheck cannot cover everything due before the next one? +
First determine whether the problem is timing or a broader income shortage. If the month works overall, review whether part of an earlier paycheck needs to stay reserved, whether a biller allows a due-date change, or whether flexible spending can be adjusted for that coverage window.
If necessary expenses repeatedly exceed the income available for the month, changing paycheck timing alone will not solve the shortfall.
Learn how cash-flow timing works →How do I budget by paycheck if my income changes every time? +
The paycheck framework can still help, but variable income needs a more flexible planning system. Build the current coverage window from income you can reasonably expect rather than assuming every paycheck will match a higher-income period.
For the full method, use the dedicated irregular-income budgeting guide rather than trying to force a fixed-paycheck structure onto variable income.
Read the irregular-income budgeting guide →Should every dollar in a paycheck be assigned? +
Not necessarily. Some people prefer to assign every dollar, while others intentionally leave some margin for normal variation. Paycheck budgeting does not require one universal allocation rule.
What matters is knowing which money is already committed, which money needs to remain reserved, and what is genuinely available for flexible spending.
What should I do with a third paycheck in a three-paycheck month? +
First confirm what that paycheck still needs to cover. A biweekly payroll calendar does not automatically make the third paycheck completely uncommitted.
If money remains after current and upcoming obligations are accounted for, assign that margin according to the priorities already established in your broader financial plan rather than assuming the full amount is extra spending money.
How often should I update my paycheck budget? +
Review it before each paycheck. You do not need to rebuild the full budget every time, but you should update paycheck amounts, due dates, everyday spending estimates, and known upcoming obligations when something changes.
Periodic monthly reviews can then help you spot patterns across several paycheck cycles.
Learn how to review your budget →KEEP LEARNING
Continue With the Next Most Useful Guides
These guides cover the broader planning skills and adjacent systems that can make paycheck budgeting easier to maintain.
How to Plan a Monthly Budget Before the Month Begins
Build the broader monthly spending plan that your paycheck allocations operate inside.
Read the guide → PLAN FOR FUTURE COSTSHow to Use Sinking Funds
Go deeper on setting money aside gradually for predictable expenses that do not happen every pay period.
Read the guide → IMPROVE THE SYSTEMHow to Review Your Budget at the End of the Month
Use actual spending and cash-flow results to make future budget estimates more accurate.
Read the guide →WANT THE COMPLETE BUDGETING FRAMEWORK?
Return to the main beginner guide for the broader system covering income, expenses, categories, planning, review, and ongoing budget adjustment.
SOURCES & METHODOLOGY
How We Verified This Guide
This guide was reviewed against Consumer Financial Protection Bureau resources on cash-flow budgeting, bill timing, and managing the mismatch between income dates and payment due dates. The examples and Verestly frameworks in this article are educational illustrations, not official CFPB budgeting rules.
LAST REVIEWED
September 2026
Reviewed for source accuracy, cash-flow terminology, budgeting scope, internal-link ownership, and consistency with Verestly's beginner-focused editorial standards.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on practical systems, clear explanations, and actionable financial tools.
View author profile →VERESTLY NEWSLETTER
Get Practical Money Guides and Tools
Join Verestly for beginner-friendly financial education, practical budgeting systems, new tools, and resources designed to make everyday money decisions easier to understand.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED GUIDES
Continue Learning
Explore additional guides that build on paycheck planning, monthly budgeting, budget categories, and ongoing budget review.