BUDGETING · PRACTICAL GUIDE
Best Budget Categories for a Simple Monthly Spending Plan
Learn which budget categories to include in a simple monthly spending plan, how to organize your expenses, and when to add more detail without making your budget harder to maintain.
QUICK ANSWER
The Short Answer
A simple monthly spending plan usually works best when it starts with a small set of broad budget categories that reflect how your household actually uses money. Add more detail only when separating an expense would help you make a better budgeting decision.
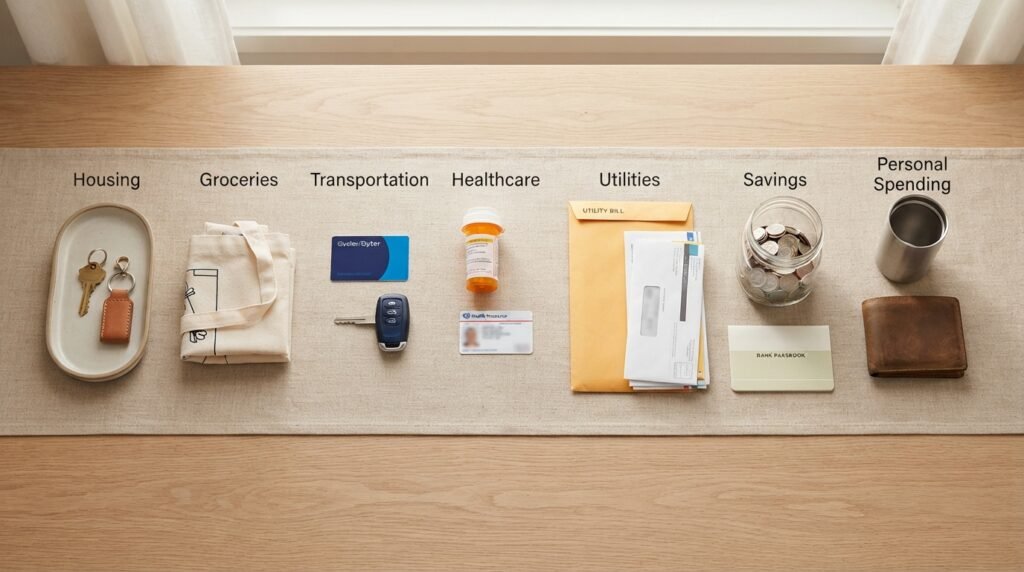
A Practical Starting List
- ✓ Housing, utilities, and communications.
- ✓ Food, transportation, healthcare, and insurance.
- ✓ Debt payments, savings, and future expenses.
- ✓ Personal, household, family, and lifestyle spending.
WHY THIS MATTERS
Why the Right Budget Categories Make Your Spending Plan Easier to Use
Budget categories turn a single monthly spending total into smaller, more useful decisions about where your income needs to go.
A bank balance can tell you how much money is available, but it does not show how much is already needed for housing, groceries, transportation, healthcare, or other priorities.
Categories make those trade-offs visible. They help you compare planned and actual spending, notice where costs are changing, and decide where an adjustment may be needed.
The goal is not to track every purchase in its own category. A useful category system gives you enough detail to make decisions without making the budget difficult to maintain.
PARENT GUIDE Budgeting for Beginners: A Complete Step-by-Step Guide →KEY IDEA
A category should earn its place by helping you make a decision. Split it when more detail changes what you do; combine it when it does not.
BUILD YOUR CATEGORY SYSTEM
How to Choose the Right Budget Categories
Start with broad categories that reflect your real spending, then add detail only where it helps you plan, compare, or adjust your money more clearly.
STEP 1
Start With the Expenses You Already Have
Review your recent spending and identify the major areas where your money consistently goes. These become the foundation of your category system.
Most households will need categories for housing, food, transportation, utilities, healthcare, and other recurring obligations, but your list should reflect your actual circumstances.
PRACTICAL TIP
Do not add a category simply because it appears on someone else's budgeting template. If you do not use it, leave it out.
STEP 2
Group Related Expenses Together
Combine expenses that serve a similar purpose when seeing them together is enough for planning.
- Housing
- Utilities and communications
- Food
- Transportation
- Healthcare
- Personal and household spending
STEP 3
Split Categories Only When the Detail Helps
A category becomes more useful when separating part of it changes the decision you can make.
STEP 4
Include Expenses That Do Not Happen Every Month
Your category system should also account for predictable costs that appear only occasionally. Ignoring them can make an otherwise balanced monthly plan look more reliable than it really is.
- Vehicle registration
- Home or car maintenance
- Annual subscriptions
- School expenses
- Gifts and seasonal costs
STEP 5
Give Financial Priorities Their Own Place
Required debt payments and money assigned to future priorities should remain visible in the monthly spending plan because they reduce the amount available for other categories.
IMPORTANT
The budget should show these allocations, but detailed saving strategies and debt payoff methods belong in their dedicated plans.
STEP 6
Review the Categories After You Use Them
Your first category list does not need to be permanent. After using the budget for a month, review whether the structure is giving you useful information.
- Is one category too broad to explain what happened?
- Are several categories too small to be useful?
- Did recurring expenses keep landing under “Other”?
- Did a missing category make planning harder?
REAL-LIFE EXAMPLE
What a Simple Monthly Category Plan Can Look Like
A category list becomes more useful when you can see how the pieces fit together inside one complete monthly spending plan.
EXAMPLE SCENARIO
A Household Has $4,800 in Monthly Take-Home Income
This household uses broad categories to assign the full $4,800 available for the month. The goal is not to follow a universal percentage rule, but to give each major spending area a clear place in the plan.
| Category | Amount |
|---|---|
| Housing | $1,600 |
| Utilities and communications | $350 |
| Food | $700 |
| Transportation | $550 |
| Healthcare | $200 |
| Insurance | $250 |
| Debt payments | $300 |
| Savings and future expenses | $350 |
| Family, personal, and household | $250 |
| Entertainment and lifestyle | $200 |
| Buffer | $50 |
| Total assigned | $4,800 |
WHAT THIS SHOWS
The Categories Reflect the Household, Not a Universal Formula
The plan uses broad categories for major obligations and everyday spending, while still giving debt payments, future expenses, lifestyle spending, and a small buffer their own place.
Another household with the same income could use a very different allocation because housing costs, childcare, transportation, healthcare, debt, and other priorities can vary substantially.
SIMPLE CHECK
THE TAKEAWAY
Use examples like this for structure, not targets. Your category amounts should reflect your actual income, obligations, priorities, and trade-offs.
This example is illustrative, not a recommended allocation. Your household may need different categories, amounts, or levels of detail.
ADAPT THE CATEGORIES
What Changes If Your Household Needs More Detail?
The basic category structure can stay simple, but some households need more detail in specific areas. Add or split categories where the extra visibility helps you plan more accurately.
IRREGULAR INCOME
If Your Income Changes From Month to Month
Keep essential categories easy to identify so you can see which expenses must be covered first when income is lower than expected. Flexible categories may need wider ranges instead of fixed monthly amounts.
HIGH FIXED COSTS
If Housing or Other Fixed Costs Take Up Most of Your Income
Keep major fixed obligations visible rather than burying them inside broad categories. This makes it easier to see how much income is already committed before flexible spending begins.
FAMILY OR CAREGIVING COSTS
If Childcare, School, or Caregiving Costs Are Significant
Give these expenses their own category when combining them with general household spending would hide an important part of your monthly obligations.
VARIABLE LIFESTYLE SPENDING
If One Flexible Category Keeps Growing
A broad category such as Food or Personal Spending may stop being useful if one part regularly drives the total. Split the category only when the new detail helps you make a clearer trade-off.
NOT SURE WHETHER TO ADD ANOTHER CATEGORY?
Ask whether seeing that spending separately would change a budgeting decision. If the answer is no, keeping the category broader may make the plan easier to maintain.
PRACTICAL VERESTLY RESOURCE
Turn Your Category List Into a Monthly Spending Plan
Once you have chosen your categories, the next step is to assign realistic amounts to them using your actual take-home income, recurring obligations, flexible spending, and future priorities.
- ✓ Start with broad categories instead of tracking every purchase separately.
- ✓ Assign an amount to each category based on your actual monthly cash flow.
- ✓ Review the structure after the month and adjust categories that are not useful.
Beginner-friendly · Flexible · Built around your actual spending
MONTHLY PLAN
Example structure
Illustrative example · Not a recommended allocation
PLAN BEFORE THE MONTH STARTS?
Once your categories are set, organize them into a complete monthly plan before the next month begins.
TAKE ACTION
Your Budget Categories Action Plan
You do not need to design the perfect category system today. Start with a simple structure, use it for real spending, and improve it based on what helps you make better budgeting decisions.
TODAY
15–20 minutes
Build Your First Category List
Review your recent spending and write down the broad categories that reflect where your money actually goes.
- List your major recurring household expenses.
- Add everyday categories such as food and transportation.
- Include debt payments, future expenses, and other priorities.
THIS WEEK
Build the plan
Assign Realistic Amounts to Each Category
Use your actual take-home income and recent spending to decide how much each category needs. The goal is a workable plan, not a set of idealized percentages.
- Fund major obligations before optional spending.
- Use realistic amounts for variable categories.
- Include known nonmonthly expenses in your planning.
- Check that total allocations fit within available income.
END OF THE MONTH
Review and simplify
Check Whether the Categories Were Actually Useful
Compare the category structure with what really happened. The goal is not to judge the month—it is to make the next spending plan easier to understand and adjust.
- Split categories that were too broad to explain your spending.
- Combine categories that added detail without improving decisions.
- Create a category for recurring expenses that kept landing under “Other.”
- Remove categories that you consistently do not use.
QUICK CHECK
A Useful Category System Should Answer One Simple Question
Can you look at your categories and quickly understand where your income is going, what is already committed, and where you still have room to adjust?
COMMON MISTAKES
Budget Category Mistakes That Make a Spending Plan Harder to Use
Most category problems come from either tracking too much detail, hiding too much spending inside broad buckets, or forgetting expenses that still need room in the plan.
MISTAKE
Creating Too Many Categories at Once
A highly detailed budget may look organized, but dozens of categories can make tracking and reviewing the plan unnecessarily difficult.
BETTER APPROACH
Start with broad categories and split them only when the extra detail helps you make a clearer decision.
MISTAKE
Hiding Too Much Under “Other”
A catch-all category can be useful for occasional expenses, but it becomes less informative when the same types of spending keep appearing there month after month.
BETTER APPROACH
If the same expense repeatedly lands under “Other,” consider creating a dedicated category for it.
MISTAKE
Forgetting Irregular Expenses
Annual fees, vehicle registration, repairs, school costs, medical expenses, gifts, and seasonal spending may not occur every month, but they still affect the budget when they arrive.
BETTER APPROACH
Keep predictable nonmonthly expenses visible in the category they belong to and plan ahead for when they are due.
MISTAKE
Forcing Every Category Into a Percentage Target
Percentage frameworks can be useful references, but housing, transportation, healthcare, childcare, and other costs vary substantially between households.
BETTER APPROACH
Use your actual income, obligations, priorities, and trade-offs to set category amounts rather than forcing every expense into a universal split.
MISTAKE
Treating the First Category List as Permanent
Your spending plan changes as your life changes. A new job, move, child, vehicle, healthcare expense, subscription, or shift in income can make an old category structure less useful.
BETTER APPROACH
Review the category structure regularly and split, combine, add, or remove categories when doing so makes the plan easier to understand and adjust.
REMEMBER
The best category system is not the one with the most detail. It is the one that gives you enough visibility to understand your spending, make trade-offs, and adjust the plan when needed.
FREQUENTLY ASKED QUESTIONS
Common Questions About Budget Categories
These questions cover the decisions that most often come up when someone is choosing, organizing, or simplifying categories for a monthly spending plan.
How many budget categories should I have? +
There is no universal number. Start with broad categories that cover your main obligations, everyday spending, financial priorities, and recurring household needs.
Add more detail only when separating an expense helps you make a clearer budgeting decision.
Should groceries and dining out be separate categories? +
They can be. Separating groceries and dining out can help when you want to make different decisions about those two types of food spending.
If the distinction does not change how you plan or adjust your budget, keeping one broader Food category may be simpler.
Is savings a budget category? +
It can be. Money assigned to future priorities reduces the amount available for current spending, so including that allocation in your monthly plan can make your cash flow clearer.
The detailed strategy for emergency savings, sinking funds, or other savings goals belongs in the relevant savings plan.
Should debt payments be included in a budget category? +
Required debt payments should generally remain visible in the monthly spending plan because they use part of your available cash flow.
Detailed decisions about repayment order, acceleration, or consolidation belong in a separate debt strategy.
Where do annual bills go in a monthly budget? +
Keep annual or occasional bills connected to the category they belong to instead of ignoring them until they are due. For example, vehicle registration can remain part of Transportation, while an annual insurance premium can remain under Insurance.
Larger predictable future expenses may also be easier to manage with a dedicated sinking-fund strategy.
Learn how sinking funds work →Should I use percentages for every budget category? +
Not necessarily. Percentage frameworks can provide a useful reference point, but housing, transportation, healthcare, childcare, debt, and other costs vary between households.
Your actual income, fixed obligations, priorities, and trade-offs matter more than forcing every category into one predetermined percentage.
See how the 50/30/20 framework works →KEEP LEARNING
Continue With the Next Most Useful Guides
These guides help turn your category structure into a complete, workable monthly budgeting system.
How to Create a Beginner Budget You’ll Actually Use
Turn your category list into a complete spending plan based on your actual income and expenses.
Read the guide → PLAN AHEADHow to Plan a Monthly Budget Before the Month Begins
Assign amounts to your categories before the month starts and adjust the plan around upcoming obligations.
Read the guide → EXPLORE A FRAMEWORKThe 50/30/20 Budget Rule: Does It Really Work?
See how a broad percentage framework organizes spending and where it may need to be adapted.
Read the guide →WANT THE COMPLETE SYSTEM?
Return to the main budgeting guide for the broader beginner framework covering income, expenses, planning, trade-offs, and ongoing budget management.
SOURCES & METHODOLOGY
How We Verified This Guide
Verestly prioritizes primary government sources and other authoritative references. For this guide, we used official household-budgeting materials and expenditure data to verify common spending categories, household-cost context, and the role of irregular expenses in a monthly plan.
LAST REVIEWED
September 2026
This guide was reviewed for accuracy, search-intent ownership, source quality, practical usefulness, and consistency with Verestly's budgeting methodology.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on practical systems, clear explanations, flexible budgeting, and actionable financial tools.
View author profile →VERESTLY NEWSLETTER
Get Practical Money Guides and Tools
Join Verestly for beginner-friendly financial education, practical budgeting systems, new tools, and resources designed to make everyday money decisions easier to manage.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED GUIDES
Continue Learning
Explore three additional guides that help you turn your budget categories into a practical monthly spending plan.