BUDGETING · PRACTICAL GUIDE
How to Use Sinking Funds in Your Monthly Budget
Learn how to turn predictable future expenses into manageable monthly allocations, calculate sinking fund contributions, and adjust them as your priorities and cash flow change.
QUICK ANSWER
The Short Answer
Using sinking funds in your monthly budget means setting aside money now for future expenses you can reasonably anticipate. Instead of letting an annual, seasonal, or irregular cost hit one month all at once, you divide it into smaller planned contributions and include those amounts in your budget.
What You'll Do
- ✓ Identify future expenses that are predictable enough to plan for.
- ✓ Estimate the amount needed and when the expense is likely to occur.
- ✓ Turn each future cost into a realistic monthly contribution.
- ✓ Review and adjust those contributions as your budget changes.
WHY THIS MATTERS
Why Irregular Expenses Can Disrupt an Otherwise Balanced Budget
A monthly budget can cover your regular bills and still get thrown off by annual, seasonal, or occasional expenses that were predictable but never assigned a place in the plan.
Many expenses do not arrive every month. Vehicle registration, annual memberships, holiday spending, school costs, planned maintenance, and other irregular expenses may appear only a few times a year.
If your budget focuses only on this month's bills, those future costs can look like surprises even when you knew they were eventually coming.
Sinking funds help solve that problem by spreading a future cost across several months and making the contribution part of your regular monthly allocation.
PARENT GUIDE Budgeting for Beginners: A Complete Step-by-Step Guide →KEY IDEA
A sinking fund turns a larger future expense into a series of planned monthly allocations before the cost arrives.
STEP-BY-STEP METHOD
How to Add Sinking Funds to Your Monthly Budget
The goal is to turn larger future expenses into smaller, manageable allocations before those costs arrive. Start with the expenses you can reasonably anticipate, then build each contribution into the monthly plan.
STEP 1
Identify the Expenses You Can See Coming
Start with costs that do not happen every month but are predictable enough that you know they are likely to occur.
- Vehicle registration or maintenance
- Annual or semiannual insurance premiums
- Holiday and gift spending
- School or seasonal expenses
- Planned travel
- Home or pet maintenance
PRACTICAL TIP
Review several months of past spending to find irregular expenses that may be easy to miss when you look at only one month.
STEP 2
Estimate the Amount and Target Date
For each expense, estimate how much you expect to need and approximately when you will need the money.
Some amounts will be exact, such as a known annual fee. Others will be estimates based on previous costs, upcoming plans, or current prices.
GO DEEPER Learn how to plan your budget before the month begins →STEP 3
Calculate a Monthly Contribution
Subtract anything you have already saved from the target amount, then divide the remaining amount by the number of months left before the expense is expected.
STEP 4
Add the Contribution to Your Monthly Budget
Treat the sinking fund contribution as a planned allocation when you build the month's budget instead of waiting to see what money happens to be left over.
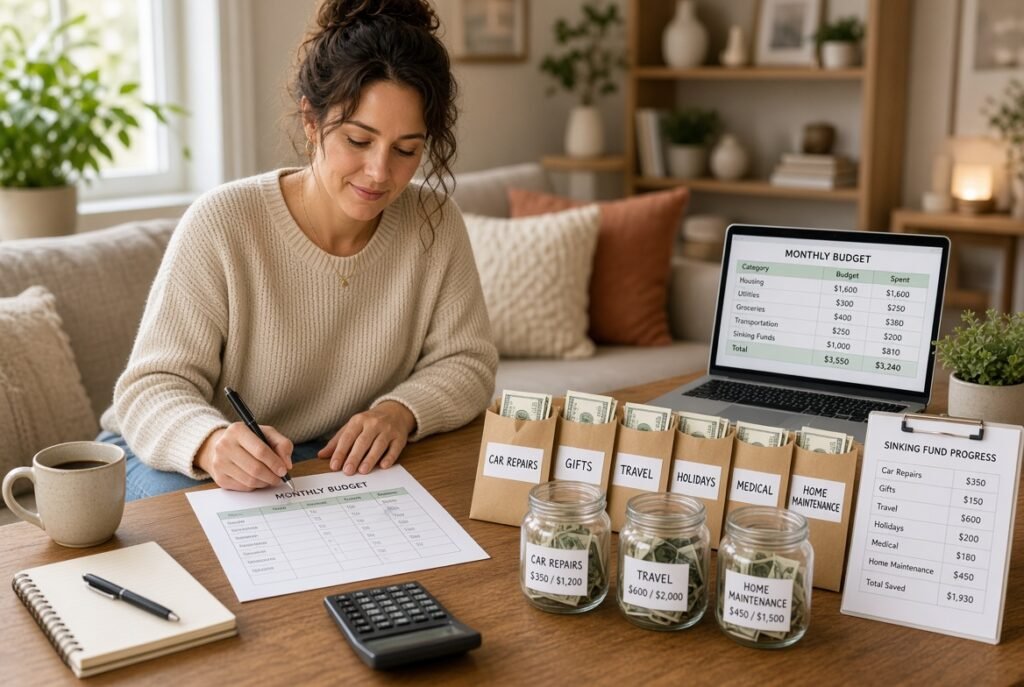
You can show one broader future-expenses category or list individual sinking funds separately. The important part is making the allocation visible.
GO DEEPER See how to organize your monthly budget categories →STEP 5
Prioritize When the Ideal Amount Does Not Fit
If funding every sinking fund at the ideal pace would exceed the money available in your budget, prioritize instead of pretending every goal can be fully funded at once.
- Which expense is due soonest?
- Which expense is necessary rather than optional?
- What happens if the money is not ready in time?
- Can the amount or timing reasonably change?
IMPORTANT
A sinking fund should support your cash flow, not make essential monthly expenses harder to cover. If the ideal contribution does not fit, adjust the plan.
STEP 6
Review, Spend, and Rebuild as Needed
Review your sinking funds along with the rest of your budget. Update contributions when costs, deadlines, income, or priorities change.
When the planned expense arrives, use the money for its intended purpose. If the expense will happen again, estimate the next target and begin rebuilding the fund.
- Did you make the planned contribution?
- Has the expected cost changed?
- Is the deadline still realistic?
- Does the contribution still fit your cash flow?
REAL-LIFE EXAMPLE
What Sinking Funds Can Look Like in a Monthly Budget
A simple example shows how several future expenses can be turned into manageable monthly contributions instead of large one-time hits to the budget.
EXAMPLE SCENARIO
Maya Has Three Predictable Expenses Coming Up
Maya expects to need $480 for vehicle registration and maintenance, $600 for holiday spending, and $300 for annual pet care. Instead of waiting until those costs arrive, she begins setting aside money for them each month.
| Future Expense | Monthly Amount |
|---|---|
| Vehicle registration and maintenance | $60 |
| Holiday spending | $60 |
| Annual pet care | $50 |
| Total monthly allocation | $170 |
| Amount still available for other budget categories | Varies |
WHAT THIS SHOWS
Maya Turns Three Future Costs Into One Monthly Commitment
Instead of asking one future month to absorb several large expenses, Maya gives those costs a place in the budget now. The total monthly contribution is $170, split across three separate purposes.
The amounts are based on the expected cost and time remaining. If one target changes, Maya can adjust that individual contribution without rebuilding the entire budget.
SIMPLE MATH
THE TAKEAWAY
Sinking funds make future expenses easier to manage by converting them into planned monthly allocations before the bills or purchases arrive.
This example is illustrative, not a recommended allocation. Your sinking fund amounts should reflect your own expenses, deadlines, available income, and priorities.
ADAPT THE METHOD
What Changes If Your Budget Has Different Constraints?
The basic sinking fund process stays the same, but the amount you contribute and the order you prioritize funds may need to change with your income, deadlines, and available monthly margin.
IRREGULAR INCOME
If Your Income Changes From Month to Month
Keep the sinking fund targets visible, but allow the actual contribution to change with available income. Lower-income months may require smaller contributions, while stronger months can help you catch up on higher-priority funds.
TIGHT CASH FLOW
If You Cannot Fully Fund Every Sinking Fund
Do not force every target to stay on its ideal schedule. Compare urgency, necessity, deadline, and consequences, then direct available money toward the funds that matter most now.
SHORT DEADLINE
If the Expense Is Coming Up Soon
A short deadline can make the ideal monthly contribution much larger. Recalculate what is still needed, then decide whether the target amount, timing, or another flexible budget category can reasonably change.
MORE FINANCIAL MARGIN
If Your Budget Has More Room Than Expected
Extra margin can be used to strengthen an underfunded sinking fund, prepare earlier for another predictable expense, or stay available for other priorities. The key is assigning that money intentionally instead of assuming every fund must grow.
NOT SURE WHAT TO PRIORITIZE?
Start with the future expenses that are both necessary and approaching soon. Your sinking fund plan can change as deadlines, income, and available cash flow change.
FREE VERESTLY TOOL
Calculate a Monthly Sinking Fund Contribution
Use the Sinking Fund Calculator to turn a future expense into a monthly contribution based on your target amount, what you have already set aside, and the time remaining before you expect to need the money.
- ✓ Enter the total amount you expect the future expense to cost.
- ✓ Account for money you have already set aside.
- ✓ See the monthly contribution needed to work toward the target.
Free · Beginner-friendly · Built for future-expense planning
SINKING FUND
Vehicle Maintenance
Illustrative example
PLANNING THE FULL MONTH?
See how sinking fund contributions can sit alongside bills, everyday spending, and other priorities in your monthly plan.
TAKE ACTION
Your Sinking Fund Action Plan
You do not need to build every sinking fund at once. Start with the future expenses that matter most, calculate realistic monthly contributions, and adjust them as your budget changes.
TODAY
15–20 minutes
List the Future Expenses You Can Predict
Write down the irregular expenses you reasonably expect over the coming months and identify which ones would be difficult to absorb from a single monthly budget.
- Review annual, seasonal, and occasional expenses.
- Estimate the amount you may need for each one.
- Note when each expense is likely to occur.
THIS WEEK
Build the plan
Turn the Priorities Into Monthly Contributions
Calculate how much would need to be set aside each month, then compare the total with the money actually available in your current budget.
- Subtract anything you have already set aside.
- Divide the remaining amount by the months left.
- Prioritize necessary or time-sensitive expenses first.
- Reduce contributions that do not fit your available cash flow.
NEXT BUDGET REVIEW
Review and adjust
Check Whether the Plan Still Fits
Review your sinking funds with the rest of your monthly budget. The goal is not to keep the original contribution forever—it is to keep the plan aligned with real costs, deadlines, and cash flow.
- Confirm whether each expected cost has changed.
- Check whether each deadline is still realistic.
- Look for new predictable expenses that need attention.
- Adjust contributions before the next budget period begins.
QUICK CHECK
A Workable Sinking Fund Plan Should Answer One Simple Question
After adding the contributions to your monthly budget, can you still cover higher-priority obligations without relying on money already reserved for those future expenses?
COMMON MISTAKES
Mistakes That Can Make Sinking Funds Harder to Maintain
Sinking funds are meant to make future expenses easier to manage. A few common planning mistakes can make them feel more complicated, restrictive, or unreliable than they need to be.
MISTAKE
Creating Too Many Sinking Funds at Once
A long list of small contributions can add up quickly and consume more of your monthly income than expected. It can also make the system harder to track.
BETTER APPROACH
Start with the future expenses that are most necessary, predictable, or time-sensitive, then add others only when your budget has room.
MISTAKE
Forgetting the Deadline
A target amount by itself does not tell you whether the monthly contribution is realistic. A $1,200 expense due in twelve months requires a very different plan from the same expense due in three.
BETTER APPROACH
Pair every target amount with an approximate due date and recalculate the contribution when the timing changes.
MISTAKE
Treating Sinking Funds as Whatever Is Left Over
If contributions depend entirely on leftover money at the end of the month, predictable expenses may remain underfunded until the deadline is close.
BETTER APPROACH
Include sinking fund contributions when you build the monthly spending plan, then adjust them if your available cash flow cannot support the original amount.
MISTAKE
Counting the Same Money as Emergency Savings
Money already reserved for a known future expense has a job. Treating those same dollars as part of your emergency cushion can make your available reserves look larger than they really are.
BETTER APPROACH
Keep the purpose of each allocation clear. Sinking funds prepare for anticipated expenses; emergency savings serve a different role.
MISTAKE
Treating the First Contribution Amount as Permanent
Target costs, deadlines, income, and other priorities can all change. A contribution that made sense three months ago may no longer fit the current budget.
BETTER APPROACH
Review sinking funds along with the rest of your budget and change the contribution when better information or new cash-flow constraints appear.
REMEMBER
A useful sinking fund plan is not the one with the most categories or the most aggressive contributions. It is the one that prepares for important future expenses while still fitting the income and obligations you have today.
FREQUENTLY ASKED QUESTIONS
Common Questions About Sinking Funds
These questions cover the issues that most often come up when sinking funds are added to a monthly budget.
Should sinking funds be included in my monthly budget? +
Yes. If you plan to contribute to a sinking fund during the month, that contribution should appear somewhere in your spending plan so it competes for income alongside your other priorities.
You can group several sinking funds under one broader category or list them separately. The important part is making the allocation visible.
How much should I put into sinking funds each month? +
There is no universal amount. A practical starting point is to subtract anything already saved from the expected cost, then divide the remaining amount by the number of months before you expect to need the money.
If that contribution does not fit your current cash flow, adjust the amount, deadline, target, or priority rather than forcing the budget to support an unrealistic number.
How many sinking funds should I have? +
There is no ideal number for every household. Use enough sinking funds to make important future expenses visible without creating a system that becomes difficult to track or consumes too much of your monthly income.
Starting with the most necessary or time-sensitive expenses is often more useful than creating a category for every possible future cost.
Is a sinking fund the same as an emergency fund? +
No. A sinking fund is generally for an expense you can reasonably anticipate, such as vehicle registration, holiday spending, or planned maintenance.
Emergency savings are intended for genuinely unplanned financial shocks. Some expenses fall into a gray area, but keeping the purposes separate helps prevent the same money from being counted twice.
Do sinking funds need separate bank accounts? +
Not necessarily. You can track sinking funds through budget categories, subaccounts, savings buckets, a spreadsheet, or another system that keeps each purpose identifiable.
From a budgeting perspective, the key issue is being able to see how much has been reserved for each future expense and avoid spending that money elsewhere.
What happens after I use the money in a sinking fund? +
If the expense was one-time, the monthly allocation can be redirected to another priority. If the expense will happen again, estimate the next target amount and date and begin another funding cycle.
Spending the money for its intended purpose is not a failure. That is exactly what the sinking fund was created to do.
KEEP LEARNING
Continue With the Next Most Useful Guides
These guides help you connect sinking funds to the broader budgeting system without turning this article into a guide about every budgeting method.
How to Plan a Monthly Budget Before the Month Begins
Build the broader monthly plan where sinking fund contributions will sit alongside bills and spending.
Read the guide → ORGANIZE YOUR PLANBest Budget Categories for a Simple Monthly Spending Plan
Decide where future-expense allocations fit within a clear and manageable category structure.
Read the guide → HANDLE VARIABLE INCOMEHow to Budget With Irregular Income
Learn how to keep future expenses visible when the amount available to fund them changes from month to month.
Read the guide →WANT THE COMPLETE SYSTEM?
Return to the main budgeting guide for the broader beginner framework covering income, expenses, category planning, priorities, and ongoing budget management.
SOURCES & METHODOLOGY
How We Verified This Guide
This guide was reviewed against primary U.S. government sources covering household budgeting, regular savings, less-frequent expenses, automatic transfers, and financial resilience. Examples and planning frameworks in the article are educational illustrations rather than universal rules.
LAST REVIEWED
September 2026
This guide was reviewed for budgeting accuracy, source quality, search-intent ownership, and clear separation between sinking funds and emergency savings.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on practical systems, clear explanations, and actionable financial tools.
View author profile →VERESTLY NEWSLETTER
Get Practical Money Guides and Tools
Join Verestly for beginner-friendly financial education, new tools, practical systems, and resources you can actually use.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED GUIDES
Continue Learning
Explore three additional guides selected to help you connect sinking funds with monthly planning, budget categories, and changing income.