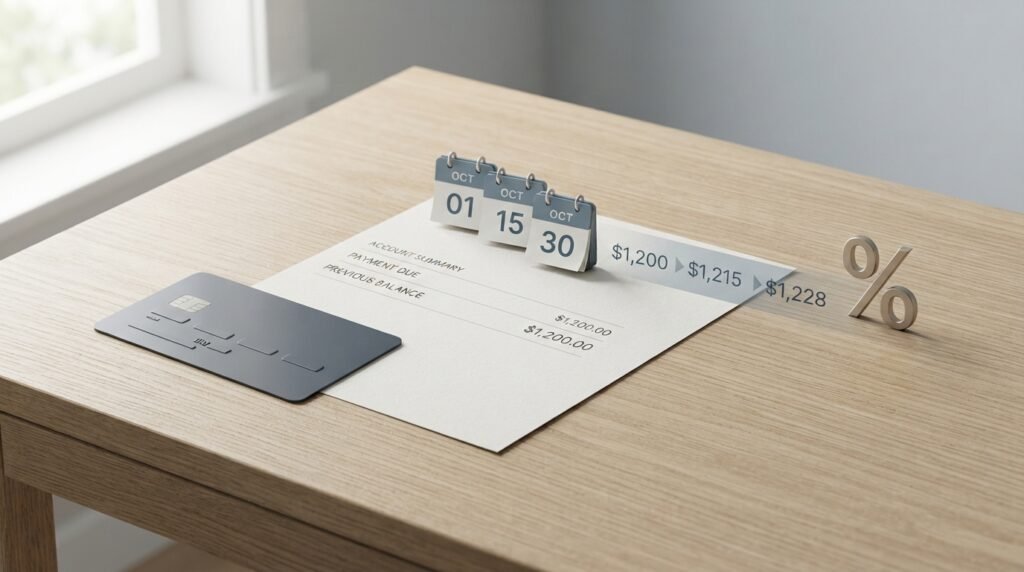
CREDIT & CREDIT CARDS · BEGINNER GUIDE
What Is Credit Utilization and How Does It Work?
Learn what credit utilization means, how to calculate it, why reported balances and credit limits matter, and how utilization can affect your credit scores.
QUICK ANSWER
The Short Answer
Credit utilization is the percentage of your available revolving credit that is currently being used. It is usually calculated by dividing a reported credit card balance by the card's credit limit. Credit scoring models may consider both your overall utilization and the utilization on individual accounts, although the exact impact can vary by scoring model and credit profile.
What You'll Learn
- ✓ How credit utilization is calculated using balances and credit limits.
- ✓ The difference between individual-card and overall utilization.
- ✓ Why reported balances can differ from the balance you see today.
- ✓ Why the commonly cited 30% figure is a guideline, not a guaranteed scoring cutoff.
- ✓ How to manage utilization without carrying a balance or paying interest unnecessarily.
UNDERSTAND THE BASICS
What Is Credit Utilization?
Credit utilization shows how much of your available revolving credit is being used. It is usually expressed as a percentage and is based on the relationship between a reported balance and the credit limit available on an account.
Start with your credit limit
Your credit limit is the maximum amount of revolving credit the card issuer currently allows you to use on the account. It provides the available-credit side of the utilization calculation.
Compare it with the reported balance
The other side of the calculation is the balance reported for the account. That amount may differ from the balance you see in your card app today because creditors report account information periodically.
Turn the relationship into a percentage
If a card has a $4,000 credit limit and a $1,000 reported balance, you are using one-quarter of the available credit. That equals 25% credit utilization.
Remember that utilization focuses on revolving credit
Credit utilization most commonly applies to revolving accounts such as credit cards. It is different from simply measuring how much total debt you owe across every type of credit account.
Credit and debt are related, but they are not the same. Credit is access to borrowed money or financing, while debt is money you currently owe. Credit utilization compares the amount of applicable revolving credit being used with the amount available.
DO THE MATH
How to Calculate Credit Utilization
Credit utilization compares a reported revolving balance with the credit limit available on the account. The calculation is simple: divide the reported balance by the credit limit, then multiply the result by 100 to express it as a percentage.
Find the Reported Balance
Identify the balance being reported for the revolving account.
Find the Credit Limit
Check the current credit limit associated with that account.
Divide Balance by Limit
Divide the reported balance by the available credit limit.
Convert It to a Percentage
Multiply the result by 100 to get the utilization percentage.
Read the Result in Context
Remember that the percentage can change as reported balances or credit limits change.
A simple example
Suppose a credit card has a $6,000 credit limit and a $1,500 reported balance.
Divide $1,500 by $6,000:
$1,500 ÷ $6,000 = 0.25
Multiply 0.25 by 100:
0.25 × 100 = 25%
In this example, the card's credit utilization is 25%.
THE FORMULA
Reported balance ÷ credit limit × 100 = credit utilization percentage.
The same balance can produce a very different ratio
A $1,000 balance on a card with a $2,000 limit represents 50% utilization. The same $1,000 balance on a card with a $10,000 limit represents only 10% utilization.
The amount owed has not changed, but the relationship between the balance and available revolving credit has. That is why credit utilization is different from simply measuring how many dollars you owe.
LOOK AT BOTH LEVELS
Individual vs. Overall Credit Utilization
Credit utilization can be viewed in two ways: how much of the limit you are using on each individual credit card and how much of your total available revolving credit you are using across multiple cards. Those percentages can look very different.
ACCOUNT LEVEL
Individual Utilization Looks at One Card at a Time
Individual-card utilization compares the reported balance on a single revolving account with the credit limit on that same account.
Suppose one credit card has a $1,000 credit limit and a $900 reported balance. The calculation is:
KEY IDEA
Each revolving account can have its own utilization percentage, even when your overall utilization is much lower.
TOTAL PICTURE
Overall Utilization Combines Your Revolving Accounts
Overall credit utilization compares the combined reported balances on applicable revolving accounts with their combined credit limits.
Imagine you have two credit cards:
Your overall utilization in this example is 10%, even though one individual card is using 90% of its available limit.
READ THE FULL PICTURE
Why Both Percentages Matter
A low overall utilization percentage does not automatically mean every individual account has low utilization. One card can be close to its limit while your combined percentage remains relatively low because other cards have much larger unused limits.
Credit scoring models may consider information about both overall revolving utilization and utilization on individual accounts. The exact effect can vary by scoring model and by the rest of the information in your credit file.
- Check the utilization percentage on each individual card.
- Also calculate your combined revolving utilization.
- Do not assume a low overall percentage makes a nearly maxed-out individual card irrelevant.
- Avoid treating either percentage as a guaranteed predictor of a specific credit score.
SIMPLE WAY TO REMEMBER IT
Individual utilization shows what is happening on one account. Overall utilization shows what is happening across your revolving credit as a whole.
FOLLOW THE REPORTING FLOW
Which Balance Is Used for Credit Utilization?
Credit utilization is generally based on the balance that appears in your credit-report data when a score is calculated. That number may be different from the balance you see in your credit card app today because card issuers report account information periodically.
Your Balance Changes
Purchases, payments, credits, fees, and other account activity can change the balance you see during the billing cycle.
Your Billing Cycle Ends
At the end of a billing cycle, the issuer generates a statement. The statement balance reflects what was owed when that cycle closed.
Account Information Is Reported
Credit card issuers periodically send account information to credit reporting companies. The balance reported can often reflect recent statement information, although reporting practices can vary by issuer.
Your Current Balance May Change Again
You may make a payment or new purchase after information has already been reported. Your current account balance can therefore differ from the balance still appearing on your credit report.
Utilization Changes When New Data Is Reported
When updated balance or credit-limit information reaches your credit reports, the utilization calculation can change again.
THREE BALANCES TO KNOW
Current balance is what your account shows you owe right now. Statement balance is the amount shown when your latest billing cycle closed. Reported balance is the amount most recently supplied to the credit reporting company. These numbers do not always match.
SEE IT IN PRACTICE
How Credit Utilization Can Affect Credit Scores
Credit scoring models may consider how much of your available revolving credit is being used. The example below shows how a change in reported balances can change utilization without assuming or predicting a specific credit-score increase.
STARTING POINT
Meet Taylor
Taylor has two credit cards with a combined credit limit of $10,000. After several larger purchases, the combined reported balances reach $5,000.
Taylor has not missed a payment, but the higher reported balances mean more of the available revolving credit is currently being used.
| Card A credit limit | $4,000 |
|---|---|
| Card A reported balance | $2,800 |
| Card A utilization | 70% |
| Card B credit limit | $6,000 |
| Card B reported balance | $2,200 |
| Card B utilization | 36.7% |
| Overall utilization | 50% |
FOLLOW THE CHANGE
What Happens When the Reported Balances Fall?
REPORT
Higher Balances Are Reported
With $5,000 in combined reported balances and $10,000 in combined limits, Taylor's overall utilization is 50%.
PAY
Taylor Pays Down the Balances
Taylor pays the combined card balances down from $5,000 to $1,500 while the total credit limits remain unchanged.
UPDATE
Lower Balances Are Reported
Once the lower balances are reflected in the credit report data, the utilization calculation can change to reflect the updated amounts.
RECALCULATE
Overall Utilization Falls to 15%
With $1,500 in reported balances and the same $10,000 in available revolving credit, Taylor's overall utilization becomes 15%.
SCORE
The Credit-Score Input Has Changed
A scoring model that considers revolving utilization now has different balance-to-limit information to evaluate. The actual score effect, however, can vary by scoring model and by the rest of Taylor's credit file.
THE TAKEAWAY
Utilization Is One Credit-Score Factor, Not the Whole Score
Lower reported revolving balances can reduce utilization when credit limits stay the same, but that does not translate into a guaranteed number of credit-score points. Credit scores can also reflect payment history, account age, recent credit activity, account types, derogatory information, and other data in the credit report.
This example is illustrative and does not predict a specific credit-score outcome. Different scoring models and lenders may evaluate credit-report information differently.
INTERPRET THE PERCENTAGE
What Is a Good Credit Utilization Rate?
There is no single utilization percentage that guarantees a particular credit score. Lower utilization is generally viewed more favorably than using a large share of your available revolving credit, but the exact effect can vary by scoring model and by the rest of your credit profile.
IF YOUR UTILIZATION IS LOW
You are using a small share of your available credit
Lower utilization generally means your reported revolving balances are small relative to your available limits. That can be favorable in many credit-scoring contexts, but there is no universal percentage that guarantees a specific score outcome.
IF YOU ARE NEAR 30%
Treat 30% as a guideline, not a scoring cutoff
The 30% figure is commonly used in consumer credit guidance, but it is not a universal threshold where your score suddenly changes. Moving from 29% to 31%, for example, does not create a predetermined score result.
IF UTILIZATION IS HIGH
A large share of your available credit is being used
Higher utilization means your reported balances are closer to your available revolving limits. Scoring models may view heavy use of available credit differently from lower use, although the precise impact cannot be predicted from the utilization percentage alone.
IF YOUR REPORTED UTILIZATION IS 0%
Do not take on debt just to create a utilization percentage
A 0% reported utilization rate is not a reason to spend unnecessarily or carry an interest-bearing balance. Some scoring models may distinguish between no recently reported revolving usage and a small reported balance, but that does not make paying interest necessary to build credit.
THE BETTER RULE OF THUMB
Think Lower, Not “Perfect”
Instead of trying to hit one exact percentage, focus on avoiding heavy reliance on your revolving limits, paying bills on time, and keeping balances at levels that are manageable for your finances. Utilization is only one part of a broader credit profile.
Practical · Beginner-friendly · No score promises
PRACTICAL CREDIT HABITS
How to Manage Credit Utilization in Practice
Managing utilization does not require chasing a perfect percentage. The goal is to keep revolving balances manageable, understand what is being reported, and avoid using more credit than your finances can comfortably support.
- ✓ Know the credit limits on your revolving accounts.
- ✓ Monitor balances during the billing cycle instead of checking only at the due date.
- ✓ Pay balances down when practical without carrying debt just to create credit activity.
- ✓ Remember that a higher credit limit is not extra income or permission to increase spending.
Practical · Beginner-friendly · No score promises
START HERE
What should you check when utilization starts rising?
IMPORTANT TO REMEMBER
You do not need to carry a balance or pay interest to build credit. Responsible card use can include paying your statement balance in full while still having account activity reported.
CLEAR UP THE CONFUSION
Common Credit Utilization Myths
Credit utilization is surrounded by shortcuts, rules of thumb, and advice that can sound more precise than it really is. Use the points below to separate useful guidance from common misconceptions.
MYTH
Carrying a balance builds creditYou Do Not Need to Carry Debt to Build Credit
Leaving part of a balance unpaid from one billing cycle to the next is not required to create positive credit history. You can use a credit card, allow account activity to be reported, and still pay the statement balance in full.
- Reported card activity does not require revolving debt.
- Paying interest is not a credit-building requirement.
- Paying on time remains more important than creating debt intentionally.
MYTH
30% is the perfect numberThere Is No Universal Perfect Utilization Rate
The commonly cited 30% figure is a practical guideline, not a universal scoring rule. A move from 29% to 31% does not trigger a predetermined score change, and no single percentage guarantees a particular outcome.
- Treat 30% as guidance, not a hard cutoff.
- Lower utilization can generally be more favorable.
- Different scoring models may weigh utilization differently.
MYTH
Only overall utilization mattersIndividual Card Utilization Can Matter Too
A low combined utilization percentage does not mean every account has low utilization. One card can be close to its limit while the total across all cards remains relatively low.
- Review utilization on each individual revolving account.
- Also review your combined revolving utilization.
- Do not rely on the aggregate number alone.
MYTH
Paying in full always means 0%Your Reported Balance May Still Be Above Zero
Paying your statement balance in full does not always mean your credit report will immediately show a zero balance. Reporting timing can cause a previously reported balance to remain visible until the issuer sends updated information.
- Current balance and reported balance can differ.
- Statement timing can affect what appears on your report.
- A reported balance does not automatically mean you are carrying debt.
MYTH
Closing an unused card always helpsClosing a Card Can Change the Utilization Math
Closing a revolving account can reduce the amount of available credit included in the utilization calculation. If your other reported balances stay the same, that can cause the percentage to rise.
- A lower total credit limit can raise utilization.
- Your debt does not have to increase for the ratio to rise.
- Whether to close a card depends on more than utilization alone.
KEEP THE BIG PICTURE IN MIND
Use Credit Responsibly Instead of Chasing Score Tricks
Utilization is one factor that can influence credit scores, but it should not become the only number you manage. Focus on paying on time, keeping balances manageable, understanding what is being reported, and avoiding unnecessary interest.
AVOID THESE PITFALLS
Common Credit Utilization Mistakes to Avoid
Credit utilization is simple to calculate, but it is easy to misread what the percentage means or make decisions based on incomplete information. These are some of the most common mistakes to watch for.
Treating 30% as a Hard Scoring Cutoff
The commonly cited 30% figure can be useful as a general guideline, but it is not a universal threshold that guarantees a particular credit-score outcome.
Think of utilization as a range rather than a magic number, and remember that lower usage can generally be more favorable than heavy use of available credit.
Looking Only at Overall Utilization
A low combined utilization ratio can hide a single credit card that is using a large share of its own limit.
Review both your total revolving utilization and the utilization on each individual card.
Confusing Current Balance With Reported Balance
The balance you see in your card app today may not be the same balance currently appearing on your credit report.
Understand the difference between current balance, statement balance, and reported balance before trying to interpret changes in utilization.
Carrying a Balance to “Build Credit”
Leaving debt unpaid from one billing cycle to the next is not required to create credit history and can result in unnecessary interest charges.
Use credit responsibly and pay according to your account terms. You do not need to intentionally revolve debt to build credit.
Spending More Because Your Limit Increased
A larger credit limit can reduce utilization when the balance stays the same, but it does not increase your income or make additional spending easier to afford.
Treat available credit as borrowing capacity, not as money available for additional spending.
Making Major Account Decisions for Utilization Alone
Opening a new card, requesting a higher limit, or keeping an account open solely to change utilization can affect other parts of your credit and financial life.
Consider utilization as one factor alongside fees, borrowing needs, spending behavior, account age, credit inquiries, and your broader financial goals.
FREQUENTLY ASKED QUESTIONS
Credit Utilization Questions Beginners Often Ask
These short answers cover common questions about balances, credit limits, reporting timing, and how utilization can interact with credit scores.
Does credit utilization include installment loans?
Credit utilization usually refers to revolving credit, especially credit cards. Installment loans such as auto loans and mortgages can affect credit scores in other ways, but they are not normally part of the standard credit-card utilization calculation.
How often does credit utilization change?
Utilization can change whenever new balance or credit-limit information is reported. Creditors usually update account information periodically rather than continuously.
Review how balance reporting works →Can utilization change even if I make no new purchases?
Yes. A payment, credit-limit change, account closure, adjustment, or newly reported information can change the balance-to-limit calculation even when you have not made another purchase.
Can paying before my statement closes lower utilization?
It can result in a lower reported balance in some situations, depending on when and what your card issuer reports. Reporting schedules vary, so there is no single payment date that works the same way for every account.
Is 0% credit utilization bad?
A 0% reported utilization rate is not a reason to take on debt. Some scoring models may distinguish between no recently reported revolving usage and a small amount of reported activity, but you should not spend unnecessarily or pay interest simply to create a balance.
Does credit utilization have a memory?
It depends on the scoring model. Some commonly used models place substantial weight on current reported balances, while newer scoring approaches can also consider trends in balance and utilization data over time. Because lenders can use different models, consistent credit management is more useful than relying on a temporary score-optimization tactic.
Should I open another card just to lower utilization?
Not automatically. Opening another account can affect other parts of your credit profile, may involve a hard inquiry, and creates additional borrowing capacity. Utilization should be only one factor in that decision.
Learn how different credit factors fit together →CONTINUE YOUR JOURNEY
Where to Go Next
Credit utilization is only one part of your credit profile. Continue with the topic that helps you better understand the information behind your balances, credit scores, and everyday credit-card decisions.
UNDERSTAND YOUR SCORE
Learn How Credit Scores Work
Choose this path if you understand utilization but want to see how it fits alongside payment history, account age, recent credit activity, and other information that can influence credit scores.
UNDERSTAND REPORTING
Learn What Gets Reported
Choose this path if you want to understand why the balance in your credit report may differ from the amount currently showing in your credit-card account.
MANAGE UTILIZATION
Put Credit Utilization Into Practice
Use this path if your main goal is understanding your own utilization numbers and making sense of changes in reported balances or credit limits.
CHECK THE DETAILS
Review Your Credit Information for Accuracy
If a reported balance, credit limit, or account does not look familiar or appears inaccurate, reviewing the information in your credit reports can help you understand what is actually being reported.
KEEP THE BIG PICTURE
Credit Utilization Is One Part of Responsible Credit Management
You do not need to chase a perfect utilization percentage. Focus on understanding what is reported, paying bills on time, keeping balances manageable, and using credit in a way that supports your broader financial situation.
SOURCES & METHODOLOGY
How We Built This Guide
Verestly prioritizes primary government sources and official credit-scoring resources when explaining credit utilization. These references support the definitions, calculation methods, reporting mechanics, scoring context, and consumer guidance used throughout this article.
LAST REVIEWED
September 2026
We periodically review this guide for accuracy, clarity, source quality, and changes in consumer-credit guidance, reporting practices, or credit-scoring information.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical systems, and actionable tools that help readers make more informed money and credit decisions.
View author profile →VERESTLY NEWSLETTER
Understand Your Credit, One Step at a Time
Get practical guides, beginner-friendly explanations, and educational resources designed to make credit and everyday money decisions easier to understand.
- Practical credit education
- Beginner-friendly financial guides
- New Verestly tools and resources
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Guides
Continue with guides that explain credit scores, credit reports, and the information used to evaluate your broader credit profile.