RETIREMENT · BEGINNER GUIDE
Retirement Planning for Beginners: Where to Start
Learn how retirement planning works, where to start, how workplace plans and retirement accounts fit together, and how to build a practical system for saving toward your future.
QUICK ANSWER
Where Should You Start With Retirement Planning?
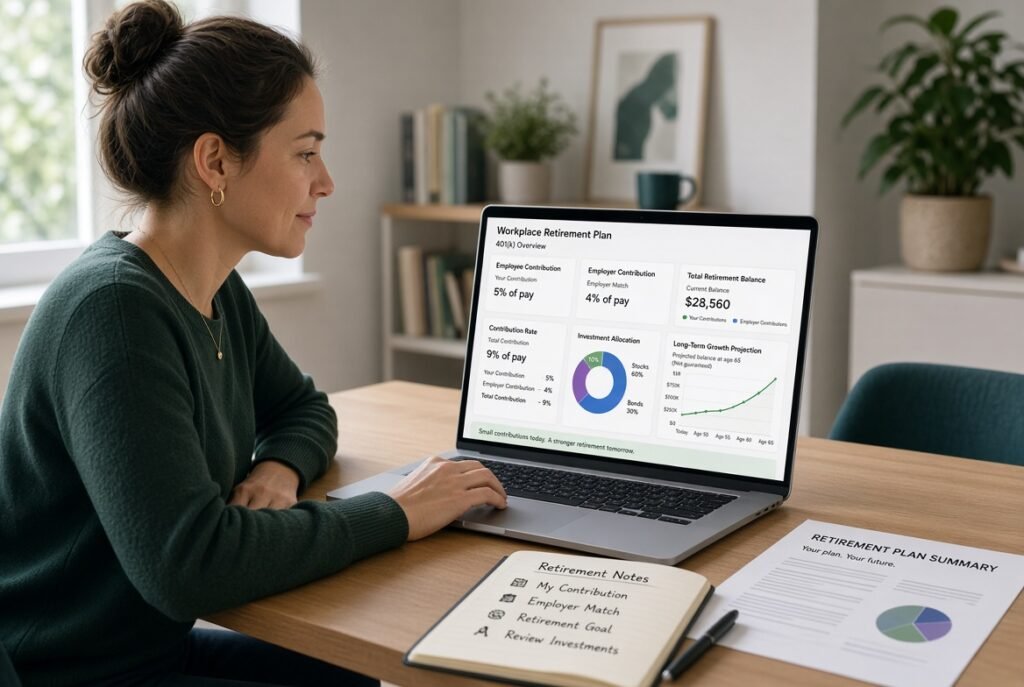
Start by understanding what retirement planning is meant to accomplish, reviewing the retirement accounts and benefits you already have, and choosing a contribution amount that fits your current financial situation. Then make sure your retirement money is invested intentionally and review your plan as your income, goals, and circumstances change.
What You'll Learn
- ✓ How to take inventory of your current retirement resources.
- ✓ How workplace retirement plans and employer benefits fit into your plan.
- ✓ How retirement accounts differ from the investments held inside them.
- ✓ How to think about contributions without relying on a universal savings percentage.
- ✓ How to build a simple process for reviewing and improving your retirement plan over time.
FIND YOUR STARTING POINT
Where Are You Starting From?
Retirement planning does not begin in the same place for everyone. Start by identifying what you already have, what you understand, and which decision needs your attention next.
I have not started saving for retirement
Begin by taking inventory of your income, workplace benefits, existing accounts, savings, and other financial obligations. You do not need a perfect long-term plan before taking the first useful step.
Start with my current financial picture →I have a workplace retirement plan
If your employer offers a 401(k), 403(b), or another retirement plan, review your eligibility, current contribution, employer contributions, vesting rules, investment choices, and plan fees.
Review my workplace plan →I am contributing, but I am not sure what happens next
Contributions are only one part of the process. Check where your retirement money is going, what investments you hold, what they cost, and whether the approach fits your time horizon and risk tolerance.
Understand how my money is invested →I feel behind on retirement savings
Starting later can change the trade-offs involved, but it does not make planning pointless. First identify what you have today, then evaluate the contribution, timing, and other planning levers available to you.
Identify my next retirement step →Your retirement starting point may change as your income, benefits, goals, and responsibilities change. The objective is not to solve every retirement decision today—it is to identify the next useful step.
SEE THE SYSTEM
How Retirement Planning Fits Together
Retirement planning is not one decision or one account. It is a system that connects your current financial position, retirement accounts, contributions, investments, and future income needs. Understanding how those pieces relate makes it easier to know what to work on next.
Current Position
Identify your income, expenses, savings, debts, retirement accounts, and workplace benefits.
Retirement Accounts
Understand which workplace plans or individual retirement accounts are available to you.
Contributions
Decide how much you can contribute now and understand any employer contribution rules that may apply.
Investments
Make sure the money inside your retirement accounts is invested intentionally for your time horizon and risk tolerance.
Review and Adjust
Revisit your contributions, accounts, investments, benefits, and retirement assumptions as your life changes.
The pieces work together
A retirement account is only one part of the plan. You also need to understand how much you are contributing, what the money is invested in, whether your employer provides additional benefits, and how those resources may eventually support your retirement income.
You do not need to solve every retirement decision at once. The useful starting point is to understand the system, identify what you already have, and then improve one part of the plan at a time.
CORE PRINCIPLE
Retirement planning works best as an ongoing process: understand where you are, contribute intentionally, invest appropriately, and adjust as your circumstances change.
BUILD THE FOUNDATION
The Core Building Blocks of Retirement Planning
You do not need to master every retirement rule before you begin. Start by understanding the accounts and plan features that may be available to you, then go deeper into each decision as needed.
STEP 1
Start With Your Current Retirement Picture
Before choosing a new account or changing your contribution, identify what you already have. That may include a current workplace plan, retirement accounts from previous employers, IRAs, pension benefits, or other long-term savings.
Your current cash flow matters too. Retirement contributions need to operate alongside essential expenses, emergency savings, debt payments, and other financial priorities rather than being treated as an isolated decision.
KEY IDEA
Retirement planning becomes easier once you know which resources, accounts, and benefits are already part of your financial picture.
STEP 2
Understand Your Workplace Retirement Plan
If your employer offers a retirement plan, learn how it works before assuming you need to open something elsewhere. Common workplace plans include 401(k) plans and 403(b) plans, although the specific rules and available features depend on the plan.
Review your eligibility, current contribution, available investment choices, fees, employer contributions, and whether the plan offers traditional or Roth contribution options.
- Confirm whether you are already enrolled.
- Check your current contribution amount or percentage.
- Review any employer contribution or matching formula.
- Find the plan's vesting rules and investment menu.
STEP 3
Know the Difference Between a Limit and a Target
Retirement accounts have annual contribution limits, but those limits are legal ceilings—not suggested savings targets.
For 2026, the employee elective-deferral limit for most 401(k) and 403(b) plans is $24,500. Eligible participants age 50 or older may have additional catch-up contribution capacity, with a higher catch-up limit applying at ages 60 through 63 in qualifying plans.
IMPORTANT
These figures describe 2026 contribution ceilings. They do not indicate how much any individual should contribute.
STEP 4
Review Employer Match and Vesting Separately
Some employers contribute to an employee's retirement account, often according to a matching formula. The amount available and the contribution required to receive it depend on the specific plan.
Vesting is a separate concept. Your own contributions to a 401(k) are generally fully vested, while some employer contributions may become fully yours only after you satisfy the plan's vesting schedule.
STEP 5
Understand Where IRAs Fit
Individual Retirement Arrangements, commonly called IRAs, are another type of retirement account. The two forms beginners encounter most often are Traditional IRAs and Roth IRAs.
They differ in tax treatment, and eligibility or deductibility may depend on factors such as income and workplace-plan coverage. For 2026, the combined annual contribution limit across Traditional and Roth IRAs is $7,500, with an additional $1,100 catch-up contribution available to eligible individuals age 50 or older.
STEP 6
Separate the Account From the Investment
A 401(k), 403(b), Traditional IRA, or Roth IRA describes the account structure. The investments held inside that account are a separate decision.
Depending on the plan or provider, retirement money may be held in mutual funds, target-date funds, index funds, bonds, company stock, or other available investments. Contributing money to an account does not by itself tell you how that money is invested.
KEY IDEA
First understand the account and its rules. Then confirm what investments are actually held inside it.
VERESTLY FRAMEWORK
The Verestly Retirement Planning Framework
Retirement planning becomes easier when you treat it as a sequence of repeatable decisions rather than one large calculation. This educational framework helps you organize the process from your current position to ongoing review.
Map Your Current Position
Identify your current retirement accounts, workplace benefits, savings, debts, cash flow, and any other resources that may affect your retirement plan.
Use the Accounts Available to You
Learn how your workplace plan or individual retirement account works, including eligibility, contribution rules, employer benefits, fees, and available investment choices.
Choose a Sustainable Contribution
Select an amount that fits your current financial situation, understand any employer contribution requirements, and plan to revisit the amount as your income and obligations change.
Invest Intentionally
Confirm how the money inside your retirement accounts is invested and whether the approach is consistent with your time horizon, risk tolerance, and available investment choices.
Review and Adjust Over Time
Revisit your contributions, accounts, investments, employer benefits, beneficiaries, and retirement assumptions as your financial life changes.
THE CORE IDEA
You do not need to complete each stage perfectly before moving forward. This is a Verestly educational framework—not an official retirement rule—and its purpose is to help you identify the next useful decision while keeping the overall plan moving.
PRACTICAL EXAMPLE
What Retirement Planning Can Look Like in Practice
Retirement planning becomes easier to understand when the major decisions are viewed in sequence. This hypothetical example shows how someone could review an existing workplace plan and identify the next useful steps without trying to solve every retirement question at once.
HYPOTHETICAL STARTING POINT
An Early Retirement Planning Snapshot
Consider a worker earning $60,000 per year who has access to a workplace 401(k), is already contributing 3% of pay, and has accumulated a modest retirement balance.
The objective is not to identify a universally correct contribution rate. It is to understand the existing plan, confirm how the money is being used, and decide which part of the retirement system deserves attention next.
| Annual gross income | $60,000 |
|---|---|
| Workplace retirement plan | 401(k) |
| Current employee contribution | 3% of pay |
| Approximate monthly contribution | $150 |
| Current retirement balance | $8,500 |
| IRA | None currently |
| Next planning priority | Review the existing plan |
APPLYING THE FRAMEWORK
A Possible Sequence of Next Steps
MAP
Confirm the Current Retirement Picture
The first step is to identify the current 401(k) balance, contribution level, any old retirement accounts, available savings, and other financial obligations.
ACTIVATE
Review the Workplace Plan
Next, review the plan documents to understand any employer contribution formula, vesting rules, fees, Roth options, and the investment choices available inside the account.
CONTRIBUTE
Evaluate the Current Contribution
After reviewing current cash flow and the plan rules, the contribution can be evaluated to determine whether the existing 3% remains appropriate or whether a sustainable increase is possible.
INVEST
Check Where the Contributions Are Invested
The next check is whether contributions are actually invested, which investments are being used, what they cost, and whether the overall approach is consistent with the investor's time horizon and risk tolerance.
REVIEW
Set a Future Review Point
The plan can be reviewed again after a meaningful change such as a raise, new job, change in expenses, updated employer benefits, or another major financial event.
THE TAKEAWAY
The First Improvement Is Clarity
Retirement planning does not require choosing every account, contribution level, investment, and retirement date at the same time. A clearer sequence is to understand what already exists, review the rules that apply, make one informed decision, and continue improving the plan over time.
This example is hypothetical and for educational purposes only. The figures are illustrative, not recommended contribution targets or projections. Actual retirement decisions depend on factors such as income, expenses, available plans, taxes, goals, time horizon, and individual circumstances.
PLAN YOUR CONTRIBUTIONS
How Should You Think About Retirement Contributions?
There is no universal retirement contribution percentage that works for everyone. A useful starting point is to identify which contribution question applies to your situation, then review the plan rules and financial trade-offs involved.
IF THIS SOUNDS LIKE YOU
You are not contributing yet
Start by reviewing whether you have access to a workplace retirement plan, whether you are eligible to participate, and how a contribution would fit alongside your current expenses and other financial obligations.
IF THIS SOUNDS LIKE YOU
Your employer offers a retirement contribution or match
Review the actual matching formula, the contribution required to receive employer money, and any vesting rules that apply. These details vary by plan and should be confirmed in your plan documents.
IF THIS SOUNDS LIKE YOU
You are contributing but do not know whether it is enough
Separate your current contribution from your longer-term retirement goal. The amount that fits your budget today may not be the same amount eventually required to support your desired retirement timeline and spending.
IF THIS SOUNDS LIKE YOU
You feel behind on retirement saving
Starting later can change the trade-offs involved, but it does not make planning pointless. Begin by measuring your current position and then review the contribution, timeline, catch-up, and retirement-income options available to you.
WANT A CLEARER RETIREMENT SNAPSHOT?
Review the Major Pieces of Your Retirement Plan
The planned Verestly Retirement Readiness Calculator is designed to help organize key retirement-planning inputs and identify areas that may deserve a closer review.
Planned Verestly resource · Educational use
PLANNED VERESTLY TOOL
Turn Your Retirement Information Into a Clearer Planning Snapshot
The planned Retirement Readiness Calculator is designed to help you organize key retirement-planning inputs in one place and identify areas of your plan that may deserve a closer review.
- ✓ Organize your current retirement accounts and contributions.
- ✓ Review major inputs such as time horizon, existing savings, and workplace retirement benefits.
- ✓ Identify which part of your retirement plan may need additional research or attention.
Planned Verestly resource · Educational use
REVIEW AREA
Which parts of your retirement plan have you already reviewed?
PREFER TO REVIEW IT MANUALLY?
Use the retirement planning checklist later in this guide to review your accounts, contributions, investments, benefits, and next steps at your own pace.
PUT IT INTO ACTION
Your 30-Day Retirement Planning Action Plan
You do not need to solve every retirement decision this month. Use the next 30 days to organize what you already have, understand the rules that apply to your accounts, review your contributions, and create a simple routine for ongoing retirement planning.
TODAY
15–30 minBuild Your Retirement Snapshot
Identify the retirement accounts and benefits you already have before deciding what to change. The goal today is visibility, not optimization.
- List your current workplace retirement accounts and IRAs.
- Find any retirement accounts from previous employers.
- Note current balances and contribution amounts.
WEEK 1
Review the rulesUnderstand Your Workplace Plan
Review the plan information provided by your employer or plan administrator so you know what features and rules actually apply to your account.
- Confirm your current employee contribution.
- Review any employer match or contribution formula.
- Check vesting rules, fees, and available investment choices.
WEEK 2
Review contributionsEvaluate What You Are Contributing
Compare your current retirement contribution with your present cash flow and broader retirement goals. Avoid treating a legal contribution limit or a generic percentage as a universal target.
- Confirm how much you are currently contributing.
- Check whether the amount is sustainable within your budget.
- Identify when you will review or reconsider the amount.
WEEK 3
Review investmentsCheck Where Your Retirement Money Is Invested
Confirm that contributions are actually invested and review the available information about your holdings, costs, time horizon, and risk exposure.
- Identify the investments currently held in each account.
- Review available fees or expense information.
- Confirm that you understand the level of investment risk involved.
WEEK 4
Build the routineSet Your Next Retirement Review
Turn what you learned into a repeatable process. Decide which part of the plan deserves attention next and set a future date or event that will trigger another review.
- Update beneficiaries if needed.
- Note any unanswered questions about accounts or benefits.
- Set a review point after a raise, job change, or other meaningful event.
KEEP IT PRACTICAL
The Goal Is a Repeatable Process, Not a Perfect Retirement Plan
Retirement planning will change as your income, accounts, benefits, goals, and life circumstances change. A useful plan is one you understand well enough to review and improve over time.
AVOID THESE PITFALLS
Common Retirement Planning Mistakes to Avoid
Retirement planning problems often develop gradually rather than from one major mistake. These common pitfalls can make it harder to understand your progress or keep your long-term plan aligned with your financial life.
Waiting for the Perfect Time to Start
It is easy to postpone retirement saving while waiting for higher income, lower expenses, or a fully developed long-term plan.
Start by understanding your current position and, when your finances allow, choose a contribution you can realistically maintain and review later.
Treating a Contribution Limit as a Savings Target
Annual retirement-account limits define how much may be contributed under applicable rules. They do not tell every saver how much they personally need to contribute.
Separate legal contribution limits from your own retirement goal, current cash flow, timeline, and other financial priorities.
Ignoring Employer Match or Vesting Rules
Workplace retirement benefits can include employer contributions and vesting requirements that differ from one plan to another.
Review the actual plan documents so you understand the matching formula, eligibility requirements, and when employer contributions become fully vested.
Assuming the Account Is the Investment
Opening or contributing to a 401(k), 403(b), or IRA does not by itself explain how the money inside the account is invested.
Review both the account rules and the investments held inside it, including their role, risk, and costs.
Setting the Plan Once and Never Reviewing It
Contributions, employer benefits, income, expenses, investments, beneficiaries, and retirement goals can all change over time.
Review the plan periodically and after meaningful events such as a raise, job change, major expense, or change in household circumstances.
Treating Feeling Behind as a Reason Not to Start
Starting later can make retirement trade-offs more significant, but avoiding the numbers does not make those trade-offs disappear.
Establish your current position first, then evaluate the contribution, timeline, catch-up, spending, and retirement-income levers available to you.
FREQUENTLY ASKED QUESTIONS
Retirement Questions Beginners Often Ask
These short answers address common questions that arise when you are building a retirement plan for the first time.
How much should I save for retirement?
There is no single percentage that works for everyone. A retirement savings target depends on factors such as your age, existing savings, income, retirement timeline, expected spending, benefits, and other financial resources.
Explore the beginner retirement savings framework →Should I use a 401(k) or an IRA?
They are different retirement-account structures with different rules, investment choices, contribution limits, tax treatment, and eligibility considerations. Some people may use both rather than treating the decision as an either-or choice.
Review how workplace plans and IRAs differ →Is a Roth IRA always better than a Traditional IRA?
No. Their tax treatment differs, and eligibility, deductibility, current tax circumstances, and future expectations can all affect how the comparison should be evaluated. Neither account type is universally better.
Compare Traditional and Roth IRAs →Does putting money into a retirement account mean it is invested?
Not necessarily. The retirement account is the structure that holds the assets. You should also confirm what investments are actually held inside the account and whether contributions are being invested as intended.
Can Social Security be part of my retirement plan?
Yes. Social Security can be one source of retirement income for eligible workers. The age at which benefits begin can affect the monthly amount, so claiming should be considered alongside other retirement resources and household circumstances.
How often should I review my retirement plan?
There is no required review schedule for a personal retirement plan. A practical approach is to review it periodically and whenever a meaningful change occurs, such as a new job, raise, change in expenses, or major change in your retirement goals.
Review the retirement planning checklist →CONTINUE YOUR RETIREMENT JOURNEY
Where to Go Next
Once you understand the basic retirement planning system, the next step is to go deeper into the decision that matters most to your situation. Choose the path that matches the question you need to answer next.
UNDERSTAND YOUR PLAN
Go Deeper Into Your Workplace Retirement Plan
Choose this path if you have access to a 401(k) and want to better understand contributions, employer match, vesting, and how the plan works.
COMPARE ACCOUNT TYPES
Understand Traditional and Roth IRAs
Choose this path if you want to understand how individual retirement accounts differ in tax treatment, eligibility, contribution rules, and their role alongside workplace plans.
REVIEW YOUR SAVINGS TARGET
Explore How Much You May Need to Save
Use this path if you are already contributing but want to understand how your current savings effort relates to a broader retirement goal.
START FROM WHERE YOU ARE
Build a Plan If You Feel Behind
Choose this path if retirement saving started later than you expected or your current balance feels lower than you hoped. The first step is to measure your current position before deciding which planning lever to adjust.
NOT SURE WHICH PATH COMES NEXT?
Start With the Retirement Question You Still Cannot Answer
If several areas need attention, return to your retirement snapshot and identify the first unresolved question about your accounts, contributions, investments, benefits, or timeline. Work through that question before adding more complexity.
SOURCES & METHODOLOGY
How We Built This Retirement Guide
Verestly prioritizes primary government sources and regulators when explaining retirement rules, contribution limits, workplace plan mechanics, Social Security, and investing concepts. Rules that can change over time are reviewed against current official guidance before publication.
LAST REVIEWED
September 2026
This guide was reviewed for current retirement contribution limits, workplace-plan rules, Social Security information, source quality, clarity, and editorial accuracy.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical financial systems, and educational resources that help readers understand complex money decisions more confidently.
View author profile →VERESTLY NEWSLETTER
Build Your Financial Knowledge, One Step at a Time
Get practical guides, financial tools, and beginner-friendly resources designed to help you make clearer money decisions.
- Practical financial education
- New calculators and tools
- Beginner-friendly planning resources
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Retirement Guides
Continue with three carefully selected guides that build on the retirement planning concepts covered here.