SAVING · EMERGENCY FUND GUIDE
Where Should You Keep Your Emergency Fund?
Your emergency fund should be easy to reach when you genuinely need it, protected from unnecessary risk, and separate enough from everyday spending that you are less likely to use it by accident. Here is how to evaluate where your emergency savings belong without chasing yield at the expense of access or safety.
QUICK ANSWER
Keep Your Emergency Fund Somewhere Safe, Accessible, and Separate
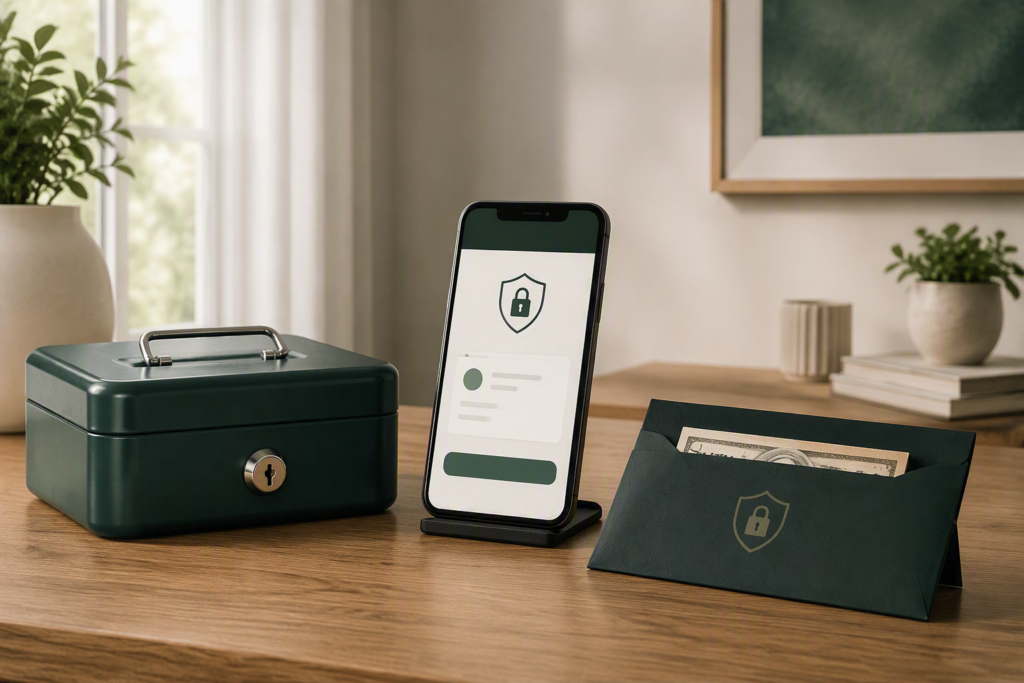
For many people, a dedicated savings account at an insured bank or credit union can be a practical place to keep emergency savings. The goal is not simply to earn the highest possible return. The money should remain protected, reasonably easy to access, and separate enough from everyday spending that you are less likely to use it for non-emergencies.
Protect the Money First
Emergency savings should generally avoid unnecessary risk of losing principal. Eligible deposit accounts at federally insured banks or credit unions can provide deposit or share insurance within applicable coverage limits.
Make Sure You Can Reach It
An emergency fund needs enough liquidity for unexpected expenses. An account that takes too long to access or imposes meaningful withdrawal restrictions may be a poor fit for the portion of your fund you expect to need quickly.
Keep It Separate From Spending
Keeping emergency savings away from your everyday checking balance can create useful friction. The money remains available when needed without constantly looking like extra spending money.
This does not mean every emergency fund must sit in one account. Depending on your situation, you may eventually choose to keep different portions of your reserve in places with different levels of immediate access.
WHY THIS MATTERS
The Wrong Place Can Make an Emergency Fund Harder to Use
Building an emergency fund is only part of the job. Where you keep the money can affect how quickly you can reach it, how protected it is, and how likely you are to spend it before a real emergency arrives.
Access Matters When Timing Matters
Emergency expenses can be time-sensitive. A car repair, urgent home expense, unexpected travel need, or temporary income interruption may require money quickly. If your entire reserve is locked behind withdrawal restrictions, settlement delays, or penalties, the fund may be less useful at the moment you need it.
Too Much Access Can Create a Different Problem
Keeping emergency savings mixed into the same checking balance you use for groceries, bills, and everyday purchases can make the money feel available for routine spending. Separating it can create a useful boundary without making it unavailable in a genuine emergency.
Chasing Return Can Conflict With the Fund's Job
Higher expected returns often come with additional risk, restrictions, or volatility. That tradeoff may be reasonable for long-term investing, but emergency savings have a different purpose: helping cover an unexpected near-term need without depending on favorable market conditions.
The goal is not to find a perfect account. It is to choose a location whose tradeoffs match the job your emergency fund needs to perform.
A SIMPLE DECISION FRAMEWORK
Use the Verestly Emergency Fund Placement Check
You do not need to compare every account on the market. Start by testing any potential location against four practical questions: safety, access, separation, and cost or return.
SAFETY
Ask What Protects the Money
Emergency savings are meant to be available when something goes wrong, so protecting the principal matters. If you are considering a bank or credit-union deposit account, confirm that the institution and account are eligible for applicable federal deposit or share insurance.
Could this money lose value because of market movements, institution risk, or another feature I do not fully understand?
ACCESS
Check How Fast You Can Actually Use It
Do not assume that "available" means immediately spendable. Transfers can take time, some products restrict withdrawals, and certain accounts may impose penalties or procedural delays. Think about the real path from the account to the bill you may need to pay.
If I had an urgent expense today, how long would it take before I could actually use this money?
SEPARATION
Create Enough Friction to Protect It From Routine Spending
Emergency savings should be accessible without constantly blending into your normal spending balance. A separate account or clearly separated savings bucket may make it easier to see the money as a reserve rather than available spending cash.
Will seeing this balance every day make me more likely to spend it on something that is not an emergency?
COST & RETURN
Evaluate Yield Only After the Basics Work
Once safety, access, and separation are acceptable, compare the practical economics. Fees, minimum-balance rules, withdrawal penalties, and interest can all matter. A higher yield may be useful, but not if it creates a tradeoff that weakens the fund's primary purpose.
Am I accepting meaningful restrictions or risk just to earn a somewhat higher return?
REAL-LIFE EXAMPLE
The Right Setup Can Look Different for Different Households
Emergency-fund placement is not one-size-fits-all. The same amount of savings can be structured differently depending on how quickly a household may need the money, how stable its income is, and how much separation from everyday spending is helpful.
EXAMPLE A
Stable Income, Simple Access Needs
Jordan has steady income, a separate checking account for monthly spending, and no reason to expect frequent emergency withdrawals. One possible setup is keeping the emergency fund in a dedicated insured savings account that can be transferred to checking when needed.
EXAMPLE B
Variable Income, More Immediate Liquidity
Maya's income changes from month to month. Because a temporary income gap could require faster access, she may prefer to keep part of her reserve especially easy to reach and the rest in a separate insured savings location.
EXAMPLE C
Larger Reserve, Multiple Access Layers
Chris has built a larger emergency reserve and wants to keep some money immediately accessible without leaving the entire balance near everyday spending. One possible approach is using more than one location, with different portions offering different levels of access.
COMPARE YOUR OPTIONS
Where Can You Keep an Emergency Fund?
Several places can hold emergency savings, but they do not all serve the same role. Compare each option by how well it supports safety, access, separation from spending, and the purpose of the money.
| Option | Access | Main advantage | Watch for | Possible role |
|---|---|---|---|---|
| Dedicated savings account | Usually straightforward | Keeps emergency money separate while remaining relatively easy to reach | Fees, transfer timing, minimums, and account terms | Can be a practical primary location for many households |
| Money market deposit account | Varies by institution and account | Can combine deposit-account access with interest | Minimum balances, fees, withdrawal rules, and confusing it with a money market mutual fund | May serve a similar role to savings when the terms fit |
| Checking account | Very high | Money can be immediately available for payments | Greater temptation to spend and less separation from routine expenses | May hold a limited immediate-access portion |
| Certificate of deposit | More restricted | May offer a defined return for money that does not need immediate access | Early-withdrawal penalties, maturity dates, and reduced flexibility | May fit only part of a larger reserve when restrictions are understood |
| Physical cash | Immediate | Can remain usable during certain payment or access disruptions | Theft, loss, damage, and no interest | May complement, rather than replace, an account-based reserve |
| Market investments | Depends on the asset and settlement process | Potential for long-term growth | Market losses, volatility, and the possibility of needing to sell at an unfavorable time | Generally better suited to longer-term goals than immediately needed emergency cash |
OFTEN THE SIMPLEST START
A Dedicated Insured Savings Account
For many beginners, a separate savings account can offer a useful combination of accessibility and behavioral separation. If you use this approach, verify that the financial institution is federally insured and review the account's fees, transfer timing, minimums, and withdrawal terms.
IMPORTANT DISTINCTION
Money Market Account ≠ Money Market Fund
A money market deposit account offered by an insured bank or credit union is a deposit product. A money market mutual fund is an investment product. The names sound similar, but the protections and risks are not the same.
You do not have to choose the option with the highest return. Start with the location that makes your emergency fund reliably usable, then evaluate whether better rates or additional layers can be added without weakening access or safety.
FREE VERESTLY TOOL
Plan Different Levels of Emergency-Fund Access
Your emergency fund does not necessarily need to sit in one place. The Emergency Fund Ladder Planner can help you think through how much money you may want available immediately, how much can sit slightly farther from everyday spending, and how different layers can support different types of financial disruptions.
Map Immediate Access
Identify the portion of your reserve that may need to be available quickly for urgent expenses.
Add Separation
Consider whether another portion could sit farther from everyday spending while still remaining reasonably accessible.
Review the Full Structure
See whether your emergency reserve is relying too heavily on one access method or one type of account.
The planner is an educational tool. It does not determine how much emergency savings you need or prescribe a specific bank, account, or allocation.
PUT IT INTO PRACTICE
Review Your Emergency Fund Location in Five Steps
You do not need to rebuild your entire emergency-fund setup today. A short review can help you identify whether your current location is safe enough, accessible enough, and appropriately separated from everyday spending.
Identify Where the Money Sits Today
Write down each place holding emergency savings, including checking, savings, money market deposit accounts, CDs, cash, or investment accounts.
Check Safety and Protection
If the money is held at a bank or credit union, confirm the institution's insurance status and whether the account is an eligible deposit or share product. If it is invested, note that the value can fluctuate.
Test Real Access
Consider how long it would take to move the money into a spendable form during an urgent expense. Review transfer timing, withdrawal limits, penalties, and any other access restrictions.
Check Whether It Is Too Easy to Spend
If your emergency savings are mixed into your everyday checking balance, consider whether a separate account or savings bucket would create a clearer boundary.
Improve the Setup Only Where Needed
If your current setup already provides adequate safety, access, and separation, you may not need to change much. If one area is weak, improve that specific part before chasing a higher return.
QUICK CHECKLIST
Your emergency fund location may be working well if:
- The money is protected in a way you understand.
- You can access it within a timeframe that fits your likely emergencies.
- It is not mixed so closely with routine spending that you regularly dip into it.
- Fees, minimums, or penalties are not undermining the account's usefulness.
- You are not depending on favorable market conditions to cover an urgent need.
COMMON MISTAKES
Avoid These Emergency-Fund Placement Mistakes
Most placement mistakes come from optimizing one feature while ignoring the fund's overall purpose. A higher rate, faster access, or greater convenience can all be useful—but not when another essential part of the setup breaks down.
Chasing the Highest Yield
A better rate can be helpful, but it should not automatically outweigh transfer delays, fees, withdrawal restrictions, or a setup that is difficult to manage.
Better approach: compare return only after safety and access are acceptable.
Keeping Everything in Everyday Checking
Immediate access is convenient, but mixing emergency savings with routine spending can make the reserve harder to protect from non-emergency purchases.
Better approach: create enough separation to preserve the money's purpose.
Locking the Entire Fund Away
CDs and other restricted products may have a role in some larger reserve structures, but putting every emergency dollar behind penalties or delayed access can reduce flexibility.
Better approach: preserve enough liquidity for the emergencies you may need to handle quickly.
Treating Investments Like Cash Reserves
Stocks, funds, and other market investments can lose value. If you need the money during a downturn, you may have to sell at an unfavorable time.
Better approach: keep near-term emergency money separate from longer-term investment goals.
Assuming Similar Names Mean Similar Protections
A money market deposit account and a money market mutual fund are different products. One may be an insured deposit product; the other is an investment.
Better approach: verify the product type instead of relying on the account name.
Building a Setup That Is Too Complicated
Multiple accounts, transfer rules, maturity dates, and access layers can become counterproductive if you cannot quickly understand where your emergency money is or how to use it.
Better approach: use the simplest structure that still meets your needs.
FREQUENTLY ASKED QUESTIONS
Common Questions About Where to Keep an Emergency Fund
Emergency-fund placement becomes easier when you separate the fund's core job—staying safe and usable—from questions about maximizing return or choosing a specific financial product.
Should I keep my emergency fund in checking or savings?
A dedicated savings account can provide useful separation from everyday spending while still keeping the money relatively accessible. Checking may offer faster access, but keeping the entire reserve there can make it easier to spend accidentally. Some households may use both for different portions of their reserve.
Is a high-yield savings account good for an emergency fund?
It can be, provided the account also meets your needs for safety, access, fees, minimums, and transfer speed. A higher yield is useful only if the account still works well when you actually need the money.
Can I keep my emergency fund in a money market account?
A money market deposit account may be suitable when its access rules, fees, minimums, and insurance status fit your needs. Be careful not to confuse it with a money market mutual fund, which is an investment product and does not have the same type of federal deposit insurance.
Should I invest my emergency fund?
Money you may need unexpectedly generally serves a different purpose from long-term investment money. Market investments can lose value, which can force you to sell at an unfavorable time if an emergency happens during a market decline.
Is it okay to split my emergency fund between accounts?
Yes. Some households may prefer to keep one portion very easy to reach and another portion more separated from everyday spending. The appropriate structure depends on your circumstances, access needs, and the account terms you are comfortable managing.
Should I keep emergency cash at home?
A limited amount of physical cash may be useful during certain payment or access disruptions, but cash can be lost, stolen, or damaged and does not earn interest. It may be more appropriate as a complement to an account-based emergency reserve rather than the only place you keep it.
Can I put part of my emergency fund in a CD?
Possibly, especially if you have a larger reserve and understand the CD's maturity date and early-withdrawal terms. The portion you may need immediately should not depend entirely on money that is difficult or costly to access.
KEEP LEARNING
Continue Building Your Emergency-Fund System
Placement is only one part of emergency preparedness. These related guides can help you decide how much to save and how to build the fund itself.
SOURCES & METHODOLOGY
How We Verified This Guide
Verestly prioritizes primary government sources, financial regulators, and other authoritative references. For this guide, we reviewed guidance covering emergency savings, deposit protection, credit-union share insurance, investment risk, and liquidity restrictions.
LAST REVIEWED
September 2026
This guide was reviewed for financial accuracy, source quality, clarity, search intent, and current emergency-savings guidance.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on practical systems, clear explanations, and actionable financial tools.
View author profile →VERESTLY NEWSLETTER
Get Practical Money Guides and Tools
Join Verestly for beginner-friendly financial education, new tools, practical systems, and resources you can actually use.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED GUIDES
Continue Learning
Explore three additional guides selected to help you continue building a stronger emergency-savings system.