BUDGETING · BUDGET FRAMEWORKS
The 50/30/20 Budget Rule: Does It Really Work?
Learn how the 50/30/20 budget rule divides your take-home income, what belongs in each category, when the percentages can be useful, and how to adjust the framework when real-life expenses do not fit.
QUICK ANSWER
The Short Answer
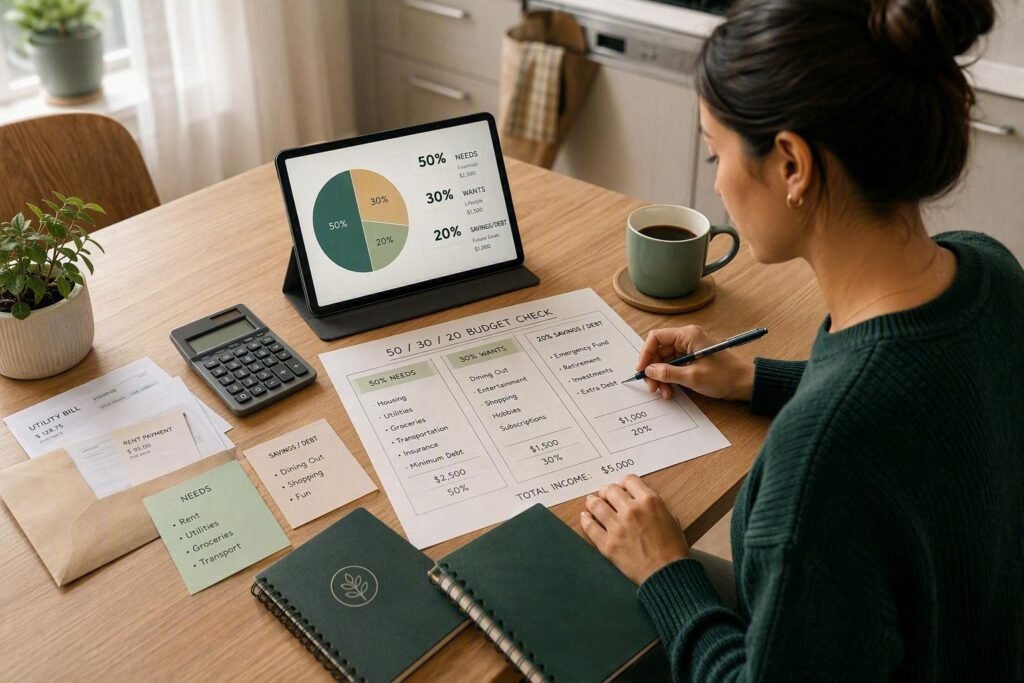
The 50/30/20 budget rule can work as a simple way to organize take-home income, but it is best treated as a flexible framework, not a universal rule. The standard split assigns 50% to needs, 30% to wants, and 20% to savings and financial goals. If your essential expenses already exceed 50%, the framework can still help you understand where your budget is under pressure and what trade-offs are realistically available.
What You'll Learn
- ✓ How the 50/30/20 rule divides your take-home income.
- ✓ What usually counts as a need, a want, or a financial goal.
- ✓ How to calculate the framework using your own monthly income.
- ✓ When the standard percentages may fit—and when they may not.
- ✓ How to adjust the framework without forcing unrealistic numbers.
CHECK YOUR CURRENT SPLIT
Where Does Your Budget Stand Today?
Before trying to match 50%, 30%, and 20%, look at how your take-home income is already being divided. The framework becomes more useful when you compare it with your actual spending instead of treating the percentages as a pass-or-fail test.
My needs are close to 50%
If housing, utilities, groceries, transportation, insurance, and other necessary costs already fit near half of your take-home income, the standard framework may be relatively easy to test.
See how the rule works →My needs are already above 50%
If essential expenses already consume more than half of your take-home income, do not force them into an artificial target. First identify which costs are creating the pressure.
See how to adapt →I am not sure what counts as a need
Some expenses are easy to classify, while others contain both necessary and discretionary elements. The goal is to use consistent categories that make your trade-offs visible.
Classify my expenses →My percentages already look different
A 60/20/20 or 55/25/20 split does not automatically mean your budget is wrong. Your current percentages can help show where flexibility exists and where fixed costs are limiting it.
Understand my current split →The 50/30/20 percentages are a reference point, not a requirement. Start with your real income and expenses, then use the framework to understand what your current allocation is telling you.
HOW THE RULE WORKS
How the 50/30/20 Budget Rule Divides Your Income
The framework starts with your monthly take-home income and divides it into three broad purposes: necessary expenses, discretionary spending, and money directed toward savings and financial goals.
Start With Take-Home Income
Use the income that is actually available after taxes and other required payroll deductions.
Needs
Allocate about half toward necessary living expenses and required financial obligations.
Wants
Use up to roughly 30% for optional spending, convenience, entertainment, and lifestyle choices.
Savings and Financial Goals
Direct the remaining share toward savings and financial goals, including additional debt repayment.
The percentages are based on available income
The 50/30/20 framework is generally applied to take-home pay, not gross salary. That distinction matters because the budget should be built around money you can actually allocate during the month.
If you bring home $4,000 per month, the standard framework would translate to about $2,000 for needs, $1,200 for wants, and $800 for savings and financial goals.
CORE PRINCIPLE
The 50/30/20 rule is most useful as an allocation framework. The percentages help you see how your income is being used; they do not make necessary expenses fit automatically.
Think in buckets before individual categories
Unlike a highly detailed budget, this method does not require you to assign a separate percentage to groceries, fuel, dining out, subscriptions, or every other expense.
Instead, those expenses are grouped into three larger buckets. The next step is deciding which bucket each expense belongs in, especially when the difference between a need and a want is not obvious.
SORT THE THREE BUCKETS
What Counts as a Need, a Want, or a Financial Goal?
The math behind 50/30/20 is simple. The harder part is deciding where individual expenses belong. Some are obvious, while others depend on what the expense does in your particular household.
50% BUCKET
Start With Expenses You Need to Cover
Needs are expenses that are reasonably necessary to maintain your household, health, basic obligations, and ability to earn income.
Depending on your circumstances, this can include housing, utilities, basic groceries, necessary transportation, insurance, essential healthcare, childcare required for work, and minimum required debt payments.
- Rent or mortgage payments.
- Basic utilities and household services.
- Groceries and essential household supplies.
- Necessary transportation and insurance.
- Essential healthcare and medication.
- Minimum required debt payments and other unavoidable obligations.
KEY IDEA
The purpose of the expense matters more than whether the bill is fixed, recurring, or expensive.
30% BUCKET
Separate Lifestyle Spending From Basic Needs
Wants generally improve comfort, convenience, entertainment, or lifestyle but can be reduced, delayed, replaced, or removed without preventing you from meeting a basic obligation.
That can include restaurant meals, entertainment subscriptions, recreational spending, vacations, nonessential shopping, premium upgrades, and other discretionary purchases.
- Dining out and food delivery.
- Entertainment and optional subscriptions.
- Hobbies and recreational spending.
- Vacations and discretionary travel.
- Nonessential shopping and premium upgrades.
REMEMBER
The 30% bucket is an allowance for discretionary spending, not a target you are required to spend.
20% BUCKET
Reserve Money for Savings and Financial Goals
The final bucket creates space for money that supports future priorities rather than current lifestyle spending.
That can include savings contributions and payments made above required debt minimums. The 50/30/20 framework identifies the allocation; detailed saving systems and debt-payoff strategies belong in their own plans.
DEBT CLASSIFICATION
Separate Required Payments From Extra Progress
Debt can be confusing inside a percentage-based budget because required payments and voluntary extra payments serve different roles.
A minimum payment is part of the amount your current budget must cover. An additional payment is a deliberate choice to direct more available income toward a financial goal.
PRACTICAL DISTINCTION
Treat required minimums as obligations. Treat amounts paid above those minimums as progress toward a financial goal.
GRAY AREAS
Some Expenses Contain Both a Need and a Want
Real household expenses do not always fit neatly into one category. Transportation may be necessary for work, for example, while choosing a more expensive vehicle can add a discretionary component.
The same distinction can appear with housing, food, phones, clothing, and other categories. The underlying need may be real even when part of the cost reflects preference or convenience.
Groceries needed for regular meals.
Restaurant meals, delivery, or premium upgrades.
You do not need perfect classification. You need a consistent approach that makes the trade-offs in your budget easier to see.
PUT IT TOGETHER
What 50/30/20 Looks Like With $4,000 of Take-Home Pay
Suppose your household has $4,000 available after taxes each month. Under the standard framework, the three buckets would look like this.
IMPORTANT
This example shows how the framework is calculated. It does not mean every household should be able to match these percentages exactly.
VERESTLY FRAMEWORK
The Verestly 50/30/20 Fit Check
If your actual budget does not match 50%, 30%, and 20%, do not force the numbers. Use this educational framework to identify what is driving the difference, protect essential expenses, and make adjustments where flexibility actually exists.
Calculate Your Actual Split
Compare your real take-home income with what you currently spend on needs, wants, savings, and other financial goals.
Find the Main Constraint
Identify whether housing, transportation, childcare, healthcare, debt obligations, or another category is pushing your actual percentages away from the standard framework.
Protect Required Expenses First
Keep essential living costs and required obligations visible. Do not reduce a necessary expense on paper simply to make the percentages appear closer to 50/30/20.
Change the Flexible Parts
Review discretionary spending, timing, recurring costs, and financial-goal contributions to see which areas can be adjusted without ignoring real household needs.
Review the Split as Life Changes
Recalculate after changes in income, housing, childcare, debt, transportation, or other major expenses. Your workable split can change over time.
EDUCATIONAL FRAMEWORK
The Verestly 50/30/20 Fit Check is not an official budgeting rule. It is a practical review process for using the 50/30/20 framework without treating its percentages as mandatory targets.
EXAMPLE
This split does not automatically mean the budget is wrong. The useful next question is why needs are at 62% and whether any part of the remaining 38% should be adjusted.
REAL-LIFE EXAMPLE
What the 50/30/20 Rule Looks Like in Practice
The percentages become easier to evaluate when you compare them with an actual monthly budget. This example shows both a clean 50/30/20 split and what happens when real expenses push the budget away from the standard framework.
STARTING POINT
Meet Jordan
Jordan takes home $4,000 per month and wants a simple way to understand how much income is supporting necessary expenses, lifestyle spending, and future financial goals.
The first step is not to force the budget into three perfect percentages. It is to calculate the actual split and compare it with the 50/30/20 reference point.
| Category | Share | Amount |
|---|---|---|
| Needs | 50% | $2,000 |
| Wants | 30% | $1,200 |
| Savings + financial goals | 20% | $800 |
| Total take-home income | 100% | $4,000 |
APPLYING THE FRAMEWORK
Jordan's Actual Budget Looks Different
MEASURE
Calculate the Real Percentages
Jordan confirms that needs consume $2,400, or 60% of take-home income, rather than the $2,000 suggested by the standard 50% reference point.
LOCATE
Identify What Is Driving the Difference
Higher housing and transportation costs explain most of the gap. Those expenses are necessary in Jordan's current situation, so simply relabeling them would not make the budget more realistic.
PROTECT
Keep Required Costs Visible
Jordan keeps the full $2,400 in the needs bucket instead of pretending that $400 of necessary costs belongs somewhere else just to reach the 50% target.
ADJUST
Work With the Flexible Categories
Wants are already below the standard 30% allocation, which helps preserve $720 for savings and other financial goals even though needs are higher than 50%.
RECHECK
Revisit the Split When Costs Change
If income increases, transportation costs fall, or housing changes, Jordan can recalculate the allocation and decide whether more money should move toward financial goals.
THE TAKEAWAY
A Different Split Can Still Be Useful
Jordan's 60/22/18 allocation does not match the classic rule, but the framework still reveals something useful: necessary costs are the main constraint, discretionary spending is already below the reference level, and some income is still being directed toward future priorities.
This example is illustrative, not a recommended percentage split. Real allocations depend on income, housing, transportation, healthcare, childcare, debt obligations, and other household circumstances.
CHECK THE FIT
Does the 50/30/20 Rule Fit Your Situation?
The framework can be useful in different ways depending on your income, fixed costs, and budgeting preferences. Use the paths below to see whether the standard percentages are workable, need adapting, or simply are not the best planning method for your current situation.
IF THIS SOUNDS LIKE YOU
Your essential expenses are reasonably close to 50%
If housing, transportation, groceries, insurance, healthcare, and other required costs fit near half of your take-home income, the standard framework may provide a simple structure without requiring dozens of individual spending limits.
IF THIS SOUNDS LIKE YOU
Your needs already take more than 50%
High housing, transportation, childcare, healthcare, insurance, or other necessary costs can make the classic split unrealistic. The framework can still reveal where your budget is constrained without requiring you to force essential expenses lower on paper.
IF THIS SOUNDS LIKE YOU
Your income changes significantly from month to month
If your income is irregular, the three percentage buckets may still provide useful reference points, but fixed monthly dollar targets can become difficult to maintain when available income changes from one month to the next.
IF THIS SOUNDS LIKE YOU
Three broad buckets do not give you enough control
If you need to manage individual categories closely, coordinate expenses with specific paychecks, or assign every available dollar, 50/30/20 may feel too broad even when the percentages themselves are reasonable.
THE PRACTICAL TEST
Compare the Rule With Your Actual Budget
You do not need to decide whether 50/30/20 is “good” or “bad” in the abstract. Calculate your current split first, then look at which category is creating the biggest difference from the standard framework.
Start with real take-home income · Adapt the percentages if needed
FREE VERESTLY TOOL
Test the 50/30/20 Rule With Your Own Numbers
Use the Verestly 50/30/20 Budget Calculator to turn your monthly take-home income into three reference amounts, then compare those targets with your actual spending. The goal is not to force a perfect split—it is to see where your current budget differs and why.
- ✓ Calculate the 50%, 30%, and 20% reference amounts automatically.
- ✓ Compare the framework with your real take-home income.
- ✓ Use the results as a starting point for adjustments, not as a pass-or-fail score.
Free · Beginner-friendly · Based on monthly take-home income
TAKE-HOME INCOME
$4,000 per month
NEED MORE DETAIL THAN THREE BUCKETS?
If the 50/30/20 framework feels too broad, use a full beginner budgeting guide to plan individual categories, monthly expenses, and financial priorities in more detail.
COMPARE THE METHODS
How 50/30/20 Compares With Other Budgeting Methods
The 50/30/20 rule solves one budgeting problem especially well: it gives you a simple way to divide income into broad priorities. Other methods provide more detail, focus more on timing, or work better when income changes from month to month.
50/30/20
Broad allocationBest for Seeing the Big Picture
The 50/30/20 framework groups your take-home income into needs, wants, and financial goals. It requires fewer categories and fewer individual spending decisions than more detailed budgeting methods.
- Uses three broad allocation buckets.
- Makes trade-offs easy to see.
- Works well as a benchmark or diagnostic.
ZERO-BASED BUDGETING
Detailed allocationBest for Assigning Every Available Dollar
Zero-based budgeting gives every available dollar a planned purpose. Instead of stopping at three broad buckets, you decide how much should go to individual expenses, spending categories, savings, and other priorities.
- Provides tighter category-level control.
- Requires more active planning and review.
- Makes unassigned money easier to identify.
PAYCHECK BUDGETING
Cash-flow timingBest for Matching Expenses to Paydays
Paycheck budgeting focuses less on percentage targets and more on timing. Each paycheck is assigned to the expenses and priorities that need funding before the next paycheck arrives.
- Connects specific income deposits with upcoming expenses.
- Can make short-term cash flow easier to manage.
- Can be combined with broader allocation frameworks.
IRREGULAR-INCOME BUDGETING
Variable incomeBest for Income That Changes Month to Month
When income fluctuates, a budgeting system needs to account for uncertainty before applying fixed dollar targets. Percentages can still provide useful reference points, but the underlying income plan needs more flexibility.
- Starts with a realistic income-planning assumption.
- Prioritizes required expenses before optional spending.
- Adjusts allocations as actual income becomes known.
KEEP THE PURPOSE IN MIND
You Do Not Have to Use Only One Budgeting Method
You might use 50/30/20 to evaluate your overall allocation, paycheck budgeting to manage timing, or a more detailed method when individual categories need closer control. The useful distinction is what problem each method helps you solve.
AVOID THESE PITFALLS
Common 50/30/20 Budget Mistakes
Most problems with the 50/30/20 rule come from applying the percentages too rigidly, classifying expenses inconsistently, or using targets that do not reflect the money actually available.
Using Gross Income Instead of Take-Home Pay
Building the percentages around gross salary can create category targets based on money that is not actually available for monthly spending and saving.
Start with the income that is actually available after taxes and required payroll deductions.
Treating Every Fixed Expense as a Need
An expense is not automatically necessary just because it recurs every month. Subscriptions, premium services, and other discretionary costs can still be wants.
Classify expenses by their purpose and necessity, not simply by whether they are recurring.
Treating Every Need as Completely Inflexible
Some categories are necessary while still containing choices. Housing, transportation, food, and phone costs can include both essential and discretionary elements.
Recognize the underlying need while separating any premium, convenience, or lifestyle component where useful.
Calling the Budget a Failure When the Split Is Different
A 58/24/18 budget is not automatically wrong simply because it does not match 50/30/20 exactly.
Use the difference to understand what is putting pressure on your budget and where flexibility exists.
Assuming Wants Are Always the Main Problem
Discretionary spending can create pressure, but some households are constrained primarily by housing, transportation, childcare, healthcare, or other necessary costs.
Identify the category actually driving the imbalance before deciding what needs to change.
Treating 20% as a Universal Savings Requirement
The 20% bucket is part of the framework, not a universal rule that every household can or should meet in every month.
Use the percentage as a reference point and adapt your allocation to current income, obligations, and priorities.
FREQUENTLY ASKED QUESTIONS
50/30/20 Budget Rule FAQs
These answers cover the most common questions about applying the framework to real income, expenses, debt, and savings goals.
Is the 50/30/20 rule based on gross or net income?
It is generally applied to take-home pay rather than gross salary. The framework works best when the percentages are based on money that is actually available for monthly allocation.
Does rent count as part of the 50% needs category?
Yes. Housing is generally a need, so rent or a mortgage payment typically belongs in that bucket along with other required housing costs.
Are groceries a need or a want?
Basic groceries generally fit under needs. Restaurant meals, takeout, delivery, and other discretionary food spending usually fit more naturally under wants.
Where do minimum debt payments go?
Required minimum payments are current obligations and should be treated as part of the amount your monthly budget must cover. Additional payments above the minimum can be treated as progress toward a financial goal.
What if I cannot save 20%?
Start with the amount your current budget can realistically support and identify why the standard target does not fit. If necessary expenses already consume most of your take-home income, the issue may not be discretionary spending.
Do the percentages have to be exact every month?
No. Actual spending changes from month to month. The percentages are more useful as planning and review reference points than as a requirement that every month finish at exactly 50%, 30%, and 20%.
CONTINUE YOUR JOURNEY
Where to Go Next
The 50/30/20 rule is only one way to organize a budget. Your next step depends on whether you need broader budgeting guidance, a more detailed monthly plan, or a method that better matches how your income arrives.
BUILD THE FOUNDATION
Learn the Full Budgeting Process
Choose this path if you want to understand budgeting beyond percentage rules and see how income, categories, spending, priorities, and adjustments fit together.
BUILD YOUR OWN PLAN
Create a Budget Around Your Real Numbers
Use this path if you understand the 50/30/20 framework but need a practical budget built around your own income, categories, obligations, and spending priorities.
PLAN THE MONTH
Decide Where Your Money Should Go Before the Month Starts
Choose this path if your main challenge is turning income into a workable monthly plan before bills, spending, and financial goals begin competing for the same money.
USE A DIFFERENT METHOD
Explore a Budgeting Method That Matches Your Situation
If three broad percentage buckets are not enough, a more detailed method may fit better. Zero-based budgeting, paycheck budgeting, and irregular-income budgeting solve different planning problems.
WANT TO RUN THE NUMBERS AGAIN?
Compare the 50/30/20 Framework With Your Actual Income
Return to the calculator whenever your income, housing, transportation, childcare, debt obligations, or other major expenses change. Your useful budget split can change with them.
SOURCES & METHODOLOGY
How We Built This Guide
This guide uses primary government sources to verify how the 50/30/20 framework is described, how budgeting categories are applied, and how current household spending pressures can affect whether percentage targets are realistic. Verestly treats 50/30/20 as an educational budgeting framework rather than a universal spending rule.
LAST REVIEWED
September 2026
We reviewed this guide for accuracy, source quality, budgeting terminology, calculation consistency, and clear separation between the original 50/30/20 framework and Verestly's educational adaptation guidance.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical budgeting systems, and tools that help readers make more informed decisions with the money available to them.
View author profile →VERESTLY NEWSLETTER
Build a Budget That Works With Real Life
Get practical budgeting guides, financial tools, and beginner-friendly resources designed to help you allocate income, understand trade-offs, and adjust your plan as life changes.
- Practical budgeting education
- New calculators and financial tools
- Flexible, beginner-friendly money systems
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Budgeting Guides
Continue with practical guides that help you build, organize, and adjust a budget around your real income and expenses.