
Debt Snowball vs. Debt Avalanche: Which Payoff Method Is Better?
Both methods help you decide where to send extra debt payments, but they prioritize different things. The debt snowball starts with your smallest balance, while the debt avalanche starts with your highest interest rate.
Snowball prioritizes momentum. Avalanche prioritizes interest cost.
If your main goal is to reduce interest, the debt avalanche generally has the mathematical advantage when the other repayment conditions are the same. If paying off a smaller account sooner would help you stay engaged with your plan, the debt snowball may be a reasonable alternative.
Debt Snowball
Smallest balance first
Keep making required payments on your other debts and direct your extra money toward the debt with the smallest balance.
Debt Avalanche
Highest interest rate first
Keep making required payments on your other debts and direct your extra money toward the debt with the highest interest rate.
There is no universal winner. The better method depends on whether you prioritize minimizing interest or reaching smaller payoff milestones sooner—and which approach you can realistically maintain.
Same goal. Different payoff order.
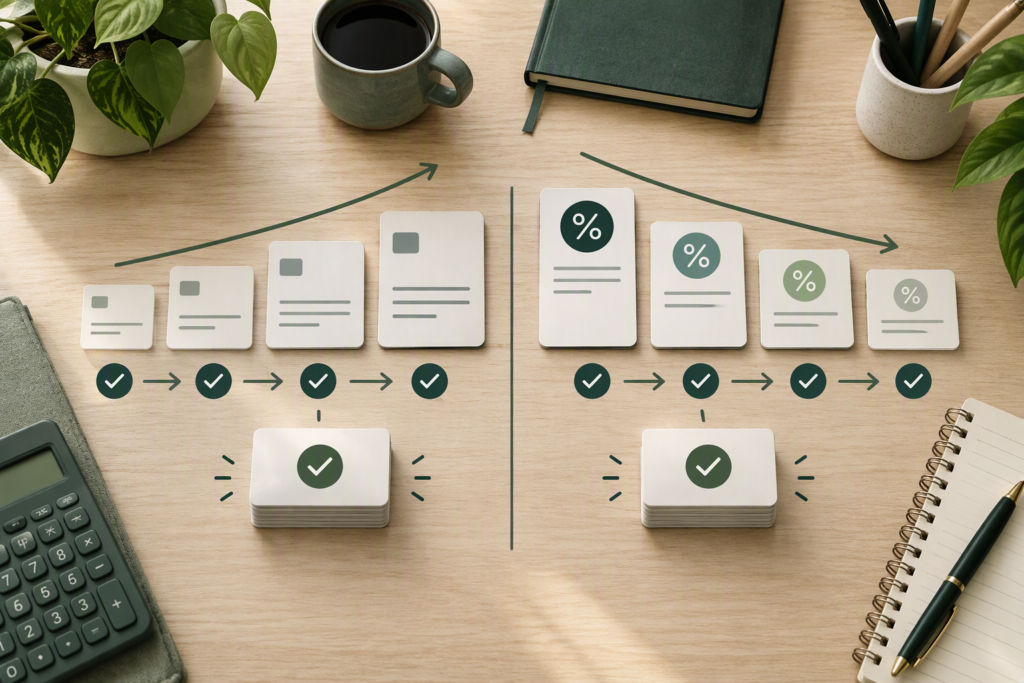
SIDE-BY-SIDE COMPARISON
Debt Snowball vs. Debt Avalanche at a Glance
Both methods use the same basic idea: make the required payments on your debts, then direct extra money toward one priority balance. The difference is how that priority is chosen.
| Compare | Debt Snowball | Debt Avalanche |
|---|---|---|
| First priority | Smallest balance | Highest interest rate |
| Main objective | Reach an account payoff sooner | Reduce interest cost |
| Main advantage | Earlier visible progress | Usually lower total interest |
| Main trade-off | May cost more in interest | First payoff may take longer |
| May fit you if | Small wins help you stay consistent | Minimizing borrowing cost is your priority |
Choose by balance if you want the snowball approach.
Choose by interest rate if you want the avalanche approach.
What does not change: you still make the required payments on your other debts. The method determines where your available extra payment goes.
METHOD 1
How the Debt Snowball Method Works
The debt snowball method ranks your debts by balance, from smallest to largest. You focus extra money on the smallest balance first while keeping required payments current on the others.
List your debts by balance
Put the smallest balance first and the largest balance last. Interest rate does not determine the order in this method.
Keep required payments current
Continue making the required payment on every debt while sending your available extra payment to the smallest balance.
Roll the payment forward
When the smallest debt is paid off, redirect the money you were sending to it toward the next-smallest balance.
SIMPLE EXAMPLE
Snowball follows the balance, not the APR
Example balances are for illustration only. The actual payoff time and interest cost depend on your balances, APRs, payments, fees, and whether new charges are added.
WHEN SNOWBALL MAY FIT
The snowball method may appeal to you if seeing accounts disappear sooner helps you stay engaged with your payoff plan, even if another payoff order could reduce more interest.
METHOD 2
How the Debt Avalanche Method Works
The debt avalanche method ranks your debts by interest rate, from highest to lowest. You direct extra money toward the highest-rate debt while keeping required payments current on the others.
List your debts by interest rate
Put the debt with the highest APR or interest rate first. Balance size does not determine the order.
Target the highest-rate debt
Make the required payments on your other debts and apply your available extra payment to the account charging the highest rate.
Move to the next-highest rate
After the first debt is paid off, redirect that payment toward the remaining debt with the next-highest rate.
SIMPLE EXAMPLE
Avalanche follows the rate, not the balance
This example is for illustration only. Actual interest costs depend on your rates, balances, payment amounts, fees, timing, and whether new charges are added.
WHY THIS CAN SAVE INTEREST
Higher-rate debt generally costs more to carry for the same amount of time. Paying it down first can reduce the amount of interest that accumulates compared with prioritizing a lower-rate balance.
THE TRADE-OFF
Your highest-rate debt may also have a large balance, so it can take longer to reach your first fully paid-off account. That is the main behavioral trade-off compared with snowball.
SEE THE DIFFERENCE
Same Debts, Two Different Payoff Orders
The easiest way to understand snowball versus avalanche is to apply both methods to the exact same debts.
EXAMPLE DEBT LIST
$14,300 total balance
DEBT SNOWBALL
Smallest balance first
-
1Credit Card A $900 · 18% APR
-
2Personal Loan $2,400 · 11% APR
-
3Credit Card B $4,200 · 27% APR
-
4Credit Card C $6,800 · 21% APR
The 11% loan moves ahead of the 27% card because its balance is smaller.
DEBT AVALANCHE
Highest interest rate first
-
1Credit Card B $4,200 · 27% APR
-
2Credit Card C $6,800 · 21% APR
-
3Credit Card A $900 · 18% APR
-
4Personal Loan $2,400 · 11% APR
The $4,200 card moves to the front because its 27% APR is the highest rate.
WHAT ACTUALLY CHANGED?
The debts, balances, and rates stayed exactly the same. Only the order receiving the extra payment changed. That ordering decision creates the main financial and behavioral difference between the two methods.
This comparison illustrates payoff order only. It does not predict payoff time or total interest. Those results depend on payment amounts, interest calculations, fees, timing, and future charges.
COST COMPARISON
Which Method Usually Saves More Money?
If your goal is to minimize interest, the debt avalanche generally has the advantage because it targets the highest-rate debt first.
WHY THE ORDER MATTERS
Higher-rate debt is usually more expensive to carry
When balances remain unpaid, interest continues to accrue according to the account terms. By attacking the highest rate first, avalanche reduces the amount of debt exposed to the most expensive borrowing cost.
Snowball can still work, but it may leave a high-interest balance outstanding longer while you eliminate smaller debts first.
Assuming the same debts, payment amounts, and no new borrowing, highest-rate-first generally produces lower total interest than smallest-balance-first.
SIMPLE RATE EXAMPLE
A higher APR creates more interest pressure
Higher-rate balance
Lower-rate balance
If all else were equal, directing extra money to the 27% debt would usually reduce interest more effectively than sending that same extra payment to the 11% debt.
“Saves more” does not mean a guaranteed dollar amount
Your actual interest depends on balances, APRs, payment timing, fees, account terms, promotional rates, and whether you add new charges. Different accounts may also calculate interest differently.
MOTIVATION VS. MATH
Which Method Is Easier to Stick With?
The mathematically cheaper method is not automatically the easiest one to follow. Your payoff plan also has to survive real life.
SNOWBALL
Progress can feel faster
Paying off a small balance sooner can create an early milestone. For some people, closing an account helps make the plan feel more tangible and easier to continue.
AVALANCHE
Progress can feel slower at first
If your highest-rate debt also has a large balance, it may take longer to reach the first payoff milestone even while the strategy is reducing interest more efficiently.
THE PRACTICAL REALITY
Research suggests that small payoff wins can strengthen motivation for some borrowers, but that does not make snowball financially superior. The better plan is the one whose trade-off you understand and can follow consistently.
ASK YOURSELF
What is more likely to keep you moving?
- Do you need an early payoff milestone to stay encouraged?
- Are you comfortable waiting longer for the first account to disappear if it reduces more interest?
- Can your budget support the same extra payment month after month?
MAKE THE DECISION
How to Choose the Right Payoff Method for You
You do not need a perfect method. You need a clear payoff order that fits your priorities and that you can realistically keep following.
PRIORITIZE COST
Choose avalanche if minimizing interest matters most
- You are comfortable ranking debts by interest rate.
- You can stay committed even if the first balance takes longer to disappear.
- Reducing borrowing cost is your main objective.
PRIORITIZE MOMENTUM
Choose snowball if early wins help you stay engaged
- You want to eliminate a smaller balance sooner.
- Visible progress helps you maintain financial habits.
- You understand that this may cost more in interest.
SOMETIMES THE CHOICE IS EASY
What if your smallest debt also has the highest rate?
Then both methods point to the same debt first. You do not need to choose between snowball and avalanche until their recommended payoff orders begin to differ.
CAN YOU SWITCH LATER?
Yes. A payoff method is a planning framework, not a permanent commitment. If your rates, balances, income, or ability to stay consistent change, you can reassess the order.
Simple decision rule: choose avalanche when reducing interest is your top priority; choose snowball when earlier account payoffs are more likely to help you remain consistent.
AVOID THESE PITFALLS
Common Snowball and Avalanche Mistakes
Choosing the method is only part of the plan. A few common mistakes can undermine either strategy.
Skipping required payments on other debts
Your extra payment goes to one priority debt, but the required payments on your other accounts still need attention.
Continuing to add new balances
New borrowing can offset the progress you are making, especially if new charges carry high interest rates.
Sending every available dollar to debt
A plan with no room for essential expenses or unexpected costs may force you to borrow again when something changes.
Ignoring changes in rates or balances
A variable APR, promotional rate ending, new fee, or major balance change can alter which debt should be prioritized.
Useful reset rule: when your finances change, review the plan rather than abandoning it. You can adjust the extra payment, change the target debt, or switch methods if the new order makes more sense.
PUT IT INTO ACTION
Your Simple Debt Payoff Action Plan
You do not need to overthink the decision. Gather the numbers, choose the trade-off you prefer, and give your extra payment one clear job.
List every debt
Record the balance, interest rate, and required payment for each account.
Choose your priority rule
Rank smallest balance first for snowball or highest interest rate first for avalanche.
Set a realistic extra payment
Choose an amount your monthly cash flow can support without neglecting essential expenses.
Review and adjust
Recheck the plan when balances, rates, income, or expenses change.
FREQUENTLY ASKED QUESTIONS
Debt Snowball vs. Debt Avalanche FAQ
Is debt snowball or debt avalanche faster?
It depends on what “faster” means. Snowball may eliminate your first account sooner, while avalanche may reduce interest more efficiently. Total payoff time depends on your balances, rates, and payments.
Can I combine snowball and avalanche?
Yes. You can use a hybrid approach, such as paying off one very small balance first and then switching to highest-interest-first. The trade-off is that changing the order can change total interest cost.
Should I pay off the debt with the highest payment first?
Not necessarily. Snowball ranks debts by balance, while avalanche ranks them by interest rate. Monthly payment size is a separate factor.
What if I cannot afford all of my minimum payments?
Snowball versus avalanche may not be the immediate decision. Focus first on essential expenses, accounts at risk of serious consequences, and options for making required payments manageable.
Do I need to stick with one method until all debt is gone?
No. You can reassess your payoff order when your balances, rates, income, or priorities change. What matters is understanding the trade-off before changing strategies.
RELATED LEARNING
Keep Building Your Debt Payoff Plan
Use these guides to understand the broader payoff process and the borrowing costs behind your balances.
How to Get Out of Debt: A Step-by-Step Beginner’s Plan
Build the broader system around your payoff method, from organizing debts to tracking progress.
Read the guide → UNDERSTAND COSTHow Credit Card Interest Works
Learn why carrying a revolving balance can increase borrowing costs over time.
Learn about interest → UNDERSTAND APRUnderstand Credit Card APR
See what APR represents and why it matters when comparing which balance to prioritize.
Understand APR →SOURCES & METHODOLOGY
How We Researched This Guide
This guide compares the debt snowball and debt avalanche methods using consumer guidance from the Consumer Financial Protection Bureau and behavioral research related to debt repayment and motivation. Examples are educational illustrations and should not be treated as predictions of individual payoff results.
Consumer Financial Protection Bureau
How to reduce your debt
Supports: the distinction between prioritizing the highest-interest-rate debt and prioritizing the smallest balance, including their primary advantages and trade-offs.
View CFPB source ↗Consumer Financial Protection Bureau
Your Money, Your Goals: Reducing Debt Worksheet
Supports: ranking debts by interest rate or balance, assigning an extra payment to a target debt, and redirecting payments as debts are eliminated.
View CFPB worksheet ↗Consumer Financial Protection Bureau
What should I do if I can’t pay my credit card bills?
Supports: the guidance that people who cannot afford required credit card payments should address that problem promptly rather than treating payoff order as their only financial decision.
View CFPB guidance ↗Alexander L. Brown & Joanna N. Lahey · Journal of Marketing Research
Small Victories: Creating Intrinsic Motivation in Task Completion and Debt Repayment
Supports: the discussion of smaller completed tasks, visible progress, and motivation in debt-repayment settings.
View research ↗Methodology note: payoff examples in this article are designed to explain repayment order and trade-offs. Actual interest charges, payoff dates, and savings can vary based on balances, APRs, account terms, fees, payment timing, promotional rates, and future borrowing.
LAST REVIEWED
October 7, 2026
This article was reviewed for source accuracy, debt-payoff terminology, consumer guidance, calculation assumptions, search-intent alignment, and beginner-friendly educational clarity.
WRITTEN BY
Edvaldo Ribeiro
Author · Verestly
Edvaldo Ribeiro writes practical personal-finance education for Verestly with a focus on helping beginners understand everyday money decisions without unnecessary jargon or product pressure.
His Verestly content covers topics such as budgeting, saving, debt management, credit, banking, investing, taxes, and retirement, with an emphasis on clear explanations, realistic examples, and actionable next steps.
EDITORIAL DISCLOSURE
Independent, Educational Personal-Finance Content
Verestly creates educational content to help readers understand financial concepts and make more informed decisions. This article does not provide individualized financial, legal, tax, or credit advice.
The debt snowball and debt avalanche are presented as educational repayment frameworks. Verestly does not guarantee that either method will produce a specific payoff date, dollar amount of interest savings, credit score change, approval outcome, or other financial result.
Examples and calculations may use simplified assumptions to make concepts easier to understand. Actual outcomes depend on factors such as balances, APRs, payment timing, lender or card issuer terms, fees, promotional rates, income changes, and future borrowing.
Editorial conclusions are based on the topic, available evidence, authoritative sources, and the needs of beginner readers—not on promoting a particular debt payoff method, lender, credit card, or financial product.
THE VERESTLY NEWSLETTER
Build a Better Money System, One Step at a Time
Get practical guides, financial tools, and beginner-friendly
resources designed to help you make clearer money decisions.
✓ Practical financial education
✓ New calculators and tools
✓ Actionable money systems
No spam. Just practical money guidance. Unsubscribe anytime.

RELATED ANSWERS
Keep Exploring
Continue with three closely related guides selected to deepen your understanding.