BUDGETING · PRACTICAL GUIDE
How to Review Your Budget at the End of the Month
Learn how to compare your budget with what actually happened, understand meaningful differences, and make realistic adjustments for the month ahead.
QUICK ANSWER
The Short Answer
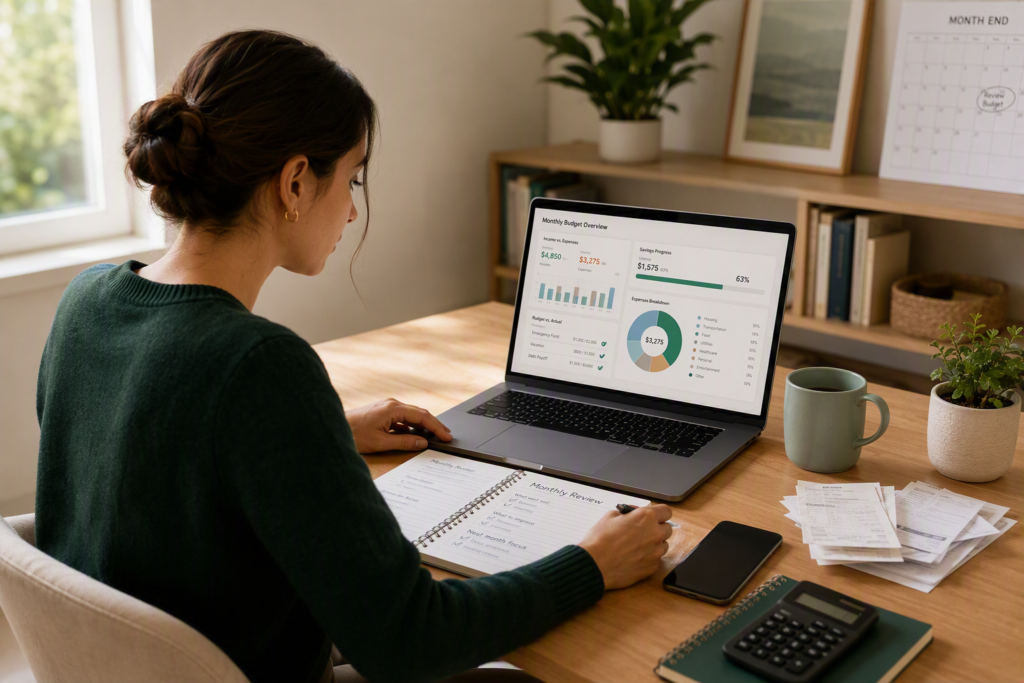
Reviewing your budget at the end of the month means comparing what you planned with what actually happened, understanding the most important differences, and deciding what should change in the next month's plan. The goal is not perfect accuracy. It is to make your budget more realistic and useful over time.
What You'll Do
- ✓ Gather your actual income, spending, and bills for the month.
- ✓ Compare planned amounts with what you actually received and spent.
- ✓ Identify why the most meaningful differences happened.
- ✓ Carry only the useful adjustments into next month's budget.
WHY THIS MATTERS
Why Reviewing Your Budget Makes the Next Month More Useful
A budget is based on estimates and priorities made before the month unfolds. Reviewing the results afterward helps you replace assumptions with real information and build a more realistic plan for what comes next.
Even a carefully planned budget will not match reality perfectly. Bills can change, prices can move, income may differ from what you expected, and irregular expenses can appear during the month.
Without a review, it is easy to carry the same inaccurate estimates into the next budget. A category that is repeatedly too low may look like a spending problem when the original allocation was simply unrealistic.
A monthly budget review helps you separate temporary surprises from recurring patterns so you can decide what actually needs to change instead of automatically cutting every category that went over plan.
PARENT GUIDE Budgeting for Beginners: A Complete Step-by-Step Guide →KEY IDEA
A budget review is not a pass-or-fail test. It is a way to understand why your actual results differed from the plan and use that information to make the next budget more realistic.
STEP-BY-STEP METHOD
How to Review Your Budget at the End of the Month
A useful review compares your original plan with what actually happened, explains the most important differences, and turns those lessons into a more realistic budget for the next month.
STEP 1
Gather Your Actual Income and Spending
Start with what actually happened during the month. Review checking-account transactions, credit card activity, recurring bills, cash purchases you recorded, and the income that actually reached your accounts.
Also look for transfers and irregular expenses so you do not mistake money moved between accounts for new spending or overlook costs that do not happen every month.
PRACTICAL TIP
Review the full month before judging any category. A missing transaction or forgotten annual charge can make your budget appear less accurate than it really was.
STEP 2
Compare Planned Amounts With Actual Results
Put your original budget beside the actual numbers and compare income and spending category by category. The difference between what you planned and what actually happened is often called a variance.
STEP 3
Identify the Differences That Actually Matter
You do not need to investigate every small difference. Focus on variances large enough to affect the overall plan or categories that keep missing their target month after month.
- Income that was higher or lower than expected
- Categories with meaningful overspending
- Categories that repeatedly come in below plan
- Expenses that were missing from the original budget
- Costs that appeared at a different time than expected
STEP 4
Ask Why Each Meaningful Variance Happened
A number above or below plan does not explain the cause. Before changing next month's budget, identify what actually produced the difference.
- You spent differently from what you intended
- The original estimate was unrealistic
- Prices changed
- An expense happened earlier or later than expected
- An irregular event changed the month
- Your income differed from the original plan
IMPORTANT
Going over budget does not automatically mean the spending was unnecessary. Sometimes the category itself was simply set too low.
STEP 5
Separate One-Time Events From Recurring Patterns
One unusual month does not always justify rewriting the budget. Look at whether the difference is likely to happen again before changing the next plan.
A temporary utility spike may need no permanent adjustment. But if groceries have exceeded the budget for several months, the planned amount may no longer reflect reality.
PRACTICAL TIP
Repeated surprises are often a signal that the budget needs a new category, a better estimate, or a different timing assumption.
STEP 6
Carry the Useful Adjustments Into Next Month
Finish the review by deciding what should actually change. Keep the parts of the budget that worked, update estimates that were consistently unrealistic, and prepare for known expenses coming up.
- Which category estimates need to change?
- Which differences were only temporary?
- Are any recurring expenses still missing?
- Did income assumptions need to be updated?
- What known expenses should be added next month?
REAL-LIFE EXAMPLE
What a Monthly Budget Review Can Look Like
A budget review becomes more useful when you look beyond whether a category was simply over or under plan and identify what caused the difference.
EXAMPLE SCENARIO
Taylor Reviews a $4,800 Monthly Budget
Taylor reaches the end of the month and compares the original spending plan with the actual results. Several categories were different from the plan, but each difference has a different cause.
| Category | Difference |
|---|---|
| Housing | $0 |
| Utilities | +$60 |
| Groceries | +$70 |
| Transportation | -$45 |
| Dining out | +$85 |
| Net difference | +$170 |
| Actual spending | $4,370 |
WHAT THIS SHOWS
The Same Over-Budget Result Can Lead to Different Decisions
Utilities were $60 above plan because of an unusually high bill. Taylor does not immediately raise the category because the change appears temporary.
Groceries were $70 above plan, but recent months show the same pattern. That suggests the original grocery estimate may be too low. Dining out, however, increased because of several unplanned meals, so Taylor chooses to keep that target unchanged next month.
SIMPLE MATH
THE TAKEAWAY
A useful budget review does not stop at the variance. It asks why the number changed before deciding what should change in the next budget.
This example is illustrative. Your income, expenses, category amounts, and reasons for budget differences will be different.
ADAPT THE REVIEW
What Should You Do With What the Review Reveals?
Not every budget difference requires the same response. The right adjustment depends on whether the change was temporary, recurring, caused by income, or driven by expenses that leave little room to move.
RECURRING VARIANCE
If the Same Category Keeps Missing Its Target
A repeated difference is stronger evidence that the original budget amount may no longer reflect reality. Review recent months before deciding whether the category should be increased, reduced, or reorganized.
ONE-TIME EXPENSE
If an Unusual Expense Changed the Month
A repair, medical bill, annual charge, or seasonal cost may push one month above plan without changing your normal spending pattern. Before permanently changing the budget, decide whether that expense is likely to happen again.
IRREGULAR INCOME
If Your Income Was Different From What You Planned
If income changes from month to month, repeated budget variances may be caused by the income assumption rather than the spending plan itself. Use the review to compare expected and actual income before adjusting individual categories.
LIMITED FLEXIBILITY
If Essential Costs Are Already Using Most of Your Income
The review may show that housing, transportation, food, healthcare, caregiving, or other necessary expenses leave very little room for adjustment. In that situation, repeatedly cutting small flexible categories may not resolve the underlying gap.
NOT SURE WHAT TO CHANGE?
Start with the differences that repeat or materially affect the whole budget. Leave temporary anomalies alone unless you have a reason to expect them again, and carry only the useful changes into next month's plan.
NEXT STEP
Turn This Month's Review Into a Better Plan for Next Month
Once you know what changed and why, use those findings to update the next monthly budget. Keep the estimates that worked, adjust recurring differences, and add known expenses before the new month begins.
- ✓ Carry forward category amounts that already match reality.
- ✓ Adjust estimates that repeatedly came in too high or too low.
- ✓ Prepare for known bills and irregular expenses before they arrive.
Step-by-step · Beginner-friendly · Based on what you learned this month
MONTHLY REVIEW
End of Month
Example review summary
KEEP SEEING THE SAME PROBLEM?
If the same budget issues return month after month, review the broader reasons your spending plan may keep falling short.
TAKE ACTION
Your End-of-Month Budget Review Action Plan
You do not need to analyze every dollar in detail. Focus on the differences that matter, understand what caused them, and carry only the useful changes into next month's budget.
START HERE
Gather the month
Collect Your Actual Numbers
Bring together the income, transactions, bills, and other spending that actually occurred during the month before you compare anything with the original budget.
- Confirm the income that actually arrived.
- Review account and card transactions.
- Add recorded cash spending and recurring bills.
- Separate transfers from actual expenses.
REVIEW
Compare and explain
Find the Variances That Matter
Compare planned and actual amounts, then focus on the differences large enough to affect the plan or patterns that keep appearing from one month to the next.
- Identify meaningful planned-versus-actual differences.
- Ask whether each difference was temporary or recurring.
- Look for unrealistic estimates or missing expenses.
- Check whether income or bill timing affected the result.
NEXT MONTH
Adjust with purpose
Update Only What the Review Supports
Keep the parts of the budget that worked. Change estimates only when the review gives you a reason, and account for any known expenses or income changes before the next month begins.
- Keep realistic category amounts unchanged.
- Adjust categories with repeated variances.
- Add known irregular or previously missed expenses.
- Update income assumptions when circumstances changed.
QUICK CHECK
A Useful Budget Review Should Answer One Simple Question
Can you explain the most important differences between your plan and your actual results—and what, if anything, you will change next month?
COMMON MISTAKES
Mistakes That Make a Budget Review Less Useful
A monthly review should help you understand what happened and improve the next plan. These common mistakes can turn it into either a judgment exercise or a set of changes that do not solve the real problem.
MISTAKE
Treating Every Over-Budget Category as a Failure
Spending more than planned does not automatically mean you made a poor decision. The estimate may have been too low, prices may have changed, or a necessary expense may have been higher than expected.
BETTER APPROACH
Ask why the variance happened before deciding whether the category, the spending, or nothing at all needs to change.
MISTAKE
Changing the Budget Because of One Unusual Month
A repair, medical bill, annual fee, seasonal expense, or temporary price spike can distort one month without changing your normal spending pattern.
BETTER APPROACH
Separate one-time events from recurring patterns before permanently changing category amounts.
MISTAKE
Forcing Actual Spending to Match the Original Plan
Rewriting or ignoring actual spending because the number looks uncomfortable makes the review less accurate and gives you a weaker starting point for the next month.
BETTER APPROACH
Record what actually happened first. Then decide whether your behavior, your estimate, or your category structure needs adjustment.
MISTAKE
Looking Only at Spending and Ignoring Income
A budget can miss its targets because the amount of income available changed, not because spending suddenly became unreasonable.
BETTER APPROACH
Compare expected and actual income before changing spending categories, especially when your earnings vary from month to month.
MISTAKE
Making Too Many Changes at Once
Rebuilding the entire budget after every imperfect month can make it difficult to tell which adjustments actually improved the plan. It can also turn a temporary variance into a permanent assumption.
BETTER APPROACH
Keep what worked, change the few assumptions supported by the review, and test those adjustments in the next monthly budget.
REMEMBER
A useful budget review is not about proving that the original plan was right. It is about learning enough from the actual results to make the next plan more realistic.
FREQUENTLY ASKED QUESTIONS
Common Questions About Reviewing Your Budget
These questions cover the situations that most often come up when you compare a monthly budget with what actually happened and decide what should change next.
How often should I review my budget? +
A full review at the end of each monthly budget cycle is a practical starting point. You can also check your spending during the month if that helps you make adjustments before the month is over.
The important part is creating a repeatable feedback loop between what you planned, what actually happened, and what you will do differently next time.
What if I go over budget every month? +
Look for the pattern before assuming the answer is simply to spend less. A category may be underestimated, recurring expenses may be missing, income may vary, or essential costs may leave less flexibility than the budget assumes.
If the same problem continues after several adjustments, the issue may require a broader review of the spending plan rather than another small category cut.
Explore why your budget may keep falling short →Should I change a category every time I go over budget? +
Not necessarily. One unusual month may not justify a permanent change. A higher utility bill, repair, medical expense, or other temporary event can create a variance without changing your normal monthly pattern.
Repeated differences across several months are stronger evidence that the planned amount should be reconsidered.
What if I spent less than I planned? +
First identify why the category came in below plan. You may have intentionally spent less, overestimated the original amount, received a lower bill, or simply delayed an expense into the next month.
Do not automatically reduce the category until you know whether the lower amount is likely to continue.
Do I need to track every purchase to review my budget? +
Not necessarily. You need enough information to understand where your money went and compare actual results with the plan. Some people track individual transactions, while others rely mainly on account records and category totals.
Use a level of detail you can realistically maintain without making the review harder than it needs to be.
What should I do after I finish the monthly review? +
Carry the useful findings into the next month's plan. Keep category amounts that still reflect reality, update estimates supported by recurring patterns, and account for known expenses or income changes before the new month starts.
Plan your next monthly budget →KEEP LEARNING
Continue With the Next Most Useful Guides
These guides help you turn what you learned during the review into a more realistic and easier-to-maintain spending plan.
How to Plan a Monthly Budget Before the Month Begins
Use this month's actual results to build a more realistic spending plan before the next month starts.
Read the guide → IMPROVE THE STRUCTUREBest Budget Categories for a Simple Monthly Spending Plan
Reorganize categories that are too broad, too narrow, or repeatedly difficult to manage.
Read the guide → FIX RECURRING PROBLEMSWhy Your Budget Keeps Failing—and How to Fix It
Diagnose broader problems when the same budget issues keep returning despite repeated adjustments.
Read the guide →WANT THE COMPLETE SYSTEM?
Return to the main budgeting guide for the full beginner framework covering income, expenses, planning, tracking, adjustment, and ongoing budget management.
SOURCES & METHODOLOGY
How We Verified This Guide
Verestly prioritizes primary government and regulatory sources when verifying budgeting guidance. For this guide, we reviewed official consumer-finance resources covering monthly budget reviews, actual spending, spending records, and realistic budget adjustments.
LAST REVIEWED
September 2026
This guide was reviewed for source accuracy, budgeting terminology, search-intent ownership, practical clarity, and consistency with Verestly's current editorial standards.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on practical systems, clear explanations, and actionable financial tools.
View author profile →VERESTLY NEWSLETTER
Get Practical Money Guides and Tools
Join Verestly for beginner-friendly financial education, new tools, practical systems, and resources you can actually use.
Free resources · Beginner-friendly · Unsubscribe anytime
RELATED GUIDES
Continue Learning
Explore three additional guides selected to help you turn your monthly review into a stronger budgeting system.