MONEY BASICS · BEGINNER GUIDE
Personal Finance for Beginners: 10 Simple Steps to Manage Your Money
Learn how to understand what comes in, where your money goes, what you owe, and what you want your money to accomplish—then use 10 practical steps to organize spending, build savings, understand debt and credit, and prepare for longer-term goals.
QUICK ANSWER
The 10 Steps at a Glance
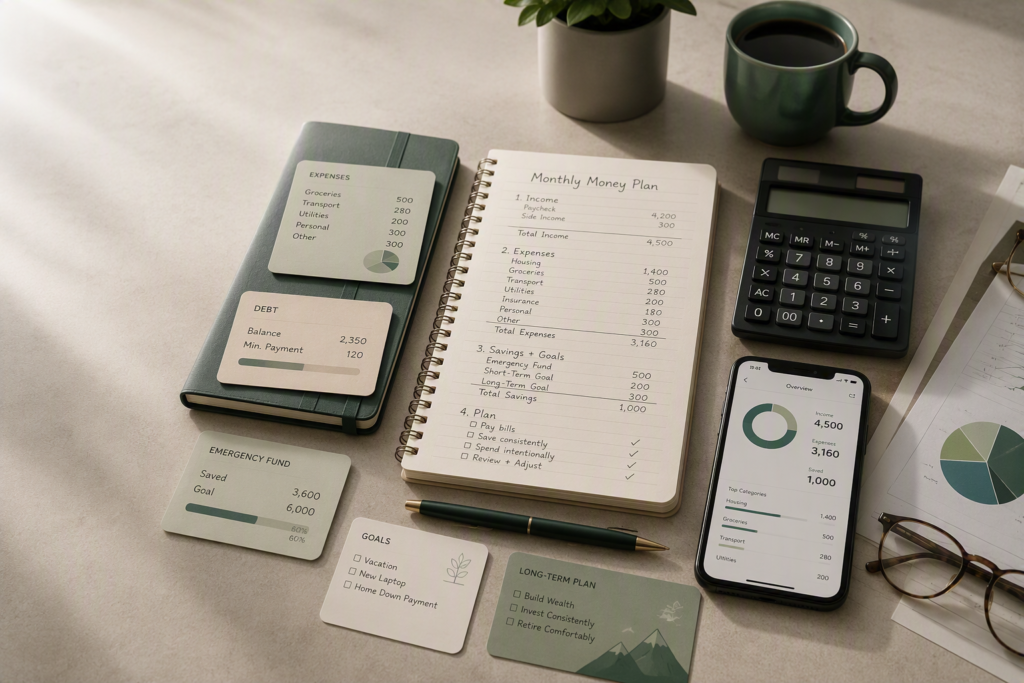
Managing your money starts with understanding where you stand, what comes in, where it goes, and what you want your money to accomplish. From there, you can build a spending plan, create financial buffers, understand debt and credit, prepare for longer-term goals, and review your finances as your circumstances change.
These 10 steps are a Verestly educational framework, not a universal financial order. Some steps may overlap or happen differently depending on your situation.
Your Beginner Money Map
- 1 Take a snapshot of where your finances stand.
- 2 Know your actual take-home income.
- 3 Understand where your money is going.
- 4 Separate needs from wants.
- 5 Set financial goals.
- 6 Build a basic spending plan.
- 7 Create a financial buffer for unexpected expenses.
- 8 Understand your debt and credit.
- 9 Prepare for long-term financial goals.
- 10 Review and adjust your finances regularly.
SEE THE BIGGER PICTURE
How the Main Parts of Personal Finance Fit Together
Personal finance becomes easier to understand when you stop treating budgeting, saving, debt, credit, and investing as separate problems. Each area has a different job, and together they form the system you use to manage money.
Income and Spending
Income tells you how much money is available. Spending shows where that money is currently going and which obligations are already competing for it.
Core question: How much comes in, and where does it go?
Budgeting and Saving
Budgeting helps decide what available money should do next. Saving prepares money for future expenses, goals, and financial shocks.
Core question: What should your money do before it is spent?
Debt and Credit
Debt represents money you already owe. Credit affects how borrowing works and how your borrowing history may influence future financial options.
Core question: What money is already committed, and how does borrowing fit in?
Investing and Retirement
Investing can support longer-term goals by putting money to work while accepting investment risk. Retirement planning focuses on preparing for future income needs.
Core question: What does your money need to accomplish in the future?
No single number tells your whole financial story. If you know which question you are trying to answer, it becomes easier to choose the right financial tool and the right next step.
STEP 1 · KNOW WHERE YOU STAND
Take a Snapshot of Where Your Finances Stand
Before deciding what to change, get a clear picture of what is happening now. You do not need a perfect spreadsheet or a full inventory of everything you own—just enough information to see what comes in, what goes out, what you own, what you owe, and what your money needs to accomplish.
What Comes In?
Identify your take-home income and other reliable sources of money reaching your household.
What Goes Out?
List regular bills, recurring obligations, everyday spending, and important irregular expenses.
What Do You Own?
Note financial accounts and major assets that materially affect your financial picture.
What Do You Owe?
Record debts and other financial obligations that already claim part of your future cash flow.
What Does Your Money Need to Accomplish?
Identify the current priorities, upcoming costs, and future goals competing for your money.
Start with what you already know
Review recent pay information, bank accounts, bills, loan statements, credit card balances, and other records you already have. Your first snapshot does not need to be perfect. Its purpose is to replace assumptions with information you can use.
You may discover a forgotten subscription, an irregular expense that is approaching, or a debt balance you have not checked recently. Those discoveries are useful because they show what deserves attention next.
SIMPLE NET WORTH CHECK
Net worth = assets − liabilities
If someone has $20,000 in relevant assets and $14,000 in liabilities, their net worth is $6,000. Net worth is useful as a snapshot, but it does not tell you everything about cash flow, income stability, or financial goals.
You do not need to value everything you own
A beginner financial snapshot does not require assigning a dollar value to every possession in your home. Focus on financial accounts, major assets, and liabilities that meaningfully affect your financial position.
STEPS 2 & 3 · FOLLOW THE MONEY
Know What Comes In and Where It Goes
Your cash flow shows how money moves into and out of your finances. Before deciding what to change, understand how much usable income you actually receive, how much leaves, and which expenses are shaping the difference.
STEP 2
Know Your Actual Take-Home Income
Your salary or hourly wage is not necessarily the amount available for everyday spending. Gross pay generally refers to earnings before applicable deductions, while take-home pay is the amount that actually reaches you after paycheck deductions.
For day-to-day planning, take-home pay is usually the more useful starting point because it reflects the money you actually have available to work with. If your income changes from month to month, look across several months instead of relying on a single paycheck.
KEY IDEA
Build your everyday money plan around the income that actually reaches you—not just the number listed as your salary or gross pay.
CASH-FLOW CHECK
Compare What Comes In With What Goes Out
Cash flow is the movement of money into and out of your finances over a period of time. Comparing those two sides gives you a quick way to see whether your current pattern is creating room, breaking even, or creating a shortfall.
Money remains available for savings, goals, debt reduction, irregular costs, or other priorities.
There may be little room for unexpected expenses or additional goals without another adjustment.
The gap has to be covered by available cash, savings, additional income, delayed spending, borrowing, or another change.
Negative cash flow does not automatically mean someone is simply spending irresponsibly. A shortfall can come from insufficient income, high fixed costs, medical expenses, debt obligations, temporary income loss, or unexpected costs.
STEP 3
See Where Your Money Is Actually Going
Start with real spending, not what you think you should be spending. Review bank statements, card transactions, bills, receipts, and other account records so your next decisions are based on what is actually happening.
Looking across several months can also reveal costs that are easy to miss when you focus only on one month.
- Recurring expenses: costs that appear regularly, such as rent, subscriptions, insurance, or loan payments.
- Variable expenses: costs that change, such as groceries, fuel, dining out, entertainment, or some utility bills.
- Irregular expenses: costs that do not appear every month, such as annual fees, repairs, gifts, school expenses, or seasonal costs.
THE POINT IS VISIBILITY
Discovering that you spend more than expected does not automatically mean the spending is wrong. It means you now have better information for deciding whether that pattern matches your priorities.
STEPS 4 & 5 · SET YOUR DIRECTION
Separate Needs From Wants and Set Financial Goals
Once you understand your cash flow, the next step is deciding what deserves your money. Distinguishing needs from wants helps reveal flexibility, while clear financial goals give that flexibility a purpose.
STEP 4
Separate Needs From Wants Without Making It a Moral Test
A need generally supports basic living, an important obligation, health, safety, or your ability to earn income. A want generally adds comfort, convenience, enjoyment, or lifestyle value.
The distinction is not always universal. A car may be essential for someone who cannot otherwise reach work and mostly optional for someone with reliable alternatives.
QUESTION 1
Is this expense required or discretionary in my circumstances?
QUESTION 2
If it is a want, is it important enough to keep?
KEY IDEA
A want is not automatically a bad expense. The purpose of the distinction is to understand where you have flexibility when your money cannot support every priority at once.
STEP 5
Give Your Money a Direction
Financial goals turn general intentions into decisions you can act on. A simple Verestly framework is: Goal → Amount → Time → Next Action.
Define What You Want to Accomplish
Name the specific result, such as building savings, replacing a car, reducing a debt, or preparing for a future expense.
Estimate the Money Involved
Give the goal an approximate dollar amount when possible so you can see what the goal may require.
Decide When It Matters
Identify whether the goal needs attention soon or belongs further into the future.
Choose the Next Useful Move
Turn the goal into a concrete action you can take now rather than leaving it as a vague intention.
EXAMPLE — NOT A RECOMMENDATION
VERESTLY PRIORITY CHECK
When Several Goals Compete for the Same Money
You do not automatically need to abandon every goal except one. Use these questions to make the tradeoffs more visible.
-
01
What must be paid?
-
02
What could create a serious problem if ignored?
-
03
What is currently costing me money?
-
04
What goal matters next?
-
05
What belongs to the longer term?
EDUCATIONAL FRAMEWORK
The Verestly Priority Check is a way to organize competing financial priorities—not a universal order of operations. Your obligations, risks, benefits, goals, and household circumstances may lead to a different sequence.
STEP 6 · BUILD A SPENDING PLAN
Build a Spending Plan You Can Actually Use
Once you understand your income, spending, obligations, and goals, you can decide how available money should be used. A spending plan helps make those tradeoffs visible before they become surprises.
EXAMPLE — NOT A RECOMMENDATION
Meet Jordan
Jordan receives $3,400 per month in take-home pay and wants to make room for current obligations, flexible spending, debt payments, savings, and other priorities.
The goal is not to copy Jordan's numbers. It is to see how one change in the plan affects the money available for everything else.
| Monthly take-home pay | $3,400 |
|---|---|
| Core needs and obligations | $2,050 |
| Flexible spending | $650 |
| Debt payments | $300 |
| Savings | $200 |
| Remaining flexibility | $200 |
HOW TO READ THE PLAN
Every Dollar Has to Compete for a Job
COVER
Start With Core Obligations
Housing, essential utilities, food, transportation, required payments, and other important obligations usually have the least flexibility.
PLAN
Account for Flexible Spending
Flexible spending still belongs in the plan. Giving it realistic space can make the overall system easier to maintain.
DIRECT
Include Savings and Other Goals
A spending plan can direct part of available income toward savings, debt goals, upcoming expenses, or other priorities.
TEST
Check Whether the Numbers Fit
If the plan uses more money than Jordan actually receives, something has to change before the plan can work in practice.
ADJUST
Make Tradeoffs Visible
When one cost changes, Jordan can see which other category, goal, reserve, or income source may need to absorb the difference.
THE TRADEOFF
What Happens if One Expense Rises?
Suppose Jordan's insurance increases by $100 per month. That $100 now has to come from somewhere—another spending category, reduced room for a different goal, additional income, or available reserves. The value of the spending plan is that Jordan can see the tradeoff instead of discovering it after the money is gone.
This example is illustrative, not a recommended allocation. Real spending plans depend on income, obligations, household needs, debt, savings, and financial goals.
STEP 7 · PREPARE FOR THE UNEXPECTED
Create a Financial Buffer for Unexpected Expenses
Saving is not only about future purchases. A financial buffer can give you money to respond when an unplanned expense or temporary income disruption appears, reducing the pressure to immediately rely on borrowing or money intended for another goal.
UNEXPECTED REPAIR
An essential car or home repair appears
A vehicle repair, broken appliance, or urgent home problem can create an immediate cash need that was not part of the normal monthly plan.
HEALTH OR FAMILY COST
An unexpected medical or family expense occurs
Even when some costs are covered elsewhere, an unexpected health or family event can still create expenses that need to be handled quickly.
INCOME INTERRUPTION
Your income temporarily drops or stops
A reduction in work hours, delayed payment, job change, or another interruption can create a gap between the money arriving and the bills that still need to be paid.
KNOWN FUTURE COST
The expense is irregular, but you already know it is coming
Annual fees, insurance premiums, school expenses, gifts, and other predictable costs may require saving, but they are not the same as financial emergencies because they can be planned for in advance.
HOW MUCH SHOULD YOU SAVE?
Start With the Risk That Could Disrupt You Most
There is no single emergency-savings amount that fits every household. Income stability, essential expenses, dependents, insurance, existing savings, and other risks can all affect what makes sense for you.
Start with your situation, not a universal savings target
A USEFUL FIRST QUESTION
What unexpected expense would create a serious financial problem for me right now?
FREE VERESTLY TOOL
Turn Your Financial Snapshot Into a Clear Next Priority
Understanding your income, spending, savings, debt, and goals is useful—but those areas can still compete for attention. The Financial Triage Wizard helps you organize the pressure points in your current situation and identify a practical place to focus next.
- ✓ Identify which part of your finances may need attention now.
- ✓ Compare competing priorities without assuming one universal order.
- ✓ Turn a broad money problem into a more manageable next step.
Free · Beginner-friendly · Designed for financial prioritization
FIRST QUESTION
What is creating the most financial pressure right now?
PREFER TO REVIEW THINGS YOURSELF?
Explore Verestly resources and checklists to work through your financial foundation at your own pace.
STEP 8 · UNDERSTAND WHAT YOU OWE
Understand Your Debt and How Credit Fits In
Debt and credit are connected, but they are not the same thing. Start by understanding what you already owe, which payments affect your cash flow, and how credit reports and credit scores relate to your borrowing history.
START WITH DEBT
Know what you oweMake Your Existing Obligations Visible
Debt represents money you already owe and can include credit-card balances, auto loans, student loans, personal loans, mortgages, and other forms of borrowing.
- Record the current balance for each debt.
- Note the required payment and due date.
- Record the interest rate or borrowing cost where applicable.
CONNECT IT TO CASH FLOW
See the monthly effectUnderstand How Debt Claims Future Income
Required debt payments use part of the money available each month. That can reduce the amount left for current expenses, savings, and other financial goals.
- Include required payments in your spending plan.
- Notice which obligations leave the least flexibility.
- Avoid treating every type of debt as if it has the same terms or cost.
UNDERSTAND CREDIT
Borrowing relationshipCredit Is the Arrangement, Not the Debt Itself
Credit is an arrangement that allows you to borrow money or receive something of value now under an agreement to repay according to stated terms.
- Credit describes the borrowing arrangement.
- Debt is the amount or obligation you owe.
- Borrowing terms can affect the total cost of repayment.
KNOW THE DIFFERENCE
Report vs. scoreCredit Reports and Credit Scores Are Different
A credit report contains information about your credit history. A credit score is a numerical prediction based on information contained in credit reports.
- Your credit report contains credit-history information.
- A credit score summarizes information through a scoring model.
- Different models, data, products, or dates can produce different scores.
CHOOSE THE RIGHT DEEPER GUIDE
Specialist next stepMatch the Next Question to the Right Topic
Once you know what you owe and how credit fits into the picture, the next step depends on the problem you are actually trying to solve.
- Use debt guidance for repayment methods and debt-specific decisions.
- Use Credit & Credit Cards guidance for reports, scores, cards, and credit management.
- Keep detailed specialist strategies out of your basic financial overview.
BEGINNER PRIORITY
Start With Clarity Before Choosing a Strategy
You do not need to choose a debt payoff method or optimize a credit score before you understand the accounts involved. First know what you owe, when payments are due, how borrowing affects your cash flow, and which deeper question you need answered next.
STEPS 9 & 10 · LOOK AHEAD
Prepare for the Future and Keep Your System Working
Once the basics are visible, personal finance extends beyond this month. Longer-term goals may involve saving, investing, and retirement planning, while a simple review routine helps your financial system adapt as your life changes.
Understand the Different Roles of Saving and Investing
Saving generally emphasizes access and stability for nearer-term needs. Investing involves accepting investment risk in pursuit of potential returns over time, and investments can lose value.
Money you may need soon presents a different planning problem from money intended for a goal many years away.
Let the Goal and Time Horizon Guide the Next Question
Your time horizon is the amount of time before you expect to need money for a financial goal. It can influence the types and amount of investment risk that may be appropriate to consider, along with your risk tolerance and the purpose of the money.
Retirement is one example of a longer-term goal that may require planning for future income needs when employment income decreases or stops.
Use a Simple Review Routine
Income, bills, goals, savings, and debt can all change. A financial plan works better when you have a repeatable way to notice those changes and respond.
Check → Compare → Adjust → Continue.
Adjust the Plan Instead of Starting Over
A difficult month, new bill, income change, or unexpected expense does not automatically mean the whole system failed. Compare what actually happened with what you expected and update the plan where needed.
Automation can reduce repeated work, but it does not remove the need to review your finances when circumstances or priorities change.
FREQUENTLY ASKED QUESTIONS
Personal Finance Questions Beginners Often Ask
These answers address common decisions that come up when you are beginning to organize and manage your money.
What is the first step in managing your money?
Start by understanding your current financial picture. Identify your take-home income, regular expenses, debts, available savings, and important obligations. You do not need every number to be perfect before you begin.
Do beginners need a budget?
A budget or spending plan can be useful because it helps you decide how available income will be used. But budgeting is only one part of personal finance. Income, spending, savings, debt, credit, goals, and longer-term planning also matter.
Learn how to create a budget →Should I save money or pay off debt first?
There is no single answer that applies to everyone. The decision can depend on required payments, borrowing costs, available emergency savings, income stability, household risks, benefits, and upcoming expenses. Saving and debt repayment may also happen at the same time.
Learn more about building emergency savings →How do I manage money if I live paycheck to paycheck?
Begin with cash-flow visibility. List your take-home income, essential expenses, bills, due dates, and required debt payments. Compare when money comes in with when obligations must be paid, then identify which expenses and obligations are creating the gap and where any flexibility may exist.
When should a beginner start investing?
There is no universal milestone that makes investing appropriate for every person. Consider the goal, time horizon, need for access to the money, and your ability and willingness to accept investment risk. Money intended for a near-term need presents a different problem from money intended for a long-term goal.
Explore investing basics for beginners →CONTINUE YOUR JOURNEY
Where to Go Next
The best next article is not necessarily the most advanced one. Choose the topic that answers the financial question directly in front of you, then go deeper only where you need more detail.
BUDGETING
Money Runs Out Before the Month Ends
If your main challenge is making income cover bills, flexible spending, irregular expenses, and financial goals, continue with budgeting guidance.
SAVING
One Unexpected Bill Could Derail Your Finances
If an emergency, repair, or temporary income interruption would create a serious cash problem, continue with saving guidance focused on financial buffers.
BANKING
Bank Accounts or Fees Feel Confusing
If your next question is where to keep money, how bank accounts work, or how account fees and deposit products differ, move into Banking.
DEBT & CREDIT
Borrowing or Debt Is Limiting Your Options
If debt payments are crowding out other goals, use the appropriate debt guidance. If your question is about credit history, scores, cards, or borrowing mechanics, continue with Credit & Credit Cards.
INVESTING
Your Focus Is Long-Term Growth
If your next question is how investing works, how investment risk fits into long-term goals, or how to begin learning about portfolios and investment products, continue with Investing.
RETIREMENT
You Want to Prepare for Future Income
If your question is how to prepare financially for years when employment income may decrease or stop, continue with retirement planning.
STILL NOT SURE?
Start With the Question Directly in Front of You
You do not need to follow every category in a fixed order. If several areas are competing for attention, the Financial Triage Wizard can help you organize the pressure points and identify a practical next topic.
SOURCES & METHODOLOGY
How We Built This Guide
This guide was developed using primary consumer-finance and investor-education sources. Verestly used these references to verify the financial concepts discussed throughout the article, while keeping specialist topics at an introductory level and directing readers to deeper guidance where appropriate.
LAST REVIEWED
September 2026
This guide was reviewed for factual accuracy, source quality, beginner clarity, query ownership, and alignment with Verestly's Money Basics editorial framework.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical frameworks, and tools that help readers understand their options and make more informed money decisions.
View author profile →VERESTLY NEWSLETTER
Build Your Money Knowledge One Useful Step at a Time
Get beginner-friendly guides, financial tools, and practical resources designed to help you understand money decisions more clearly.
- Plain-language financial education
- New calculators and planning tools
- Practical next-step resources
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Guides
Continue with foundational guides that help you understand personal finance more broadly, build a workable budget, or prepare for unexpected expenses.