MONEY BASICS · FOUNDATIONS
What Is Personal Finance? A Beginner’s Guide to Managing Your Money
Learn what personal finance means, how the main areas of your financial life connect, and how to make more informed decisions about your money, priorities, and future goals.
QUICK ANSWER
The Short Answer
Personal finance is how you manage the money and financial resources in your life. It includes earning income, paying expenses, saving, borrowing, managing credit, paying taxes, investing, preparing for retirement, and working toward financial goals. These areas are connected, so understanding how they work together can help you decide what deserves your attention next.
What You'll Learn
- ✓ What personal finance means and why it matters.
- ✓ How income, expenses, and cash flow fit together.
- ✓ How financial goals, stability, and net worth differ.
- ✓ How saving, debt, credit, banking, taxes, investing, and retirement connect.
- ✓ How to identify a useful next financial priority without relying on one universal sequence.
FIND YOUR STARTING POINT
Where Should You Start?
Personal finance does not have one starting point that works for everyone. Your next step depends on what is happening with your money today. Use the situations below to identify the area that may deserve your attention first.
Everything feels financially urgent
If several money problems are competing for attention, start by separating immediate obligations from issues that can wait. This can make the next decision easier to see.
Find my first priority →I am not sure where my money goes
If money comes in but you are unsure what remains after bills and spending, start by understanding your income, expenses, and overall cash flow.
Understand my cash flow →I need a plan for my income and expenses
If you understand where your money is going but need a clearer plan for how to use it, budgeting can help you organize income, expenses, and competing priorities.
Learn budgeting basics →My current finances feel manageable
If your immediate obligations are manageable and you have room to think further ahead, you can begin exploring how longer-term goals and investing may fit into your financial life.
Explore investing →Your starting point can change as your income, obligations, risks, and goals change. These paths are educational starting points, not a universal financial sequence.
SEE THE SYSTEM
How Personal Finance Fits Together
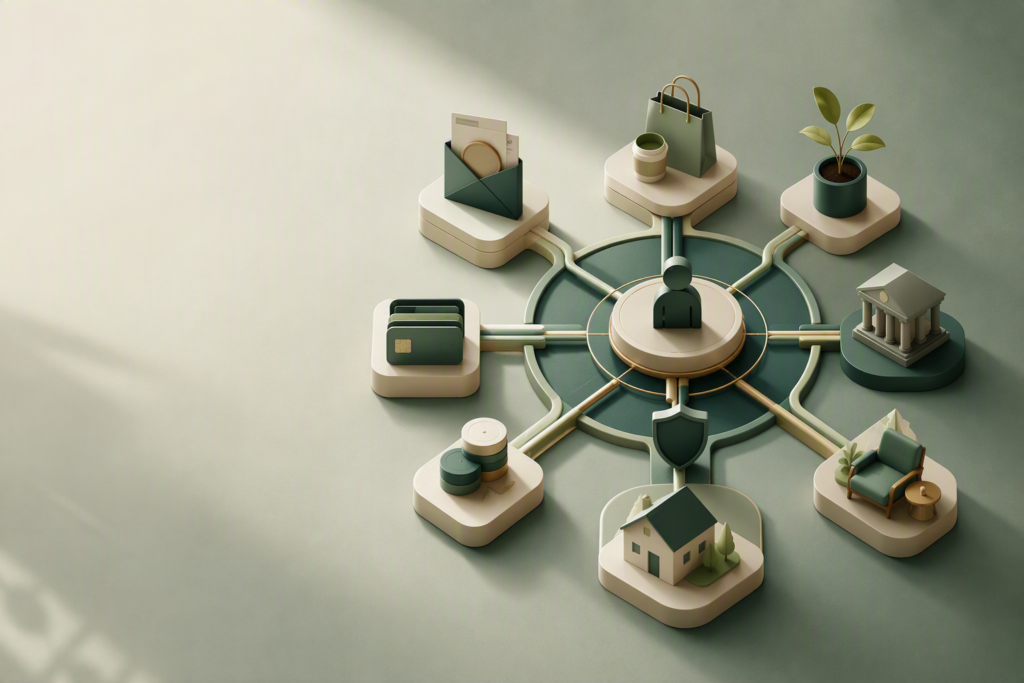
Personal finance is easier to understand when you see how income, spending, saving, debt, protection, and future goals interact. A change in one area can affect the choices available in several others.
Income
Money enters your financial life through work, benefits, business activity, investments, or other sources.
Cash Flow
Income moves through bills, everyday spending, debt payments, savings, and other financial commitments.
Financial Flexibility
What remains after current obligations can create room for savings, debt repayment, goals, or other priorities.
Financial Resilience
Savings, manageable obligations, and appropriate protection can make financial disruptions easier to absorb.
Future Goals
Available resources can support planned expenses, investing, retirement, and other longer-term goals.
The parts influence each other
Suppose your take-home income increases. That change could give you more room for current spending, savings, debt payments, an upcoming expense, retirement contributions, or another goal. The same dollars cannot usually support every priority at once, so financial decisions involve tradeoffs.
This does not mean everyone should follow the same financial sequence. Your most useful next step depends on your current obligations, risks, available resources, and goals. The purpose of the system is to help you understand those connections before deciding what deserves attention.
CORE PRINCIPLE
Personal finance is not a collection of isolated tasks. It is a connected system in which today's income, expenses, obligations, and choices shape the options available tomorrow.
BUILD THE FOUNDATION
The Core Building Blocks of Personal Finance
Personal finance becomes easier to understand when you break it into a few core concepts. These ideas help you see what is happening with your money before you move into more specialized topics such as budgeting, saving, credit, investing, or retirement.
CORE CONCEPT
Understand Your Income, Expenses, and Cash Flow
Cash flow describes how money moves into and out of your financial life. Income brings money in, while bills, everyday spending, debt payments, savings, and other commitments move money out.
A useful starting point is your take-home income—the amount available after taxes and other payroll deductions—compared with the money leaving your accounts. Understanding that pattern helps you see whether you have room for current obligations, future expenses, and other financial priorities.
KEY IDEA
Cash flow shows what is happening with your money over time. It is the foundation for many later financial decisions.
CORE CONCEPT
Separate Needs, Wants, and Financial Choices
A need is generally something required for basic living, health, safety, work, or an important obligation. A want usually improves comfort, convenience, enjoyment, or lifestyle but may offer more flexibility.
The distinction is not always absolute. Transportation may be essential, while the type of vehicle involves more personal choice. The goal is not to judge spending—it is to understand which expenses are less flexible when money becomes tight.
- Identify expenses that protect basic needs and obligations.
- Notice which costs have more room to adjust.
- Recognize that the same expense can serve different roles for different people.
- Use the distinction to understand tradeoffs rather than label spending as good or bad.
CORE CONCEPT
Connect Your Money to Financial Goals
A financial goal is an outcome you want your money to help you reach. Goals can include preparing for an upcoming expense, reducing debt, building savings, buying a home, paying for education, or preparing for retirement.
Different goals operate on different timelines. A bill due next month is not the same as a goal that may be decades away, and those differences affect how money may need to be managed.
CORE CONCEPT
Understand Financial Stability
Financial stability generally means having enough control and resilience to manage normal obligations while being better positioned to handle disruptions.
It does not necessarily mean having a high income or being wealthy. Stability can also depend on manageable expenses, financial reserves, debt obligations, access to resources, and the ability to absorb unexpected costs.
GO DEEPER How to Build a Strong Financial Foundation →CORE CONCEPT
Understand the Role of Debt and Credit
Debt is money you have borrowed and must repay. Because debt payments use future income, borrowing can directly affect your cash flow and the amount available for other financial goals.
Credit is broader. Your credit history and credit scores can influence how lenders evaluate borrowing risk and may affect the terms available to you. The detailed mechanics belong in Credit & Credit Cards, but understanding the distinction is part of the personal finance foundation.
CORE CONCEPT
Understand Saving, Investing, and Long-Term Planning
Saving and investing both involve setting aside money for future use, but they play different roles. Savings generally prioritizes accessibility and stability, while investing involves accepting risk in pursuit of potential long-term growth.
Retirement planning is another long-term part of personal finance and can involve workplace plans, individual accounts, personal savings, investments, and Social Security. The right approach depends on your goals, timeline, resources, and circumstances.
GO DEEPER Explore Beginner Investing Resources →VERESTLY FRAMEWORK
The Verestly Priority Lens
The Verestly Priority Lens is an educational framework for thinking about competing financial needs. It is not a universal financial sequence. Use it to identify which part of your financial life may deserve attention based on your current circumstances.
Understand Your Current Position
Look at your income, expenses, obligations, savings, debts, and near-term commitments so you can see what is happening with your money today.
Identify What Cannot Wait
Notice essential bills, payment deadlines, income disruptions, or other issues where delaying action could create immediate financial consequences.
Notice What Gets More Expensive
Interest, fees, penalties, and other costs can make some financial problems more expensive when they are left unaddressed.
Strengthen Financial Resilience
Consider what could make future disruptions easier to handle, such as clearer cash flow, savings, manageable obligations, or appropriate financial protection.
Connect Money to What Matters Next
Once immediate pressures are understood, consider which short-, medium-, or long-term goal deserves your attention based on your priorities and available resources.
THE CORE IDEA
These five lenses are not steps that everyone must complete in order. More than one may matter at the same time, and your priorities can change as your income, obligations, risks, and goals change.
REAL-LIFE EXAMPLE
What Personal Finance Can Look Like in Practice
Personal finance becomes easier to understand when you can see several financial areas interacting at the same time. This example shows how one person might evaluate income, expenses, savings, debt, and future goals without assuming there is one correct sequence for everyone.
STARTING POINT
Meet Jordan
Jordan takes home $3,800 per month, has some credit-card debt, limited savings, and usually has about $200 left after planned monthly expenses and debt payments.
That $200 creates choices. Jordan could use it for savings, additional debt repayment, an upcoming expense, or another goal. The useful question is which priority matters most given Jordan's current risks and obligations.
| Take-home pay | $3,800 |
|---|---|
| Essential expenses | $2,250 |
| Flexible spending | $750 |
| Debt payments | $420 |
| Other planned costs | $180 |
| Available monthly margin | $200 |
| Current emergency savings | $450 |
| Credit-card balance | $3,200 |
APPLYING THE PRIORITY LENS
How Jordan Can Evaluate the Next Decision
SEE
Confirm the Current Picture
Jordan checks whether the $200 margin is consistent and whether irregular expenses or upcoming bills are missing from the monthly snapshot.
URGENCY
Check What Cannot Wait
Jordan looks for essential bills, deadlines, or other short-term obligations that could create immediate consequences if ignored.
COST
Understand the Cost of Debt
Jordan reviews the credit-card balance, interest cost, minimum payment, and other terms to understand how the debt affects future cash flow.
RESILIENCE
Consider Financial Resilience
With only $450 in emergency savings, Jordan considers how an unexpected expense could affect the budget or lead to additional borrowing.
GOALS
Decide What the Money Needs to Do Next
After reviewing urgency, cost, and resilience, Jordan can decide whether the available margin should support savings, debt reduction, an upcoming expense, or another financial goal.
THE TAKEAWAY
The Same Numbers Can Lead to Different Priorities
Jordan's $200 monthly margin does not automatically belong to one category. A near-term bill, high borrowing costs, limited savings, or an important goal could each change the decision. Personal finance is about understanding those tradeoffs and choosing a next step that fits the situation.
This example is illustrative, not a recommendation. Real financial priorities depend on income, expenses, debt terms, available savings, deadlines, risks, and personal goals.
CHOOSE YOUR NEXT PRIORITY
What Might Deserve Your Attention Next?
There is no single financial priority that fits everyone. Your next step depends on your current obligations, risks, costs, and goals. Use the paths below as educational starting points for deciding which area may deserve attention.
IF THIS SOUNDS LIKE YOU
Essential bills are difficult to keep current
If housing, utilities, groceries, transportation, or other essential obligations are falling behind, understanding your immediate cash-flow pressures may be more useful than focusing first on longer-term financial goals.
IF THIS SOUNDS LIKE YOU
Bills are current, but unexpected costs are hard to absorb
If your regular obligations are manageable but an unexpected expense could force you to borrow or disrupt other bills, building financial resilience may deserve more attention.
IF THIS SOUNDS LIKE YOU
Expensive debt is using a large share of your cash flow
If interest and debt payments are limiting your flexibility, understanding the cost of that debt and how it affects your other goals may help you evaluate the next step.
IF THIS SOUNDS LIKE YOU
Your current obligations feel manageable and you are looking further ahead
If your cash flow is manageable and you have room to think beyond immediate needs, you may be ready to explore how longer-term saving, investing, or retirement goals fit into your broader financial plan.
NOT SURE WHICH PATH FITS?
Use the Financial Triage Wizard to Organize Your Priorities
Answer a few questions about your current financial situation to identify which areas may deserve closer attention. The tool is designed to support your thinking, not prescribe one universal financial sequence.
Free · Beginner-friendly · No complicated setup
FREE VERESTLY TOOL
Turn What You Learned Into a Clearer Next Step
If the concepts make sense but you are still unsure which area of your finances deserves attention, the Financial Triage Wizard can help you organize the situation and identify useful questions to explore next.
- ✓ Identify which parts of your financial situation may need closer attention.
- ✓ Compare urgency, financial cost, resilience, and your current goals.
- ✓ Get a simpler learning path without assuming one financial sequence fits everyone.
Free · Beginner-friendly · Takes only a few minutes
FIRST QUESTION
What is creating the most financial pressure right now?
PREFER A SIMPLE CHECKLIST?
Use the Beginner's Financial Checklist to review the core areas of your financial life and identify which topics you may want to learn more about.
PUT IT INTO ACTION
A 30-Day Personal Finance Check-In Plan
You do not need to overhaul your entire financial life in one month. Use this optional 30-day plan to understand your current position, improve visibility, review your priorities, and decide which financial topic deserves deeper attention next.
TODAY
15–30 minTake a Financial Snapshot
Review the basic numbers that describe your financial situation today. You are not trying to solve every problem; the goal is simply to understand your starting point.
- Check current bank and savings balances.
- Write down your monthly take-home income.
- List major bills, debt payments, and other obligations.
WEEK 1
Understand the flowUnderstand Your Cash Flow
Compare the money coming in with the money going out. Include regular expenses, flexible spending, debt payments, and costs that do not occur every month.
- Compare take-home income with normal monthly outflows.
- Notice which expenses are essential and which are more flexible.
- Identify irregular costs that could affect future months.
WEEK 2
Review prioritiesIdentify What Deserves Attention
Use the Verestly Priority Lens to review urgency, financial cost, resilience, and the goals that matter to you. More than one area may deserve attention at the same time.
- Notice any obligations with immediate consequences.
- Identify costs that may grow through interest, fees, or penalties.
- Consider where more financial resilience would be useful.
WEEK 3
Learn one areaGo Deeper on One Financial Topic
Choose the specialist topic that best matches the question you identified. That may be budgeting, saving, banking, debt, credit, taxes, investing, retirement, or another area.
- Pick one financial question to explore in more detail.
- Learn the basic terms and decisions involved.
- Avoid trying to optimize several areas at the same time.
WEEK 4
Choose what comes nextReview What You Learned and Choose a Next Step
Revisit your financial snapshot and decide whether anything has become clearer. Your next step may be a practical change, a new financial goal, or simply learning more about a specialist topic before making a decision.
- Review what became clearer during the month.
- Note any financial questions that remain unresolved.
- Choose one useful next learning or planning step.
KEEP IT SIMPLE
The Goal Is Clarity, Not a Perfect Financial Sequence
This 30-day plan is an educational starting point, not a rule everyone needs to follow. Keep the parts that improve your understanding and adapt the rest to your financial situation, priorities, and goals.
COMMON MISCONCEPTIONS
Personal Finance Myths That Can Make Money Harder to Understand
Beginners are often given financial rules that sound simple but leave out important context. Understanding where these ideas fall short can help you make decisions that better fit your actual situation.
Personal Finance Is Just Budgeting
Budgeting is important, but personal finance also includes saving, banking, debt, credit, taxes, investing, retirement, financial protection, and goals.
Think of budgeting as one part of a larger financial system rather than the whole system.
You Need a High Income Before Personal Finance Matters
A higher income may create more options, but understanding cash flow, obligations, tradeoffs, and goals can matter at many income levels.
Personal finance is about managing the resources you have and understanding the choices those resources create.
Everyone Should Follow the Same Financial Order
A useful next step for one person may be inappropriate for another because income, deadlines, debt costs, available savings, risks, and responsibilities differ.
Use rules of thumb as educational starting points, then evaluate urgency, cost, resilience, and your goals.
Net Worth Tells You Whether You Are Financially Successful
Net worth is useful, but it does not fully describe cash flow, available savings, financial stress, short-term obligations, or progress toward personal goals.
Treat net worth as one financial measurement alongside cash flow, liquidity, debt, and your current goals.
Personal Finance Is Mostly About Cutting Spending
Spending decisions matter, but personal finance also involves income, timing, debt costs, taxes, financial protection, saving, investing, and other tradeoffs.
Focus on how the entire financial system works rather than assuming every problem can be solved by spending less.
You Need to Be Good at Math to Manage Money
Basic arithmetic helps, but many financial decisions depend more on understanding tradeoffs, asking useful questions, planning ahead, and maintaining simple routines.
Start with a few useful numbers and concepts rather than trying to master complicated calculations.
FREQUENTLY ASKED QUESTIONS
Personal Finance Questions Beginners Often Ask
These short answers cover foundational questions about what personal finance includes, how its major concepts differ, and where to continue learning.
What is personal finance in simple terms?
Personal finance is how you manage the money and financial resources in your life. It includes earning, spending, saving, borrowing, managing credit, paying taxes, investing, preparing for retirement, and working toward financial goals.
Is personal finance the same as budgeting?
No. Budgeting focuses mainly on planning income and expenses. Personal finance is broader and also includes saving, banking, debt, credit, taxes, investing, retirement, protection, and financial goals.
Explore budgeting for beginners →What is the difference between cash flow and net worth?
Cash flow describes money coming in and going out over a period of time. Net worth is a snapshot of the value of your assets minus your liabilities at a particular point in time.
Learn more about cash flow →What are the main areas of personal finance?
Major areas include income, spending, budgeting, saving, banking, debt, credit, taxes, investing, retirement planning, financial protection, and goals. These areas overlap, so a decision in one can affect several others.
Where should a beginner start with personal finance?
A useful starting point is understanding your income, expenses, major obligations, available savings, and current goals. From there, identify which financial question is most relevant to your situation rather than assuming everyone should follow the same sequence.
Find a useful starting point →How often should I review my finances?
A simple monthly check-in can help you notice changes in income, expenses, upcoming obligations, and goals. Major life events or financial changes may justify reviewing your situation sooner.
Explore a monthly money review →CONTINUE YOUR JOURNEY
Where to Go Next
Personal finance covers several specialized areas, and you do not need to learn all of them at once. Choose the path that matches your current question and continue with the guide or resource that owns that topic in more depth.
BUDGETING
Organize Income and Spending
Follow this path if your next question is how to plan income, organize expenses, manage paycheck timing, or review how your spending plan is working.
SAVING
Learn How Saving Goals Work
Choose this path if you want to understand emergency savings, sinking funds, savings goals, or how to prepare for future expenses in more detail.
DEBT & CREDIT
Understand Borrowing and Credit
Use this path if your next question involves credit-card debt, credit scores, credit utilization, or how borrowing affects your wider financial picture.
INVESTING & RETIREMENT
Explore Longer-Term Financial Goals
Choose this path if you want to learn how investing, retirement planning, and longer-term goals fit into your financial life.
STILL NOT SURE?
Choose the Question That Matters Most Right Now
If several areas feel relevant, use the Financial Triage Wizard to organize the competing questions and identify a useful place to continue learning.
SOURCES & METHODOLOGY
How We Built This Guide
Verestly prioritizes primary government agencies, regulators, and official investor and consumer-education resources for factual financial claims. For this guide, those sources were used to verify concepts including financial well-being, cash flow, net worth, banking, credit, taxes, investing, and retirement.
LAST REVIEWED
September 2026
This guide was reviewed for factual accuracy, beginner clarity, source quality, editorial scope, and alignment with Verestly's Money Basics standards.

ABOUT THE AUTHOR
Edvaldo Ribeiro
Edvaldo Ribeiro creates beginner-focused personal-finance education for Verestly, with an emphasis on clear explanations, practical frameworks, and resources that help readers understand how different parts of their financial lives connect.
View author profile →VERESTLY NEWSLETTER
Keep Building Your Financial Knowledge
Get beginner-friendly guides, financial tools, and practical resources designed to make personal finance easier to understand one topic at a time.
- Clear financial education
- Useful calculators and tools
- Practical next-step resources
Free resources · Beginner-friendly · Unsubscribe anytime
KEEP LEARNING
Related Guides
Continue with guides that build on the personal-finance foundations covered here and help you explore your next financial question in more depth.